Shareholder Rights Group comment letter: Will the proxy ballot become a blank check for corporate insiders?
November 2, 2026
Read the submitted comment letter here.
Imagine arriving at your local polling place to find the candidates still on the ballot—but every ballot question proposed by fellow citizens has vanished.
A clerk tells you that, unless you object, your vote will be cast on unnamed, undisclosed ballot questions as officials currently in power choose.
No American would accept that arrangement at City Hall.
Investors will not accept that arrangement for corporate annual meetings, either.
To the Commission:
The Shareholder Rights Group is an association of investors, asset managers, faith-based institutions, and individual shareholders. We oppose the proposed rescission of Rule 14a-8 and amendments to Rule 14a-4, and urge the Commission to withdraw those proposals.[1]
The principle at stake is fundamental: federal law guarantees that investors be armed with the tools necessary to exercise intelligent judgment and voting on matters to be presented at corporate annual meetings, whether those investors vote by proxy or attend in person. They should be able to be fully informed as to what is being considered, be able to direct how their shares are voted, and have a meaningful opportunity to put proposals before fellow shareholders.
The Rule 14a-8 shareholder proposal process lets public-company owners manage risks that companies might otherwise minimize or neglect[2] and often serve as a critical early warning system on emerging risks facing a company. The rule has helped advance governance reforms such as majority-voting standards for directors, given shareholders a voice on executive pay, and brought transparency to climate-related financial risks.[3] As an example of a topic of current concern, it has also allowed shareholders to elevate questions about AI-related risks.[4] Investors and companies have relied on this rule for more than 80 years.
1. The rulemaking proposal subverts the central safeguard of the Securities Exchange Act: the right of shareholders to access tools that enable intelligent judgment and voting on matters raised at an annual meeting.
The release asserts that Rule 14a-8 exceeds the Commission’s statutory authority. The Commission’s own decisions and releases over eight decades, together with the legislative history, weigh heavily against that conclusion. The Securities Exchange Act was enacted to provide a federal solution to the failure of state laws to guarantee dispersed shareholders the tools necessary to exercise informed judgement and hold management accountable. The Act secured that right through federally regulated proxy materials. The Commission explained in its Sixth Annual Report (fiscal year ended June 30, 1940):
Where the stockholders are uninformed concerning the matters upon which the proxies are to be voted and where the proxy machinery is available only to the existing management, it is impossible for the average stockholder to protect his investment through intelligent participation in the determination of corporate policies. Accordingly, the general purpose of the proxy rules is to insure that security holders who are requested to authorize or consent to proposed corporate action are furnished with sufficient information to enable them to exercise an intelligent judgment on the matters involved, as well as an opportunity to indicate their approval or disapproval of such matters.
The fundamental requirement of the proxy rules is that corporate managements and others who solicit proxies, consents, or authorizations from security holders shall furnish to the security holders a proxy statement containing prescribed information as to each matter on which the proxies are to be voted. Furthermore, with certain exceptions, the persons soliciting such proxies, consents, or authorizations must give stockholders an opportunity to specify whether their proxies shall be voted for or against each proposal submitted. The Commission believes that the information now required to be disclosed in the proxy statement with respect to such vital matters as the election of directors, voluntary reorganizations, and mergers is the minimum which must be furnished to stockholders to enable them to act intelligently with respect to their investments.
The rules also require that managements give to minority stockholders an opportunity to present new proposals to their fellow stockholders. For example, a stockholder who desires to secure corporate action on a suggestion of his own can be assured that in most cases his proposal will be submitted to the other stockholders of the corporation if he gives timely notice to the management of his intention to present the matter at the annual meeting. [5] [Emphasis added].
Rule 14a-8 does not alter any shareholder right under state corporate law, and it does not displace state law. [6] Whether a shareholder may bring a proposal before a meeting remains a matter of state law and the company’s governing documents. A shareholder may raise the same proposal from the floor whether or not Rule 14a-8 exists. The rule also does not dictate corporate outcomes: most proposals are precatory, and a vote on them binds no one.
What Rule 14a-8 does regulate is the content of the company’s proxy statement—a federally mandated disclosure document and voting vehicle. Section 14(a) authorizes the Commission to prescribe rules governing proxy solicitation “as necessary or appropriate in the public interest or for the protection of investors.”
Congress enacted Section 14(a) to protect dispersed, poorly informed shareholders from being manipulated into signing blank proxies that leave insiders to cast important votes without meaningful investor direction. This is a basic safeguard. Shareholders should have information about what is being decided and the opportunity to cast their own votes, rather than surrendering voting authority on an uninformed basis.
Squarely within that authority is the ability to require management, when it solicits proxies for a meeting at which a shareholder proposal will be presented, to disclose that proposal and give shareholders a means to vote on it. The opportunity to exercise intelligent judgment on such matters expected to be raised in the annual meeting is dependent on accessing the full text of a qualifying proposal—currently limited to 500 words—and to exercise a choice by casting a vote on that item. Under the rulemaking proposal, the 500 words would disappear from the proxy statement. Shareholders would instead receive on a one line company-written description, buried in the proxy statement and no check boxes to vote for or against each proposal on the proxy card. Thus the rulemaking proposal would dismantle the safeguards of informed judgment: it would eliminate Rule 14a-8’s requirement for inclusion of proposals and supporting statements in company proxy materials as well as limit shareholders’ ability to vote on them on the proxy card.
The Commission suggests that states can give proposals proxy access, even though the federal law was established precisely because states were already a poor protector of informed proxy voting by dispersed shareholders. State-by-state rules risk a race to the bottom and different shareholder proposal rules at every company. Texas has already enacted a law that purports to let certain companies exclude proposals unless proponents hold $1 million in company stock and solicit holders of at least 67% of the voting power.[7] That threshold would reserve access for the wealthiest shareholders, not necessarily those with the most valuable ideas. The Commission in its administration of Rule 14a-8 has long recognized that the merits of an idea presented in a proposal do not depend on the proponent’s wealth.[8]
The Commission suggests that proponents would still have the option of raising proposals from the floor of a meeting under state law. But most shareholders vote by proxy and do not attend annual meetings. With Rule 14a-8 eliminated, reaching a company’s dispersed shareholders independently would require the proposals to prepare and distribute their own proxy materials at far greater cost than under Rule 14a-8, and likely at much greater marginal cost to both proponents and the company compared with inclusion of the proposal in the company’s own proxy statement that is already being transmitted to all company shareholders.[9] Retirees, individual investors, and small funds would face high barriers that would thwart most of their proposals from appearing on the proxy, while large investors who could theoretically afford the independent solicitations seldom need them because they can often reach boards directly without even filing proposals. [10] Eliminating Rule 14a-8 would silence those who depend on it most to file, and would deprive all shareholders of the opportunity to receive and vote on their proposals.
2. Rule 14a-8 rescission combined with Rule 14a-4 amendments would transform the proxy ballot into a blank check
Today, the proxy card gives shareholders a choice. Directors, management items, and shareholder proposals appear on the card, each with options to vote For, Against, or Abstain. Shareholders can review the questions and record their own decisions.
Under the combined Rule 14a-8 and Rule 14a-4 amendments, there would be far fewer shareholder proposals filed and a company would not have to put proposals on the proxy card. Instead it would have to include only a single, technical-sounding checkbox for withholding consent from management on discretionary voting. If a shareholder leaves the box unchecked, management would be able to vote that shareholder’s shares against any shareholder proposals presented at the meeting. The card would provide no direct way to vote for or against each proposal anticipated at the meeting.
This restores the conditions the Securities Exchange Act was enacted to prevent: poorly informed shareholders being manipulated into signing blank proxies that leave insiders to cast important votes without meaningful investor direction. Silence would be counted as consent.
3. Rule 14a-8 has guardrails that can be recalibrated to address policy concerns.
Rule 14a-8 has meaningful guardrails. Proponents must meet ownership requirements; proposals must satisfy relevance standards and generally cannot address ordinary business. Proposals are limited to 500 words, and those receiving low support face resubmission restrictions. Most are nonbinding, signaling shareholder priorities and informing boards without compelling company action.
The SEC’s institutional knowledge, labor and capacity embedded in the Rule has served investors, companies, and markets for more than 80 years. Jettisoning the rule would entail a harmful and disruptive elimination of that institutional knowledge and capacity, including the guardrails that investors and companies rely upon.
Across the decades of administration of the rule, the Commission has periodically recalibrated to address evolving issues in application of the rule. It has adjusted those guardrails from time to time to limit access to the federally regulated proxy statement even where state law might afford more flexibility in presenting floor proposals. For example, state law might tolerate individuals raising personal grievances or raising irrelevant proposals on the floor of a meeting. The SEC rules provide for exclusion of such proposals from the proxy statement – to protect the interests of the issuers in what appropriately appears in the proxy.
In its rulemaking release, the Commission makes a series of policy arguments about the current usage of the proposal process that are of the type that has caused the Commission in prior years to recalibrate filing and resubmission thresholds, and adjust other levers and exclusions of the rule for targeted improvements. The Administrative Procedure Act requires consideration of less harmful alternatives, reducing the costs, disruptions, risks and lost benefits that rescission would impose on those who are reliant upon the rule. The need for assessment of such alternatives was reinforced in the rulemaking petition we and other stakeholders submitted earlier this year.[11] The release fails to undertake a realistic and rigourous assessment of strategies for readjustment of the procedural and exclusion guardrails as a less harmful alternative.
Instead, the Commission proposes bulldozing decades of institutional knowledge and capacity, rescinding Rule 14a-8 and making it harder for investors to vote on proposals outside of Rule 14a-8. The entire approach of the release would undermine, not advance, the Commission’s investor-protection mission.
Our request
We ask the Commission to:
Withdraw the proposed rescission of Rule 14a-8 and amendments to Rule 14a-4;
Retain the requirement to include the full text of qualifying shareholder proposals in the proxy statement;
Retain the requirement to provide For, Against, and Abstain options for each duly submitted shareholder proposal on the proxy card.
Respectfully submitted,
Sanford Lewis
Director and General Counsel
The Shareholder Rights Group
REFERENCES
[1] We are submitting this letter as an initial top-level comment on the rulemaking. We intend to submit additional detailed comments before the November 20 deadline.
[2] As financial economist Michael C. Jensen observed, corporate reporting and market communications are often shaped by incentives to meet or beat market expectations rather than to present a full account of risk. Michael C. Jensen & Kevin J. Murphy, The Earnings Management Game: It’s Time to Stop It, Harvard Bus. Sch. NOM Unit, Working Paper No. 12-004 (Apr. 12, 2012), https://papers.ssrn.com/sol3/papers.cfm?abstract_id=1894304. Former SEC Chairman Arthur Levitt similarly warned in 1998 that the drive to satisfy earnings expectations could displace faithful representation with “a game of nods and winks.” Arthur Levitt, Chairman, U.S. Sec. & Exch. Comm’n, The “Numbers Game,” Remarks at the N.Y.U. Center for Law and Business (Sept. 28, 1998). https://www.sec.gov/newsroom/speeches-statements/spch220-numbers-game.
[3] Shareholder Rts. Grp., Interfaith Ctr. on Corp. Resp. & US SIF, Shareholder Proposals: An Essential Investor Right (Feb. 24, 2025), https://www.iccr.org/wp-content/uploads/2025/02/Shareholder-Rights-Group-Report-V20.1_Final.pdf. See also Sehr Khaliq & Timothy Smith, Shareholder Proposals as an Early Warning System for Corporate Risk, and the Cost of Ignoring Them, Harv. L. Sch. Forum on Corp. Governance (Oct. 8, 2026), https://corpgov.law.harvard.edu/2026/10/08/shareholder-proposals-as-an-early-warning-system-for-corporate-risk-and-the-cost-of-ignoring-them/.
[4] Subodh Mishra, Governing AI: Corporate Oversight and Shareholder Engagement, Harv. L. Sch. Forum on Corp. Governance (Oct. 6, 2026), https://corpgov.law.harvard.edu/2026/10/06/governing-ai-corporate-oversight-and-shareholder-engagement/.
[5] SEC, Sixth Annual Report of the Securities and Exchange Commission for the Fiscal Year Ended June 30, 1940, at 113-114 (1941), https://www.sec.gov/files/1940.pdf.
[6] See Shadow SEC, Shadow SEC Statement No. 16: Retain Rule 14a-8, CLS Blue Sky Blog (Oct. 13, 2026), https://clsbluesky.law.columbia.edu/2026/10/13/shadow-sec-statement-no-16-retain-rule-14a-8/.
[7] Tex. Bus. Orgs. Code Ann. § 21.373 (West 2025), https://law.justia.com/codes/texas/business-organizations-code/title-2/chapter-21/subchapter-h/section-21-373/. The law also gives the option of owning 3% of a corporation’s voting shares in lieu of $1 million.
[8] In fact, some of the most widely supported corporate governance reforms originated with small, individual shareholders such as John Chevedden and James McRitchie who have, for decades, consistently submitted proposals that receive high levels of approval, often winning majority support from shareholders. Timothy Smith, Individual Investors Filing Shareholder Resolutions Have Had A Significant and Impactful Role in Encouraging Good Corporate Governance, Harv. L. Sch. Forum on Corp. Governance (Sept. 10, 2026), https://corpgov.law.harvard.edu/2026/09/10/individual-investors-filing-shareholder-resolutions-have-had-a-significant-and-impactful-role-in-encouraging-good-corporate-governance/; Alyce Lomax, People Power in Corporate America, https://www.fool.com/investing/general/2010/07/21/people-power-in-corporate-america.aspx (last updated Apr. 6, 2017).
[9] SOC Investment Group, The SEC says shareholders will still have a voice through independent solicitations, LinkedIn (Oct. 29, 2026), https://www.linkedin.com/feed/update/urn:li:activity:7521208021126004736/.
[10] Joseph McCahery, Corporate Governance Preferences of Institutional Investors, Harv. L. Sch. Forum on Corp. Governance (Sept. 10, 2015), https://corpgov.law.harvard.edu/2015/09/10/corporate-governance-preferences-of-institutional-investors/. The authors surveyed 143 mostly very large, long-term institutional investors in 2015. The respondents reported that, over the prior five years, 63% had engaged in direct discussions with management, and 45% had held private discussions with a company’s board outside management’s presence.
[11] Ceres et al., Petition Regarding Amendments to Rule 14a-8 Under the Securities Exchange Act of 1934, SEC File No. 4-917 (July 23, 2026), https://www.sec.gov/files/rules/petitions/2026/petn4-917.pdf.
Shadow SEC Statement No. 16: Retain Rule 14a-8
By John Coates, John C. Coffee, Jr., James D. Cox, Merritt B. Fox and Joel Seligman October 13, 2026
We oppose rescission of SEC Rule 14a-8.
Rule 14a-8 has for 80 years been a useful, congressionally authorized component of the U.S. capital markets, fully compatible with the long-standing dual state and federal system governing public companies. Reasonable people may disagree reasonably about whether the current version of Rule 14a-8 is perfectly calibrated to obtain the greatest net benefits. We do not agree that the Commission has come close to making the case that Rule 14a-8 does not provide any net benefits whatsoever, much less that wholesale repeal will provide more net benefits than either the status quo or reasonable alternatives to the current rule.
There are many policy reasons to oppose rescission. Most obviously, proposals under Rule 14a-8 have been approved by shareholders numerous times on topics core to corporate governance, such as majority-board election requirements and classified boards—persuasive evidence (not seriously discussed in the proposing release) of the value of allowing shareholders to communicate via proxy statements and votes on matters of common interest. Many other proposals have received enough supporting votes to signal to boards the need for attention to specific topics, and boards have responded to those signals. Many other proposals have received few positive votes, and have failed to receive more votes over time, providing feedback to sponsoring shareholders that proposals need to be refined, improved, or dropped.
Also important to any serious analysis would be an informed and good faith attempt to anticipate what would follow from rescission. We are confident that shareholders will not sit by silently as boards mismanage or misgovern their companies or rely on the “Wall Street rule” (of exit), especially given how many institutional investors are not permitted by their own commitments to sell. When, predictably, at least some companies are seen to be underperforming or engaged in poor decisions, shareholders will use alternative tools in lieu of Rule 14a-8 proposals. Those tools may well disrupt corporate governance far more than non-binding proposals submitted under Rule 14a-8. Proxy fights, coalitions with hedge fund activists, withhold-vote campaigns, negative votes on management proposals, shareholder-sponsored binding bylaw amendments, and lawsuits are among those tools. Say-on-pay votes will continue as they are mandated by statute. The current release almost entirely fails to treat these possibilities with the attention they deserve. We also note the SEC made a major change in how it implemented Rule 14a-8 just a year ago, and it does not adequately review facts about the effects of that change in its current rule proposal.
But the Commission’s own release presents policy reasons for repeal as secondary to its legal rationale. The Commission contends that Rule 14a-8 exceeds the Commission’s authority under Section 14(a) of the Securities Exchange Act of 1934 and improperly intrudes on a domain long reserved to the states. In the interest of brevity, the rest of this statement focuses on the SEC’s legal rationale, which provides an independent and sufficient basis for rejecting it.
That justification is wrong on its own terms. Rule 14a-8 does not create any substantive right enforceable under state corporate law, and it displaces nothing that state law otherwise governs. Proposals included under the rule are precatory; they bind no one, alter no charter, and effect no corporate action that state law does not already fully control. What the rule actually regulates is the content of a federal disclosure document—the company’s own proxy statement—a subject squarely within the Commission’s Section 14(a) authority since 1934. A shareholder has always been free to raise the identical resolution from the floor of a meeting; Rule 14a-8 only concerns whether that proposal may also appear in the company’s proxy materials. That is a question about the scope of a federal communications channel, not an intrusion into state corporate governance.[1] The fact that in-person attendance at meetings had ceased to be a meaningful way for shareholders to exercise voting rights was evident in 1934 and is not a change that can justify a rescission of a long-standing rule on any ground, much less legal authority.
The U.S. House Commerce Committee report accompanying the Securities and Exchange Act of 1934 responded to a proxy system described by critics as “a self-perpetuation and a self-approval device” for incumbent management, [2]and the companion Senate report complained that “[t]oo often proxies are solicited without explanation to the stockholder of the real nature of the questions for which authority to cast his vote is sought.”[3] The House report grounded the proxy provisions on the idea of “fair corporate suffrage”[4]—the notion that a shareholder’s formal voting right meant little in practice if the only practical mechanism for exercising it (the proxy) was controlled entirely by management, unconstrained by any disclosure or fairness requirement. The stated purpose of what became Section 14(a) was to give the Commission “power to control the conditions under which proxies may be solicited with a view to preventing the recurrence of abuses which have frustrated the free exercise of the voting rights of stockholders.”[5]One clear gap was the inability of many shareholders to communicate with each other about shareholder resolutions and other topics of interest, because as their numbers grew, their ability to do so at a state-law-mandated shareholder meeting had steadily diminished.
Rule 14a-8 addresses another gap in disclosure when (as customary) a corporation solicits the authority to vote shareholders’ shares on any matter that may arise at a shareholder meeting. If such requests are made with corporate knowledge that a shareholder intends to seek action on a proposal at the meeting, the corporation would need to communicate its position about the proposal as part of its proxy solicitation. Without that disclosure, the corporation risks material omission liability, and shareholders risk having their authority misused to vote on an uninformed basis. Rule 14a-8 governs that process with guardrails that protect companies and shareholders alike in the state-law based voting process.[6] The SEC’s proposing release does not adequately consider how this goal of the rule would be addressed in its absence.
Nothing about modern corporate governance has eliminated the need for shareholders to communicate with each other to instruct and oversee proxies or engage in informed governance with full disclosure—a core mandate of the securities laws. No statute bearing on that fundamental need has relevantly changed since Rule 14a-8 was adopted in 1942 to partly address the gaps emphasized by Congress. The Commission does not identify any statutory change of note, nor any case law casting meaningful doubt on the legality of Rule 14a-8.[7] To the contrary, more than a dozen decisions have held or presumed over the past 80 years that Rule 14a-8 or its predecessor was and remains authorized.[8] The SEC does nothing to address much less dismiss that contrary body of law,[9] or the plain language of the statute it purports to interpret. The SEC’s only attempt to invent a justification for its volte face is to stress the fact that proxy communications have “effectively” or “de facto” displaced resolutions made in person at shareholder meetings. But that fact was a logical result of and contemplated by the Securities Exchange Act of 1934 itself, and it has been a fact for decades. It is not a new fact that somehow justifies drastically re-interpreting the authority the statute gives the SEC. Proposals made under Rule 14a-8 continue to have only the legal effect given to them under state corporate law, and the Commission’s efforts to suggest otherwise are supported by no facts.
An agency that reverses an 80-year, consistently applied interpretation of its own authorizing statute without pointing to any intervening change in the law—whether statute or governing case law—mischaracterizing the practical effect of its own rule, has not offered the “reasoned explanation” the Administrative Procedure Act requires for changed agency positions.[10] The most basic element of legal reasoning is to consider opposed arguments and authorities. The same is true for “reasoning” under the APA. A final rule resting on the SEC’s current rationale would be vulnerable to vacatur as arbitrary and capricious.
The Commission may believe that Loper Bright Enterprises v. Raimondo[11] supports its position, since that decision holds that courts owe no deference to an agency’s interpretation of the statutes it administers. But Loper Bright cuts the other way. Its lesson is that an agency’s legal interpretation must now stand or fall on the merits of its reasoning, not on the agency’s say-so.[12] The interpretation offered in this release does not stand on its merits: It is thinly reasoned and unsupported by serious legal analysis, and it reads far more naturally as a restatement of the political commitments of the current single-party Commission than as an exercise of the Commission’s expertise in administering Section 14(a). Loper Bright confirms this proposal is entitled to zero deference from a reviewing court.
The Commission should withdraw the proposal.
ENDNOTES
[1] “Where … the Commission has prescribed a rule under its clear authority to regulate the proxy process, it cannot be said that “the [Commission]’s assertion of authority directly invades the ‘firmly established’ state jurisdiction over corporate governance and shareholder voting rights.” Interfaith Ctr. on Corp. Resp. v. SEC, 786 F. Supp. 3d 97, 135 (D.D.C. 2025) (quoting Bus. Roundtable v. Sec. & Exch. Comm’n, 905 F.2d 406, 413 (D.C. Cir. 1990) (quoting CTS Corp. v. Dynamics Corp. of Am., 481 U.S. 69, 89 (1987))).
[2] Sheldon E. Bernstein & Henry G. Fischer, The Regulation of the Solicitation of Proxies: Some Reflections on Corporate Democracy, 7 U. Chi. L. Rev. 226, 227 (1940). See also H.R. Rep. No. 1383, 73d Cong., 2d Sess., 13 (1934) (“Fair corporate suffrage is an important right that should be attached to every equity security bought on a public exchange,” and that management “should not be permitted to perpetrate themselves by the misuse of corporate proxies.”)
[3] S. Rep. No. 1455, 73d Cong. 2d Sess. 75 (1934).
[4] H.R.Rep. No. 1383, 73d Cong., 2d Sess., 13 (1934).
[5] Id. at 14.
[6] E.g., SEC v. Transamerica Corp., 67 F. Supp. 326 (D. Del. 1946) (requiring re-solicitation of proxies by company given its knowledge of planned shareholder proposals, upholding predecessor of Rule 14a-8), aff’d, 163 F.2d 511 (3d Cir. 1947); cf. New York City Emps. Ret. Sys. v. Am. Brands, Inc., 634 F. Supp. 1382, 1386 (S.D.N.Y. 1986) (stating that omission of a shareholder proposal from proxy materials in violation of Rule 14a-8 is “inherently misleading”).
[7] The SEC cites Santa Fe Industries, Inc. v. Green, 430 U.S. 462, 479 (1977) and Bus. Roundtable v. SEC, 905 F.2d 406, 410 (D.C. Cir. 1990). Neither addressed Rule 14a-8. Santa Fe limits its focus to areas “where established State policies of corporate regulation would be overridden.” Id. at 479. Few states have elaborated rules for when shareholder proposals may or must be included in company proxy statements, and nothing about Rule 14a-8 would override any state laws that are adopted to do so. Business Roundtable stresses a point that undercuts the SEC’s current legal position: “Proxy solicitations are, after all, only communications with potential absentee voters. The goal of federal proxy regulation was to improve those communications and thereby to enable proxy voters to control the corporation as effectively as they might have by attending a shareholder meeting.” 905 F.2d at 410 (emphasis in original).
[8] S See, e.g., Roosevelt v. E.I. du Pont de Nemours & Co., 958 F.2d 416, 422–23 (D.C. Cir. 1992) (“It is obvious to the point of banality . . . that Congress intended by its enactment of [S]ection 14 . . . to give true vitality to the concept of corporate democracy.”); Grimes v. Centerior Energy Corp., 909 F.2d 529 (D.C. Cir. 1990); Med. Comm. for Human Rts. v. SEC, 432 F.2d 659 (D.C. Cir. 1970), vacated as moot, 404 U.S. 403 (1972); AFSCME v. Am. Int’l Grp., Inc., 462 F.3d 121 (2d Cir. 2006); Trinity Wall St. v. Wal-Mart Stores, Inc., 792 F.3d 323 (3d Cir. 2015); SEC v. Transamerica Corp., 163 F.2d 511 (3d Cir. 1947); Dyer v. SEC, 266 F.2d 33 (8th Cir. 1959); As You Sow v. Chubb Ltd., No. CV 26-734 (SLS), 2026 WL 879666 (D.D.C. Mar. 31, 2026); Interfaith Ctr. on Corp. Resp. v. SEC, 786 F. Supp. 3d 97 (D.D.C. 2025); United Church Bd. for World Ministries v. SEC, 617 F. Supp. 837 (D.D.C. 1985); Lovenheim v. Iroquois Brands, Ltd., 618 F. Supp. 554 (D.D.C. 1985); SEC v. Transamerica Corp., 67 F. Supp. 326 (D. Del. 1946), aff’d, 163 F.2d 511 (3d Cir. 1947); Tosdal v. Nw. Corp., 440 F. Supp. 3d 1186 (D. Mont. 2020); Amalgamated Clothing & Textile Workers Union v. Wal-Mart Stores, Inc., 821 F. Supp. 877 (S.D.N.Y. 1993); N.Y. City Emps.’ Ret. Sys. v. Am. Brands, Inc., 634 F. Supp. 1382 (S.D.N.Y. 1986); Peck v. Greyhound Corp., 97 F. Supp. 679 (S.D.N.Y. 1951); KBR Inc. v. Chevedden, 776 F. Supp. 2d 415 (S.D. Tex. 2011); Apache Corp. v. N.Y.C. Emps.’ Ret. Sys., 621 F. Supp. 2d 444 (S.D. Tex. 2008); see also CA, Inc. v. AFSCME Emps. Pension Plan, 953 A.2d 227 (Del. 2008).
[9] Indeed, it cites only three court decisions and provides no reasons to reject the settled legal understandings reflected in any of those decisions, merely stating “the Commission disagrees.”
[10] See FCC v. Fox Television Stations, Inc., 556 U.S. 502, 529 (2009); Motor Vehicle Mfrs. Ass’n v. State Farm, 463 U.S. 29, 42 (1983).
[11] 144 S. Ct. 2244 (2024).
[12] See id. at 392 (explaining that under Section 706 of the APA, “it thus ‘remains the responsibility of the court to decide whether the law means what the agency says'” (quoting Perez v. Mortg. Bankers Ass’n, 575 U.S. 92, 109 (2015) (Scalia, J., concurring in judgment)).
This post comes to us from the Shadow SEC, whose members are professors John Coates at Harvard Law School, John C. Coffee, Jr. at Columbia Law School, James D. Cox at Duke University School of Law, Merritt B. Fox at Columbia Law School, and Joel Seligman at Washington University School of Law.
The SEC’s Proposal to Eliminate Rule 14a-8 Removes Accountability
Oct 09, 2026
Watering down financial regulations makes it easier for companies to put profits over people.
Some background: State treasurers like me are sounding the alarm on the Trump administration’s proposal to eliminate a safeguard that has given investors a voice for more than 80 years: Rule 14a-8. This gives eligible shareholders the ability to include qualifying proposals in a company’s proxy materials, the documents investors receive before voting at an annual meeting. In doing so, eligible shareholders can raise concerns with the companies they own and bring those concerns before other investors.
The SEC’s proposal to eliminate Rule 14a-8 is a direct threat to the rights of long-term investors, and I am concerned it will curtail our ability to hold public companies accountable.
Accountability to shareholders is the foundation of public markets, and engaged shareholders make companies stronger. Weakening the federal shareholder proposal process is not going to make the sustainability risks for companies go away. It’s just going to make it harder for shareholders to raise them.
Listen to my remarks on a For the Long Term press all about the SEC rule change.
As Illinois’ Chief Investment and Banking Officer, I have a responsibility to protect the interests of taxpayers, retirees, and college savers. Shareholder proposals are an important tool for ensuring that companies address material risks that can affect workers, consumers, communities, and investors alike. They are also a key tool for engaging with boards to make sure their actions and oversight align to driving long-term durable returns.
The SEC should be protecting investors, not making it easier for companies to avoid accountability, and I strongly oppose this proposal and urge the Commission to preserve Rule 14a-8 and the shareholder rights it protects.
I have used shareholder proposals to encourage stronger health and safety practices at companies, to advocate for corporate boards to prioritize patients and quality of care when providing healthcare, and to enhance board oversight of material sustainability risks. Eliminating this rule will not make financial, governance, or operational risks disappear. It will simply make them harder and more expensive to flag. Replacing a uniform federal framework with a complex patchwork of state laws and company-by-company rules will increase inefficiencies, costs, and disputes.
Let me offer an example of this process working correctly. In 2023 and 2024, my Office supported shareholder proposals filed by Proxy Impact that called for Meta to assess child safety and implement harm reduction measures on Meta platforms. Two years later, the issue of child safety poses a significant risk to Meta, including recent lawsuits and fines. This illustrates how shareholders can use proposals to raise material risks to companies. We shouldn’t make it harder for shareholders to do so.
Shareholder proposals also are a useful tool for State Treasurers to lead constructive and collaborative dialogue with companies. A couple years ago, we filed shareholder proposals at Southwest & American Airlines over health and safety concerns among their employees and contracted employees, including heat stress for workers on the tarmac. The airlines made commitments, and we withdrew the shareholder proposals.
Since then, we have continued to work with both companies to enhance their disclosure on health and safety, including providing input on their annual sustainability reporting and what would be most helpful for the companies to disclose. One of the companies committed to obtaining an Operational Safety audit when we withdrew the proposal and has since then obtained it. That’s an important step towards keeping employees safe.
This SEC proposal to do away with a rule that has worked since 1942 is part of the Trump administration’s continuing demolition of guard rails. We have seen time and again Trump gutting the rules to put money in the pockets of his family and his cronies. The president is enriching the Trump family over the interest of all Americans. Watering down financial regulations makes it easier for companies to put profits over people.
The SEC should not make its limitations to the 14a-8 process permanent or eliminate its shareholder proposal framework. I am calling on the SEC to protect retirees, pension beneficiaries, individual investors and families saving for their child’s college education by keeping the rules in place.
The SEC’s comment period is currently scheduled to close on November 20, 2026. Submit a comment urging the Commission to preserve Rule 14a-8.
SEC Quorum Rule: A Commission of One, Adopted Without Public Comment
James McRitchie, 09/30/2026
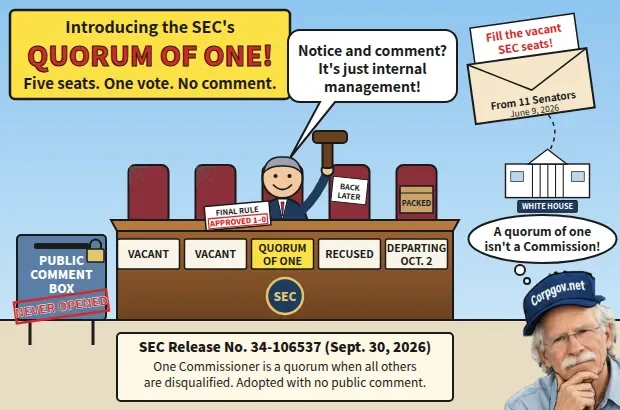
On September 30, 2026, the SEC changed who gets to decide things at the SEC. It did not propose the change. It didn’t ask for comments. It simply adopted a final rule, effective on publication, that lets a single Commissioner act as the entire Commission whenever every other Commissioner is disqualified from a matter.
Congress created a five-member, bipartisan Commission. The SEC has now decided, on its own and without public input, that one person can be enough.
In California, where I once headed rulemaking at a state agency, we called rules adopted without going through the required process “underground regulations.” The federal version has a different name, but the problem is the same: the public was shut out of a decision that affects everyone the SEC regulates.
A Quorum of One – and Music for a Democratic Corporate Governance
What the SEC Did
The amendment (Release No. 34-106537) rewrites 17 CFR 200.41, the Commission’s quorum rule. Since 1995, three Commissioners have made a quorum. If fewer were in office, the number in office did. If disqualifications left two able to act, two could. But in 1995, the Commission expressly declined to go further, saying it did not believe it necessary to let one Commissioner constitute a quorum.
The new rule does exactly that. And the stated purpose is not internal housekeeping. The release says the amendment is “designed to promote flexibility and finality of agency rulemaking.”
Yet the SEC skipped notice and comment by calling it a rule of “agency management and organization” that does “not substantially affect the rights or obligations of non-agency parties.” A rule designed to make it easier to finalize rules that bind investors, companies, and markets does not fit that description.
Why the Timing Matters
No Democratic Commissioner has served since early 2026.
Two seats have remained vacant, although nothing prevents the President from nominating, and the Senate from confirming, Democrats to fill them.
Commissioner Hester Peirce has reportedly announced her departure effective October 2, 2026, two days after this rule was adopted.
If no successor is confirmed, two Commissioners will remain, both of the same party. Under the new rule, whenever one is disqualified, the other can act alone for the Commission.
I do not assume how any Commissioner would use this power. The problem is structural. Powers Congress gave to a bipartisan commission could be exercised by one person.
A Quorum of One Is Not a Commission
A quorum is the minimum number of members needed for a body to act. It is plural by definition. One person cannot deliberate with himself.
The D.C. Circuit upheld the SEC’s existing rule in Falcon Trading Group v. SEC (1996), when only two Commissioners were in office. But the court relied on the common-law rule that “a majority of a quorum constituted of a simple majority of a collective body” may act. One Commissioner ia not a simple majority or two and one acting alone is not a collective body. Falcon does not bless this.
Even the Commissioners Say Bipartisanship Matters
On June 9, 2026, Senators Raphael Warnock and Chris Van Hollen, joined by Banking Committee Ranking Member Elizabeth Warren and eight other Democratic senators, wrote to the White House urging it to fill the vacant seats. “A full slate of commissioners and board members can bring a range of perspectives to policies that shape our markets,” they wrote. “No practical barrier prevents the President from next appointing a Democrat to the SEC.” They noted Chairman Atkins has said he is “supportive of having a full complement of commissioners, as it helps with debates and everything else.”
Commissioners themselves have said the same:
Commissioner Mark Uyeda (2022): “The Commission is structurally designed to promote regulation that is the product of consideration by five individuals with different perspectives.”
Commissioner Daniel Gallagher (2013): “Congress created the SEC as a bipartisan, five-member Commission and gave each Commissioner — including the Chairman — only one vote.”
Commissioners Peirce, Crenshaw, and Uyeda, jointly (2025): “Although as Commissioners we approached policy issues from different perspectives, there was always dignity in our differences.”
A quorum of one eliminates the different perspectives they valued.
What’s at Stake for Shareholders
The SEC has proposed rescinding Rule 14a-8, ending the federal requirement that companies include qualifying shareholder proposals in their proxy statements, a right investors have relied on since 1942. Under the new quorum rule, a final rule of that consequence could be adopted by a single Commissioner if the others were disqualified.
Rules that reverse decades of settled policy are exactly where deliberation matters most. A major rule adopted by one Commissioner, or by members of one party alone, may also be more vulnerable to challenge and to reversal by a future Commission. That undercuts the very “finality” the SEC says it wants.
The answer to vacancies is to fill them. It is not to redefine the Commission so that one member can act for all five.
Media Coverage
What I’ve Done, and What You Can Do
Because the SEC didn’t open a comment period, I filed a petition for rulemaking under Rule 192 of the SEC’s Rules of Practice, asking the Commission to rescind the amendment, or at a minimum, suspend it and put it out for public comment. You can read it here: [Comment on Release No. 34-106537]. I also filed a copy in the Rule 14a-8 rescission file (S7-2026-32), because the quorum rule bears directly on who may adopt a final rule there.
My petition also asks the SEC to:
limit any single-member authority to ministerial or time-critical matters, excluding rulemaking, enforcement authorizations, and contested adjudications;
define “otherwise disqualified” and publicly disclose every disqualification that produces a one- or two-member quorum; and
defer final action on major rulemakings, including the Rule 14a-8 rescission, until the Commission has at least three members, including at least one not of the majority party.
You can help:
Support the petition. Once the SEC posts it on its petitions page, file a comment. Until then, email your views to rule-comments@sec.gov, referencing Release No. 34-106537.
Raise it in the Rule 14a-8 file. If you’re commenting on the proposed rescission (S7-2026-32, due November 20), ask the SEC not to finalize it with fewer than three Commissioners.
Contact the Senate Banking Committee. Call (202) 224-7391 and tell them you support their call to fill the vacant seats, which both Republicans and Democrats supported in their letter of June 9, 2026.
The SEC’s legitimacy rests on the deliberation Congress built into it. A Commission of one isn’t what Congress designed, and it isn’t what investors deserve.
Sources
SEC, Commission Quorum Requirement, Release No. 34-106537 (Sept. 30, 2026).
SEC, Establishment of Commission Quorum Requirement, Release No. 34-35548 (1995).
Letter from Sens. Warnock, Van Hollen, et al. (June 9, 2026).
Falcon Trading Group v. SEC, 102 F.3d 579 (D.C. Cir. 1996).
Commissioner Uyeda, SEC Speaks remarks (Sept. 9, 2022); Commissioner Gallagher, remarks (Feb. 22, 2013); Statement of Commissioners Peirce, Crenshaw, and Uyeda (Jan. 20, 2025).
Holland & Knight, “Low Tide at the SEC: From Five Commissioners to Two” (July 2026).
The Investors Weigh In on Rescinding Rule 14a-8
Dave Lynn, September 23, 2026
The SEC’s proposal to rescind Rule 14a-8 prompted a swift response from the Council of Institutional Investors (CII). On the same day that the proposal was issued, CII Executive Director Glenn Davis issued a statement, bluntly noting:
Let this moment settle in: The SEC, created for the purpose of protecting investors in the aftermath of the Crash of 1929, today proposed to rescind a World War II-era rule protecting shareholders’ ability to suggest ideas to improve the companies they own.
Yes, shareholder proposals can be a source of embarrassment when they reveal a disconnect between shareholders’ and managers’ understandings of what matters to long-term performance; and sometimes they trigger compromise before a vote takes place. That is a feature of strong capital markets, not a basis for a government agency to swat a fly with a sledgehammer.
The proposed rescission is a solution in search of a problem. Nearly all shareholder proposals are non-binding, which means they merely give corporate directors data to make better-informed decisions. Company costs related to shareholder proposals trace largely to self-imposed expenses such as pursuing legal cover to exclude proposals from ballots or funding campaigns to get out the “against” votes. Most publicly traded companies face zero shareholder proposals in a given year.
Could Rule 14a-8 be improved? Sure. But the SEC proposed rescinding the rule in its entirety, with fingers crossed that state legislators and corporate directors will develop a patchwork of new rules resulting in something better. Spoiler alert: That patchwork will launch a new race to the bottom in state corporate law and result in a dramatic reduction in shareholders who qualify as proponents, notwithstanding smaller investors’ history of putting forward many of the most highly supported proposals.
CII will speak publicly and repeatedly to defend Rule 14a-8. We encourage all market participants to do their part in this effort. It’s not about whether you agree or disagree with the substance of particular shareholder proposals. It’s about preserving broad shareholder expression as a vital part of robust capital markets.
Meanwhile, the comments are already starting to pour in on the SEC’s proposal. Trillium Asset Management, LLC submitted a comment letter this week requesting that the Commission extend the public comment period from 60 days to 120 days, while asking the Commission to convene a public roundtable “to gather the views of investors before proceeding further.” These requests were subsequently echoed in a comment letter submitted by the Committee on Mission Responsibility Through Investment, part of Presbyterian Life & Witness, an agency of the General Assembly of the Presbyterian Church.
Statement by CII Executive Director Glenn Davis on the SEC’s Proposed Rescission of Rule 14a-8
Washington, D.C., Sept. 16, 2026
Let this moment settle in: The SEC, created for the purpose of protecting investors in the aftermath of the Crash of 1929, today proposed to rescind a World War II-era rule protecting shareholders' ability to suggest ideas to improve the companies they own.
Yes, shareholder proposals can be a source of embarrassment when they reveal a disconnect between shareholders' and managers' understandings of what matters to long-term performance; and sometimes they trigger compromise before a vote takes place. That is a feature of strong capital markets, not a basis for a government agency to swat a fly with a sledgehammer.
The proposed rescission is a solution in search of a problem. Nearly all shareholder proposals are non-binding, which means they merely give corporate directors data to make better-informed decisions. Company costs related to shareholder proposals trace largely to self-imposed expenses such as pursuing legal cover to exclude proposals from ballots or funding campaigns to get out the "against" votes. Most publicly traded companies face zero shareholder proposals in a given year.
Could Rule 14a-8 be improved? Sure. But the SEC proposed rescinding the rule in its entirety, with fingers crossed that state legislators and corporate directors will develop a patchwork of new rules resulting in something better. Spoiler alert: That patchwork will launch a new race to the bottom in state corporate law and result in a dramatic reduction in shareholders who qualify as proponents, notwithstanding smaller investors' history of putting forward many of the most highly supported proposals.
CII will speak publicly and repeatedly to defend Rule 14a-8. We encourage all market participants to do their part in this effort. It's not about whether you agree or disagree with the substance of particular shareholder proposals. It's about preserving broad shareholder expression as a vital part of robust capital markets.
Shareholder Proposals and Corporate Governance in a Season of Regulatory Uncertainty
Access the full text here.
Executive Summary
In the 2026 proxy season, the Securities and Exchange Commission (SEC) Division of Corporation Finance upended a long-standing practice of issuing informal decisions on whether shareholder proposals are excludable by the companies receiving them.
Although the SEC shareholder proposal rule, Rule 14a-8, remained in force, the SEC’s administrative dispute resolution mechanism—neutral staff review through the no-action process—was gone. The Division cited resource constraints and the sufficiency of existing guidance to justify suspending the no-action process for the current proxy season. As it stated on November 17, “due to current resource and timing considerations… as well as the extensive body of guidance from the Commission and the staff available to both companies and proponents… the Division has determined to not respond to no-action requests…” How did these changes affect the ability of shareholders to use the proposal process to raise potentially material issues with their companies and fellow shareholders? How did the SEC’s absence as a neutral arbiter of exclusion claims affect how issuers and proponents behaved? How did it affect the efficiency and effectiveness of the shareholder proposal process as a means of placing important questions before shareholders on corporate proxy statements? This analysis examines how the shareholder proposal process functioned during the 2025–2026 proxy season to identify patterns in how companies and shareholders navigated the process in the absence of routine staff review, to assess issues of fairness, balance, and efficiency and to make recommendations based on the lessons from the season.
The data indicate a chilling effect on both proponents and issuers. Shareholders filed approximately 20% fewer proposals for the 2026 season. Companies filed over 100 fewer exclusion notices.
Many companies, it seems, made a prudent judgment: without SEC staff guidance on individual proposals, unilateral exclusion carried too much risk, including proponent litigation, reputational risk, potential fuel for a proxy fight over director elections, and other concerns. Rather than exploit the absence of oversight, many companies receiving proposals let the proposals go to the proxy, sometimes even explicitly citing the lack of SEC guidance as their reason for including proposals they believed might otherwise be excludable. Other companies similarly situated engaged with proponents to produce settlement agreements.
The rate at which proposals were excluded by companies in proportion to the number of proposals filed, in the absence of the SEC’s informal determinations, was similar to the rate excluded last year after SEC determinations. Yet, analysis of these exclusions revealed several important trends.
Comparison of 2025 and 2026 Process Outcomes
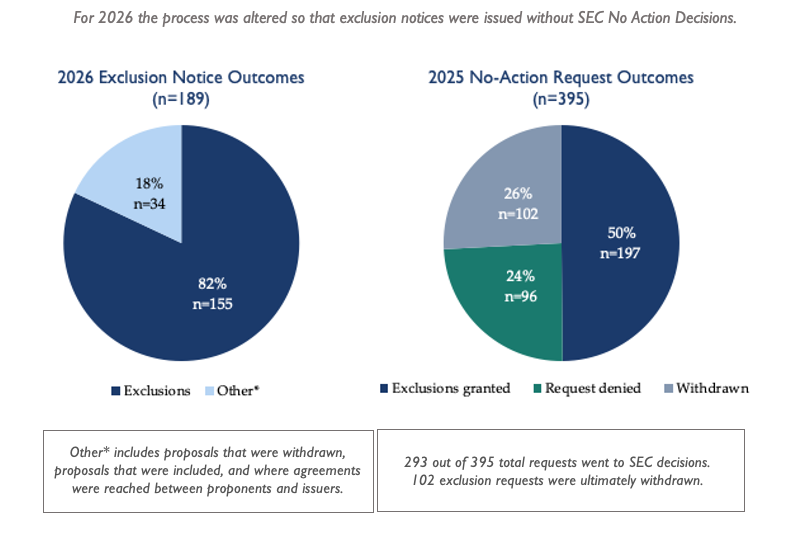
One of most common justifications for excluding proposals was the ordinary business rule—a determination that typically turns on subjective factors and has historically benefited from substantive SEC staff evaluation. Unfortunately, the largest portion of these exclusions clearly disadvantaged proponents who were either filing proposals on emerging risks on which staff had not previously opined or had refined a prior proposal’s language to address prior SEC staff concerns about prescriptive language. In both categories, the absence of SEC involvement undermined an orderly process and fair resolution of disputes over excludability, allowing exclusions to proceed despite the lack of staff guidance.
This exclusion trend is particularly troubling for proposals addressing an issue on which the staff has never opined. Even if the proposal concerned a significant emerging risk, exclusion could proceed despite the lack of staff guidance.
For example, at proposal at Amazon requesting company-specific disclosure of workforce risks tied to evolving U.S. immigration policy was excluded despite the absence of prior staff guidance on the topic. Proponents sought analysis of how recent and anticipated changes to immigration rules—particularly those affecting H-1B visa holders, warehouse labor, and truck drivers—could disrupt workforce, logistics capacity, and operating costs. Given the scale of Amazon’s workforce and reliance on these labor segments, this is an issue that a reasonable investor could view as financially material and decision-useful, yet the proposal was excluded without the benefit of any staff position addressing similar subject matter.
Similarly, on a year-to-year basis, the SEC sends signals to proponents and issuers regarding whether proposal language is too prescriptive, allowing proponents to revise proposals accordingly. This iterative feedback loop aligns proposal drafting with evolving staff interpretations. However, in the 2026 proxy season, such revisions were not ratified by staff review. As a result, issuers exercised unilateral discretion, and even proposals that may have been revised in good faith to conform with prior SEC guidance were nevertheless excluded.
For example, at AbbVie Inc., shareholders requested that the board oversee human rights due diligence to produce an impact assessment identifying actual and potential adverse human rights impacts in the company’s operations and supply chain, including effects on the right to health. Notably, this proposal appears to have been drafted to be less prescriptive than a prior 2025 proposal seeking a human rights impact assessment submitted to Eli Lilly, which the staff had permitted to be excluded on micromanagement grounds. The Eli Lilly proposal explicitly mandated the assessment cover “operations, activities, business relationships, and products”. By contrast, the AbbVie proposal narrowed and generalized the request—focusing on board oversight and an impact assessment framework rather than dictating exhaustive coverage parameters. Despite this apparent effort to align with prior staff reasoning and reduce prescriptiveness, AbbVie relied on the earlier Eli Lilly determination to justify exclusion. This illustrates how, in the absence of updated staff review, even materially revised proposals that address prior deficiencies can be excluded based on inapposite precedent.
Thus, an analysis of the ordinary business exclusions reveals that exclusions during this season disproportionately blocked (i) proposals addressing emerging issues lacking precedent and (ii) proposals that had undergone compliance-oriented revisions based on prior staff signals. The absence of no-action letters was therefore not neutral—it both impeded shareholders’ ability to surface new, financially relevant risks and disrupted the established corrective process that typically refines proposal language over time.
In another significant portion of exclusions, the companies claimed that their own activities substantially implemented the proposal. SEC staff is better positioned to provide a neutral evaluation of whether the company activities go as far as a proposal requests. These determinations are not appropriately left to the issuers.
Technical grounds—such as providing inadequate documentation that the proponent owned the necessary shares, or missing filing deadlines—accounted for another meaningful portion of exclusions. Some of these deficiencies seemed clear-cut. But without a structured opportunity for proponents to respond, questions remained about whether some of these technical exclusions rested on incomplete or disputed records that SEC staff would historically have scrutinized.
The disappearance of routine administrative review also caused at least six proponents to bring their disputes into federal court. Three of these cases resolved quickly after the companies agreed to include the proposals or provide the requested disclosure. These cases underscore how, in the absence of staff intermediation, formal legal action began to substitute for what had previously been an administrative and negotiated process. As proponent driven litigation became the primary enforcement mechanism for Rule 14a-8, a structural imbalance also took shape: the ability to defend a proposal increasingly depended on having the financial and legal resources to sue, in contradiction of the rule’s share ownership thresholds—which were designed to give even modest Main Street shareholders a voice.
This shift reflects a broader reconfiguration of how the rule operates in practice. Rule 14a-8 has historically depended on a combination of administrative oversight, evolving staff interpretation, and iterative dialogue between companies and investors. When the administrative layer was removed, interpretive authority shifted to issuers, and dispute resolution migrated to litigation and market pressure.
In that environment, the dynamics between proponents and companies changed materially. Proponents—who typically seek collaborative engagement with the company and dialogue with fellow shareholders—were forced into a position where they must consider escalation, including litigation, to ensure inclusion of proposals on the proxy.
The report concludes with five key recommendations for strengthening Rule 14a-8 and the shareholder proposal framework:
Preserve Rule 14a-8. The shareholder proposal mechanism is a vital communication channel between investors and corporate management. Weakening or eliminating it would undermine shareholders’ ability to raise governance concerns and hold management accountable.
Restore the no-action process. The SEC should revive its administrative process for resolving proposal exclusion disputes. Without it, conflicts are pushed into costly federal litigation or contentious shareholder campaigns. Some streamlining is possible for clear-cut procedural defects, but contested or fact-dependent claims still require meaningful staff review.
Eliminate “no-objection” letters. The practice of issuing no objection letters based solely on a company’s own unverified representations is inconsistent with Rule 14a-8’s intent. It implies administrative endorsement of unilateral exclusions regardless of consistency with the rule, and should be discontinued.
Issue clearer, more objective guidance. While appropriately restoring clarity about ensuring that proposals are relevant to the companies receiving them, Staff Legal Bulletin 14M also introduced excessive subjectivity into key exclusion determinations—particularly on “ordinary business” and “micromanagement” grounds. The subjective criteria provide staff with too much discretion; returning to more objective standards would improve predictability and reduce the need for repeated case-by-case adjudication.
Protect smaller shareholders’ access. Any reforms should ensure the process remains accessible to individual investors and smaller asset managers, who are unlikely to pursue litigation and who have historically filed some of the most important proposals on potentially material issues for their companies.
The 2025–2026 proxy season ultimately demonstrates both the resilience and the fragility of the shareholder proposal system. Shareholders kept raising concerns about governance, risk oversight, and corporate conduct. Some companies kept engaging constructively. But the absence of consistent regulatory oversight has introduced uncertainty, uneven outcomes, and shifted investor-company relations onto a more adversarial footing, dependent on litigation and escalatory tactics, rather than orderly SEC staff assessment of whether a proposal is consistent with the rule.

Investment Organizations Letter to Chairman Paul Atkins re Rule 14a-8 Jan 14, 2026
January 14, 2026
Dear Chairman Atkins and Mr. Moloney,
Thank you for taking the time to meet with us on December 17, 2025 to discuss ourconcerns regarding recent changes to the Division of Corporation Finance no-actionletter process for shareholder proposals and potential changes by the Commission toRule 14a-8.We appreciate the opportunity for an exchange of perspectives. However, we continue to have concerns.
Specifically, changes to the shareholder proposal process conflict with the Commission's tripartite mission of promoting capital formation, investor protection, and maintenance of fair and orderly capital markets. The ability of shareholders to vote by proxy on proposals made by their fellow shareholders has long been an integral part of the U.S. corporate governance system. We believe that this private ordering processhas helped facilitate capital formation.
In the intervening days since we met, we have seen a number of companies avail themselves of the opportunity to notify proponents of their intent to exclude proposals without the benefit of the Division of Corporation Finance staff’s substantive no-action letter review process. We believe the elimination of the no-action letter process for shareholder proposals will deprive investors of the opportunity to vote on numerous valid proposals. It will also work against the interests of many issuers who are now unable to obtain the Rule 14a-8 guidance that the Division staff have historically provided.
Moreover, the new approach seems inconsistent with Rule 14a-8(k). That provision contemplates that the shareholder proponent may respond in writing to a company’s stated intention to exclude a proposal, the Commission staff will then “consider fully” the proponent’s submission, and the staff will then issue a “response”, presumably that either agrees or disagrees with the company or the proponent.
In addition, we have continuing concerns about the approach outlined by Chairman Atkins to the Division Staff in his October 9th, 2025 speech at the John L. Weinberg Center for Corporate Governance. The right of shareholders under Delaware law to vote on precatory proposals is well-established, long-standing and highly beneficial for both shareholders and issuers. Indeed, a recent study (copy enclosed) concludes that shareholder activism “can positively influence firm value” and can “meaningfully shape long-term firm performance.” See “The Value of Being Heard” at page 40. Moreover, theproposed approach conflicts with the Commission’s longstanding position that “mostproposals that are cast as recommendations or requests that the board of directors takespecified action are proper under state law” as memorialized in Rule 14a-8’s note to paragraph (i)(1).
We urge the Division to engage in a robust effort to collect information from all concerned market participants regarding the shareholder proposal process to guide its consideration in this area. For example, in 2018 the SEC staff held a series of roundtables on the proxy process with investor, issuer and asset manager perspectives. As part of these roundtables, the staff invited interested members of the public to provide written comments that were considered as part of the Commission’s 2019proposed revisions to Rule 14a-8. We believe that a similar information gathering process would be beneficial if further changes to the shareholder proposal process are contemplated.
In the spirit of promoting dialogue and to better inform the Commission about the manybenefits that have resulted from the private ordering process of the shareholder proposal rule, we would like to share the following resources for your consideration:
Profs. Jill Fisch, Sarah Haan, Ann Lipton, and Amelia Miazad, Stockholder Proposals—Law and Policy Considerations, Harvard Law School Forum on Corporate Governance (December 9, 2025)
Letter to Chairman Atkins from various state fiscal officers (December 3, 2025)
Letter to Chairman Atkins from various investor organizations (November 5, 2025)
Letter to Chairman Atkins from the Council of Institutional Investors (December 30, 2025)
Letter to Chairman Atkins from the International Corporate Governance Network (October 12, 2025)
Shareholder Rights Group, Interfaith Center on Corporate Responsibility, and USSIF, Shareholder Proposals: An Essential Right (2025)
Letter to Chairman Atkins from the National Legal and Policy Center (December 18, 2025)
Christina Sautter, Texas Corporate Reforms Silence Retail Shareholders—By Design, Bloomberg (January 6, 2026)
Jasmijn Vandenberk, The Value of Being Heard: Board Responsiveness to Shareholder Proposals (September 11, 2025)
For additional resources on the shareholder proposal process, please see the InvestorRightsForum.com website.
Thank you for taking our concerns into consideration. As representatives of investors who have submitted or voted upon many successful shareholder proposals at the companies in which we invest, we welcome the opportunity to provide you with further information and perspectives as you evaluate the benefits of the shareholder proposal process.
Respectfully submitted,
Brandon Rees, Deputy Director of Corporations and Capital Markets, AFL-CIO
Steven M.Rothstein, Chief Program Officer, Ceres
Josh Zinner, CEO, Interfaith Center on Corporate Responsibility
Sanford Lewis, Director and General Counsel, Shareholder Rights Group
Maria Lettini, CEO, US SIF
Danielle Fugere, President and Chief Counsel, As You Sow
Legislative Developments in the Shareholder Proposal process
House
On September 18, 2024, the US House of Representatives passed H.R. 4790, the Prioritizing Economic Growth Over Woke Policies Act.110 The legislation is an umbrella bill incorporating a number of other bills that, among other things, significantly increase the ability of companies to exclude shareholder proposals from the proxy statement, including:
amending the Securities Exchange Act of 1934 to prohibit the SEC from compelling an issuer to include in the proxy statement any shareholder proposal or any discussion related to a shareholder proposal. The bill also expressly states the SEC may not preempt state regulation of proxy materials or shareholder proposals. (Section 2002)
increasing requirements for resubmission of proposals to require 10% voting support for a first-year proposal, 20% for a second year proposal and 40% for third year proposal, compared to current requirements of 5% voting support the first year, 15% for the second year and 25% for the third year. (Section 3101)
allowing companies to exclude shareholder proposals where the company already has policies, practices, or procedures that compare favorably with the guidelines of the proposal and address the proposal’s underlying concerns. (Section 3201)
allowing companies to exclude any proposal relating to environmental, social or political issues from proxy or consent solicitation material. (Section 3301)
allowing companies to exclude a shareholder proposal under Rule 14a-8(i) without regard to whether the proposal relates to a significant social policy issue. (Section 3401)
requiring the SEC to conduct a “wasteful and unnecessary” study every 5 years on shareholder proposals, proxy advisory firms, and the proxy process, covering a variety of topics, including the purported costs incurred by the shareholder proposal process and the “risk that shareholder proposals may contribute to the balkanization of the US economy over time.” (Section 3501)
providing that an institutional investor may not outsource voting decisions to any person other than an investment adviser or a broker or dealer that is registered with the Commission and has a fiduciary or best interest duty to the institutional investor. (Section 3901)
Senate
On September 23, 2024, S. 5139, the Empowering Main Street in America Act of 2024, was introduced. Among other things, the bill would allow a company to exclude a shareholder proposal from its proxy statement without regard to whether that shareholder proposal relates to a significant policy issue. (Section 305)
Shareholder Rights Group: At Boeing, Wells Fargo, Chevron - SEC Rulemaking Proposals Would Have Blocked Investor Engagement on Critical Issues
Immediate Release
January 7, 2019
The Shareholder Rights Group (SRG), a coalition of investors who exercise their right to file shareholder proposals, has written to the Securities and Exchange Commission (SEC) in opposition to proposed rule changes that would effectively undermine the ability of shareholders to continuously promote increased corporate responsibility and improved corporate governance. [Link to letter]
Currently, shareholders that own at least $2,000 in stock for one year have the right to engage an investee company on an issue of concern through procedures set forth in the SEC’s Rule 14a-8. In late 2019, the SEC proposed dramatic changes to the Rule, undermining shareholders’ rights to hold companies accountable for risk mitigation and crisis management. In addition to making it harder to file proposals by requiring larger or longer-term holdings, the rulemaking proposal would make it more difficult for shareholders to submit a proposal to a second or third vote by imposing steep voting thresholds – 25% support by the third year, and disallowing a proposal if it suffered a loss of momentum after that. The SRG letter notes that “[i]n practice sometimes 10% or 20% of investors represent the leading edge of an issue - the prescient minority, and therefore it is not wise for the management to discount the topic they are surfacing.”
The SRG’s letter highlights three case studies in which shareholders preemptively sought disclosure or oversight of certain issues that have proven to be significant concerns for those companies. Specifically, the SRG’s letter explains how the proposed rule changes, if they had been in effect at the time of shareholder engagement, would have interfered with investors’ ability to directly respond to recent corporate responsibility crises and controversial operations at Boeing, Wells Fargo, and Chevron.
Boeing: Prior to the two crashes of Boeing’s 737 Max airliners in 2018 and 2019, shareholders had encouraged better disclosure of Boeing’s notoriously aggressive lobbying policies, expenditures, and internal controls. Under the SEC’s proposed rulemaking on resubmissions, shareholder proposals on lobbying would have been barred beginning in 2017 – shortly before the 737 Max crashes. Yet, after the 737 Max crashes, shareholders supported lobbying disclosure with 32.6% of the vote in 2019. Had the proposed resubmission thresholds already been in place, shareholders would have been denied an opportunity to address this matter with the company in the wake of these catastrophic events.
Wells Fargo: Wells Fargo has suffered and continues to suffer a prolonged crisis of public, government, and consumer trust, having paid over $17.2 billion in penalties since 2000. The establishment of 3.5 million fictitious or unauthorized accounts, and improper practices in which 800,000 people were forced to take redundant auto insurance from 2012 to 2017, have punctuated an era of predatory practices. Had the SEC’s proposed resubmission thresholds been in place, shareholder proposals concerned about the ethical and business risks of predatory lending would have been excludable from 2013 to 2016. Additionally, under the SEC’s proposed threshold changes, shareholder proposals seeking an independent board chair would not have been permitted from 2013 to 2016 – a change that the company quickly enacted after its 2016 account fraud scandal. The failings of leadership, toxic corporate culture, and misdirected incentives have cost at least $24 billion in market value, despite early prescient shareholder engagement.
Chevron: In the U.S., advancement on corporate climate change mitigation initiatives has been driven to a large degree by shareholder proposals and shareholder engagement. One informative example is the progression of hydraulic fracturing and methane proposals at Chevron. Shareholder engagement from 2011-2015 had led to significant advancement of Chevron’s environmental practices and reporting; during this timeframe, shareholder support ebbed and flowed reaching highs of 40% (inspiring corporate action) and dipping to 26% before rebounding to over 30%. In 2018, approximately 45% of Chevron’s shareholders voted in favor of a shareholder proposal related to fugitive methane reduction, which again inspired a corporate response on the issue. However, had the SEC’s newly-proposed “momentum requirement” been in place, this natural variation of shareholder support would have meant that investors would not have been offered the opportunity to vote on that 2018 proposal that they resoundingly supported.
Sanford Lewis, Director of the Shareholder Rights Group explains in the letter that “[i]n our assessment, the SEC’s proposed proxy rule changes would disrupt functional working relationships between shareholder proponents, institutional investors, and proxy advisors and companies. The proposed rule changes would make the path of investor engagement steeper and more convoluted, adding unnecessary costs and red tape, and making it more difficult for investors to foster sustainability, risk management, and governance improvements at their companies. It would block the most established and effective path for improving environmental, social, and governance (ESG) disclosure and performance of the market.”
The Shareholder Rights Group urges all concerned investors to write to the SEC in opposition to the proposed rules by the February 3 comment deadline. Additional info on the proposed rule changes, including links to the proposed rules are included at InvestorRightsForum.com
The SEC is accepting comments on the proposed rules until February 3, 2020. Write to: Vanessa A. Countryman, Secretary, U.S. Securities and Exchange Commission, 100 F Street NE, Washington, DC 20549-1090; Email to: rule-comments@sec.gov. Email or hard copy subject line should include reference to the File No. S7-23-19 (shareholder proposals) and File No. S7-22-19 (proxy advisors).
Investor Voice: SEC’s Proposed Rule Changes Muzzle Shareholders and Shield CEOs From Accountability
“The shareholder proposal rule is the bedrock of effective corporate engagement in the United States,” said Bruce Herbert, chief executive of Investor Voice. “For over 70 years, the shareholder engagement process has been a vital tool for stockowners to propose good ideas involving sustainability, profitability, and governance; to hold CEOs accountable for mismanagement; and to mitigate risk by addressing issues like climate change and human rights.”
SEATTLE – The U.S. Securities and Exchange Commission voted today to consider sweeping changes to the regulations governing the shareholder proposal process which negatively impact small investors as well as proxy advisory services. The proposed changes to Rule 14a-8 include substantially more strict and complicated thresholds for filing, significantly higher resubmission requirements, serious free speech infringements on independent third-party proxy advisory services, and onerous restrictions on an investor’s essential agency right to seek assistance.
“The shareholder proposal rule is the bedrock of effective corporate engagement in the United States,” said Bruce Herbert, chief executive of Investor Voice. “For over 70 years, the shareholder engagement process has been a vital tool for stockowners to propose good ideas involving sustainability, profitability, and governance; to hold CEOs accountable for mismanagement; and to mitigate risk by addressing issues like climate change and human rights.”
“These proposed changes were not asked for by investors,” Herbert continued, “they are the result of a concerted influence campaign backed by large industry associations. Key players were the Business Roundtable, National Association of Manufacturers, and the U.S. Chamber of Commerce – each of whom believes that responding to small investors creates an undue burden on the corporation.”
The proposed changes, Herbert said, are a solution in search of a problem. Trump appointees to the SEC, including Chair Jay Clayton and Commissioner Elad Roisman, argue that change is needed to ‘modernize’ the shareholder engagement process, asserting that the rules have not been “revised” in decades.
“However,” Herbert observed, “that argument is highly misleading because ‘revision’ is very different from ‘review’ – the fact is that the shareholder engagement rule has been reviewed many times over the decades and always found to be fresh and beneficial as it stood. Focusing on ‘revisions’ while ignoring ‘reviews’, as Clayton and Roisman purposefully do, is like asserting that someone who goes in for annual check-ups has received no medical attention whatsoever unless and until they undergo surgery.”
The two Democrats on the commission, Allison Lee and Robert Jackson, blasted the proposed changes as a power-grab by corporate CEOs. “The bottom line is that today’s proposals would shift power away from shareholders and towards management,” said Commissioner Lee.
Commissioner Jackson, meanwhile, argued that, while some minor reforms may be needed, today’s proposals “amount to swatting a gadfly with a sledgehammer.”
The Commission passed the motion to consider the proposed changes on a party-line vote of 3-2. The public will have only 60 days to submit comments to the SEC once the proposals are published in the Federal Register.
Contact: Bruce Herbert
206-522-3055 team@investorvoice.net
NY State Comptroller DiNapoli Statement on Proposed SEC Rule Changes
"The SEC's proposals are two of the most significant actions to restrict shareholder rights in the SEC’s history. There is no credible evidence to support the need for these proposals, and if adopted, they would undermine corporate accountability, entrench managements’ opposition to shareholder proposals and increase costs for investors. These proposals are contrary to the SEC's mission to protect investors and our financial markets. Along with other investors, I will continue to voice my opposition to these actions and my support for greater corporate accountability."
"The SEC's proposals are two of the most significant actions to restrict shareholder rights in the SEC’s history. There is no credible evidence to support the need for these proposals, and if adopted, they would undermine corporate accountability, entrench managements’ opposition to shareholder proposals and increase costs for investors. These proposals are contrary to the SEC's mission to protect investors and our financial markets. Along with other investors, I will continue to voice my opposition to these actions and my support for greater corporate accountability."
New York City Comptroller Scott M. Stringer on Proposed SEC Rule Changes
"The proposed U.S. Securities and Exchange Commission changes will compromise the independence of our contracted proxy advisers, impose limits on shareowner proposals and therefore further insulate corporate management from accountability to shareowners. If implemented, these actions would be a shameful gift to corporate executives at the expense of shareowners.”
"As Comptroller for the City of New York, I am the chief investment advisor and custodian of assets of the five New York City Retirement Systems (NYCRS) and a trustee of four of them. These Funds represent the retirement security of the City’s teachers, school employees, police and firefighters, and other employees. Many of our more than 700,000 members likely only participate in the capital markets through their role as pension fund beneficiaries and are the true main street investors whose interests the SEC should protect.
"The NYCRS are long-term shareowners of more than 3,000 U.S. public companies and are the fourth largest public pension system in the United States, with more than $200 billion in assets under management. Our funds have filed more than 1,000 shareowner proposals, almost certainly more than any other institutional investor in the world, with a record dating back 30 years.
"The proposed U.S. Securities and Exchange Commission changes will compromise the independence of our contracted proxy advisers, impose limits on shareowner proposals and therefore further insulate corporate management from accountability to shareowners. If implemented, these actions would be a shameful gift to corporate executives at the expense of shareowners.
"The proposed rules seek to remedy problems that do not exist but are merely false narratives put forward by corporate executives who want to limit the ability of investors to push for change and to hold them accountable for runaway CEO pay, excessive risk-taking and irresponsible and harmful business practices.
"These are mechanisms through which we and other shareowners have pushed for anti-discrimination policies, greater diversity in the C-suite, better climate policies and improved transparency and accountability in our interests as long-term investors. We should be demanding more of this, not less."
Council of Institutional Investors: Fact Sheet on Proxy Advisory Firms and Shareholder Proposals Nov. 5, 2019
Most public companies do not receive any shareholder proposals. On average, 13% of Russell 3000 companies received a shareholder proposal in a particular year between 2004 and 2017. In other words, the average Russell 3000 company can expect to receive a proposal once every 7.7 years. For companies that receive a proposal, the median number of proposals is one per year.
1. The Business Roundtable, National Association of Manufacturers and other
management groups’ claim that proxy advice is rife with errors is based on anecdote not evidence.
· The SEC comment file for the SEC’s Nov. 15, 2018, proxy roundtable includes a number of letters that assert that errors in proxy reports are endemic. But the letters offer very few examples and most of those do not identify the company and cannot be checked. CII believes most claims of errors actually are methodological differences.
· The only study that CII is aware of that purports to tote up proxy advisor errors alleges just 39 factual errors over nearly three years (or 0.1% of more than 30,000 reports by leading proxy advisory firms Institutional Shareholder Services (ISS) and Glass Lewis during that period). And the study inflates the claimed error rate. CII’s own analysis of the study found that no more than 17 of the claims of factual error had merit.
· CEO and board member dislike of proxy advisors appears driven by discomfort with the role of proxy research to be critical and raise questions. The charge of systemic factual error appears to be fabricated as a means to quash critical analysis and commentary.
2. Claims that proxy advisory firms wield excessive influence over how institutional investors vote confuse correlation with causation.
· Many pension funds and other institutional investors buy proxy and review advisors’ research and recommendations but vote according to their own guidelines and policies. According to ISS, 85% of its top 100 clients use a custom voting policy.
· It is wrong and insulting to suggest that institutional investors “robo vote”—vote in lockstep with proxy advisor recommendations. While ISS recommended voting against say-on-pay proposals at 12.3% of Russell 3000 companies in 2018, just 2.4% of those companies received less than majority shareholder support on their say-on-pay proposals. In 2019, Glass Lewis recommended in favor of 89% of directors and 84% of say-on-pay proposals, while directors received average support of 96% and say-on-pay proposals garnered average support of 93%.
· Academic research has found that while both ISS and Glass Lewis appear to have some impact on shareholder voting, media reports often substantially overstate the extent of that influence.
3. The proposed mandate that proxy advisory firms let companies review the firms’ reports before investor clients see them amounts to unprecedented interference in the free market and is the opposite of what is required by regulation of stock analyst reports.
· Current rules prohibit analysts from sharing draft research reports with target companies, other than to check facts after approval from the firm’s legal or compliance department.
· FINRA Rule 2241, which the SEC approved, establishes this safeguard to, as the SEC has explained, “help protect research analysts from influences that could impair their objectivity and independence.”
· If the SEC adopts its proxy advisor regulation, an analyst and a proxy advisor could write a report on the same company and the analyst would violate securities laws by showing it to the company in advance, while the proxy adviser would violate the law if it did not show it to the company in advance.
· This is the very definition of arbitrary and capricious government action.
4. Three SEC commissioners are attempting to jam through fundamental changes without appropriate analysis and public comment.
· The predicate for the SEC’s new, heavy-handed regulatory structure for proxy advisory firms is a significant change made by the SEC on Aug. 15, 2019, on a 3-2 vote, without any public comment, zero cost-benefit analysis and limited and flawed legal justification.
5. Shareholder proposals have proven to be a key channel for effective shareholder engagement with public companies for more than half a century.
· Shareholder proposals permit investors to express their voice collectively on issues of concern to them, without the cost and disruption of waging proxy fights.
· Shareholder proposals have encouraged many companies to adopt governance policies that today are viewed widely as best practice.
o Electing directors by majority vote, rather than by plurality, a radical idea a decade ago when shareholders pressed for it in proposals, is now the norm at 90% of large-cap U.S. companies.
o Similarly, norms such as independent directors constituting a majority of the board, independent board leadership, board diversity, sustainability reporting, non-discrimination policies and annual elections for all directors all were advocated early through shareholder proposals.
· Shareholder proposals are a critical tool for expression of the collective views of holders, permitting them to communicate with each other as well as the company on whether an issue or approach has support. Another tool is voting against directors, but the message from negative voting on directors when the concern is a specific policy or disclosure is much less focused or clear.
6. Shareholder proposals are not a significant burden to U.S. public companies.
· Shareholder proposals are almost always non-binding. The board actually does not have to do anything in response to a proposal.
· Most public companies do not receive any shareholder proposals. On average, 13% of Russell 3000 companies received a shareholder proposal in a particular year between 2004 and 2017. In other words, the average Russell 3000 company can expect to receive a proposal once every 7.7 years. For companies that receive a proposal, the median number of proposals is one per year.
· Companies exaggerate the cost of shareholder proposals. Most of the cost involves attempts by management to exclude proposals from their proxy statements, which is a choice made by management. The cost to put a proposal on the proxy ballot is de minimis.
· CEO advocacy organizations say that shareholder proposals keep private companies from doing an IPO, an unsupportable and fact-free assertion. It is ludicrous to argue that a board would forgo access to public capital markets because in the next eight years the company may face a nonbinding shareholder proposal requesting better disclosure on its carbon footprint or the annual election of all directors.
7. Additional curbs on shareholder proposals are not needed.
· Raising resubmission thresholds will stifle new ideas and issues, which typically take time to gain traction with investors.
· The raised resubmission thresholds will keep topics off corporate ballots for years, even though circumstances may change at a company (e.g., independent board leadership tends to be seen as much more urgent when a company is in crisis, and the proposed new thresholds are likely to bar a proposal to separate the roles of CEO and chair at companies with the worst governance records).
· The increased ownership thresholds will especially hamper small investors, the very market participants that SEC Chairman Jay Clayton has made it a priority to protect.
· Until 1983, ownership of a single share of stock carried the right to propose a shareholder resolution. Now we are on a slippery slope that strips that right from more and more small shareholders, whose ideas can be as important and valuable to consider as those of larger holders.
AS YOU SOW: As Shareholder Support for Climate Change and other Environmental, Social, and Governance Issues Grows, SEC Votes to Restrict Shareholder Voice
“The SEC has been unable to point to any demonstrable problem with the current shareholder system or make a case for how its proposal to limit shareholder rights will improve company value,” said Danielle Fugere, president of As You Sow. “To the contrary, this proposed rulemaking has the potential to increase shareholder and company risk, particularly regarding growing climate concerns. We don’t believe that it will withstand public or legal scrutiny.”
BERKELEY, CA—NOV. 5, 2019—The U.S. Securities and Exchange Commission (SEC), led by Chairman Clayton, voted today to severely limit the rights of shareholders, especially small shareholders to file proposals at companies. The SEC 14a8 process was created to ensure that shareholders have the right to seek transparency and disclosure from companies or raise significant policy issues that can create risk or harm company value over time. Such proposals, which are advisory and not mandatory even with 100% of the vote, have the goal of raising critical issues in front of management, boards, and company shareholders. Today’s draconian vote, split along party lines, would limit investor rights in ways that are incompatible with the basic premise that shareholders are owners of companies and should have a voice in the companies they own.
“With this vote, the SEC has apparently inverted its mandate of protecting shareholders to that of protecting companies from shareholder input — even where company action creates increasing risk to shareholders, people, or the environment,” said Andrew Behar, CEO of As You Sow. “This proposal flies in the face of the SEC’s mandate of ensuring transparency, open discussion, and company responsiveness to shareholder concerns.”
Shareholder proposals have served an important role in bringing cutting edge issues to the attention of management and boards, informing shareholders of growing risk, and increasing productive discussion of significant policy issues — in short, increasing transparency and shedding light on company actions. “Shareholders and companies have been well served by this process over the years; allowing company actions to fall back into the shadows is a giant step backward for all,” said Behar.
Climate proposals are an important example of how shareholders have successfully used the process to flag the growing risk to companies and investors of inaction on climate change. Shareholder proposals have shined a light on the importance of climate change; highlighted the risks of inaction; underscored opportunities for responsive companies; flagged lead actors and lagging companies; and ensured that the market is appropriately addressing growing systemic climate risk.
“The SEC has been unable to point to any demonstrable problem with the current shareholder system or make a case for how its proposal to limit shareholder rights will improve company value,” said Danielle Fugere, president of As You Sow. “To the contrary, this proposed rulemaking has the potential to increase shareholder and company risk, particularly regarding growing climate concerns. We don’t believe that it will withstand public or legal scrutiny.”