S&P Global Market Intelligence: SEC proposed rule would have blocked 614 ESG resolutions since 2010, data shows
Author: Esther Whieldon
Since 2010 more than 600 environmental, social and governance-related resolutions likely would have never advanced under a newly proposed rule by the U.S. Securities and Exchange Commission, according to data the Sustainable Investments Institute shared with S&P Global Market Intelligence.
The SEC in November 2019 proposed to increase the amount of support a shareholder resolution required to be reconsidered in the years following an initial vote. Rather than resolutions needing at least 3% support the first year, 6% the second year, and 10% the third and subsequent years after an initial vote to be reconsidered, the SEC would raise those thresholds to 5%, 15% and 25%, respectively. The agency estimated the changes would cut the number of shareholder proposals by 7%.
While the rule has yet to be finalized, the Sustainable Investments Institute, or Si2, compiled a database of ESG resolutions voted on from the beginning of 2010 through Nov. 18, 2019. Si2 found that 614 ESG-related resolutions, or about 30%, of the 2,019 proposals voted on at company annual meetings over that period would not have been eligible for resubmission. That total is almost three times the number of resolutions — 206 resolutions — that could have failed existing threshold requirements over that time, according to Market Intelligence's analysis of the data.
Of the 614 potentially impacted resolutions, political activity, climate change and human rights issues would have taken the biggest hit.
Companies are coming under increased pressure from investors to disclose how ESG risks could impact their bottom line, and they are addressing those risks and opportunities. But groups such as the U.S. Chamber of Commerce and Business Roundtable have pushed for reforms to the shareholder resolution process.
Shareholder Rights Group: At Boeing, Wells Fargo, Chevron - SEC Rulemaking Proposals Would Have Blocked Investor Engagement on Critical Issues
Immediate Release
January 7, 2019
The Shareholder Rights Group (SRG), a coalition of investors who exercise their right to file shareholder proposals, has written to the Securities and Exchange Commission (SEC) in opposition to proposed rule changes that would effectively undermine the ability of shareholders to continuously promote increased corporate responsibility and improved corporate governance. [Link to letter]
Currently, shareholders that own at least $2,000 in stock for one year have the right to engage an investee company on an issue of concern through procedures set forth in the SEC’s Rule 14a-8. In late 2019, the SEC proposed dramatic changes to the Rule, undermining shareholders’ rights to hold companies accountable for risk mitigation and crisis management. In addition to making it harder to file proposals by requiring larger or longer-term holdings, the rulemaking proposal would make it more difficult for shareholders to submit a proposal to a second or third vote by imposing steep voting thresholds – 25% support by the third year, and disallowing a proposal if it suffered a loss of momentum after that. The SRG letter notes that “[i]n practice sometimes 10% or 20% of investors represent the leading edge of an issue - the prescient minority, and therefore it is not wise for the management to discount the topic they are surfacing.”
The SRG’s letter highlights three case studies in which shareholders preemptively sought disclosure or oversight of certain issues that have proven to be significant concerns for those companies. Specifically, the SRG’s letter explains how the proposed rule changes, if they had been in effect at the time of shareholder engagement, would have interfered with investors’ ability to directly respond to recent corporate responsibility crises and controversial operations at Boeing, Wells Fargo, and Chevron.
Boeing: Prior to the two crashes of Boeing’s 737 Max airliners in 2018 and 2019, shareholders had encouraged better disclosure of Boeing’s notoriously aggressive lobbying policies, expenditures, and internal controls. Under the SEC’s proposed rulemaking on resubmissions, shareholder proposals on lobbying would have been barred beginning in 2017 – shortly before the 737 Max crashes. Yet, after the 737 Max crashes, shareholders supported lobbying disclosure with 32.6% of the vote in 2019. Had the proposed resubmission thresholds already been in place, shareholders would have been denied an opportunity to address this matter with the company in the wake of these catastrophic events.
Wells Fargo: Wells Fargo has suffered and continues to suffer a prolonged crisis of public, government, and consumer trust, having paid over $17.2 billion in penalties since 2000. The establishment of 3.5 million fictitious or unauthorized accounts, and improper practices in which 800,000 people were forced to take redundant auto insurance from 2012 to 2017, have punctuated an era of predatory practices. Had the SEC’s proposed resubmission thresholds been in place, shareholder proposals concerned about the ethical and business risks of predatory lending would have been excludable from 2013 to 2016. Additionally, under the SEC’s proposed threshold changes, shareholder proposals seeking an independent board chair would not have been permitted from 2013 to 2016 – a change that the company quickly enacted after its 2016 account fraud scandal. The failings of leadership, toxic corporate culture, and misdirected incentives have cost at least $24 billion in market value, despite early prescient shareholder engagement.
Chevron: In the U.S., advancement on corporate climate change mitigation initiatives has been driven to a large degree by shareholder proposals and shareholder engagement. One informative example is the progression of hydraulic fracturing and methane proposals at Chevron. Shareholder engagement from 2011-2015 had led to significant advancement of Chevron’s environmental practices and reporting; during this timeframe, shareholder support ebbed and flowed reaching highs of 40% (inspiring corporate action) and dipping to 26% before rebounding to over 30%. In 2018, approximately 45% of Chevron’s shareholders voted in favor of a shareholder proposal related to fugitive methane reduction, which again inspired a corporate response on the issue. However, had the SEC’s newly-proposed “momentum requirement” been in place, this natural variation of shareholder support would have meant that investors would not have been offered the opportunity to vote on that 2018 proposal that they resoundingly supported.
Sanford Lewis, Director of the Shareholder Rights Group explains in the letter that “[i]n our assessment, the SEC’s proposed proxy rule changes would disrupt functional working relationships between shareholder proponents, institutional investors, and proxy advisors and companies. The proposed rule changes would make the path of investor engagement steeper and more convoluted, adding unnecessary costs and red tape, and making it more difficult for investors to foster sustainability, risk management, and governance improvements at their companies. It would block the most established and effective path for improving environmental, social, and governance (ESG) disclosure and performance of the market.”
The Shareholder Rights Group urges all concerned investors to write to the SEC in opposition to the proposed rules by the February 3 comment deadline. Additional info on the proposed rule changes, including links to the proposed rules are included at InvestorRightsForum.com
The SEC is accepting comments on the proposed rules until February 3, 2020. Write to: Vanessa A. Countryman, Secretary, U.S. Securities and Exchange Commission, 100 F Street NE, Washington, DC 20549-1090; Email to: rule-comments@sec.gov. Email or hard copy subject line should include reference to the File No. S7-23-19 (shareholder proposals) and File No. S7-22-19 (proxy advisors).
Business Roundtable Must Defend Shareholder Access to Proxy
We write today for two reasons. The first is to commend the Business Roundtable (BRT) and the 181 CEOs who endorsed the new Statement on the Purpose of the Corporation(the “Statement”), embracing the importance of companies’ commitment to key stakeholders. The statement acknowledges a central tenet of ICCR’s core philosophy: that companies focused on the well-being of all their key stakeholders and not just on boosting short-term shareholder returns will be more successful over the long term. A growing community of ESG investors have been supportive of companies demonstrating leadership in corporate responsibility for years, with the firm belief that these companies are building long-term value for shareholders.We expect the BRT CEO statement will stimulate an important dialogue within companies,investors and the broader public.
However,the principles clearly articulated in the Statement makes the BRT’s continuing lobbying and public statements against shareholder resolutions dealing with environmental, social and governance issues even more perplexing. We urge the BRT to reassess its campaign against shareholder resolutions in light of the new statement.
We read with interest the June 3,2019 BRT letter to the Securities & Exchange Commission (SEC Letter)and take issue with several of the assumptions used to support the BRT’s argument. The BRT’s characterization of the issues raised in the proxy process, as well as the motivations of shareholder proponents, is a simplistic description that is false and misleading.
In a letter to the Business Roundtable, ICCR’s CEO Josh Zinner highlights the inconsistencies in the BRT’s statement and its ongoing attack on the shareholder proposal process, and urges the BRT to align its positions on the proxy process in furtherance of a corporate purpose that serves all stakeholders, and leads to long-term value.
We write today for two reasons. The first is to commend the Business Roundtable (BRT) and the 181 CEOs who endorsed the new Statement on the Purpose of the Corporation(the “Statement”), embracing the importance of companies’ commitment to key stakeholders. The statement acknowledges a central tenet of ICCR’s core philosophy: that companies focused on the well-being of all their key stakeholders and not just on boosting short-term shareholder returns will be more successful over the long term. A growing community of ESG investors have been supportive of companies demonstrating leadership in corporate responsibility for years, with the firm belief that these companies are building long-term value for shareholders.We expect the BRT CEO statement will stimulate an important dialogue within companies,investors and the broader public.
However,the principles clearly articulated in the Statement makes the BRT’s continuing lobbying and public statements against shareholder resolutions dealing with environmental, social and governance issues even more perplexing. We urge the BRT to reassess its campaign against shareholder resolutions in light of the new statement.
We read with interest the June 3,2019 BRT letter to the Securities & Exchange Commission (SEC Letter) and take issue with several of the assumptions used to support the BRT’s argument. The BRT’s characterization of the issues raised in the proxy process, as well as the motivations of shareholder proponents, is a simplistic description that is false and misleading.
Investor Voice: SEC’s Proposed Rule Changes Muzzle Shareholders and Shield CEOs From Accountability
“The shareholder proposal rule is the bedrock of effective corporate engagement in the United States,” said Bruce Herbert, chief executive of Investor Voice. “For over 70 years, the shareholder engagement process has been a vital tool for stockowners to propose good ideas involving sustainability, profitability, and governance; to hold CEOs accountable for mismanagement; and to mitigate risk by addressing issues like climate change and human rights.”
SEATTLE – The U.S. Securities and Exchange Commission voted today to consider sweeping changes to the regulations governing the shareholder proposal process which negatively impact small investors as well as proxy advisory services. The proposed changes to Rule 14a-8 include substantially more strict and complicated thresholds for filing, significantly higher resubmission requirements, serious free speech infringements on independent third-party proxy advisory services, and onerous restrictions on an investor’s essential agency right to seek assistance.
“The shareholder proposal rule is the bedrock of effective corporate engagement in the United States,” said Bruce Herbert, chief executive of Investor Voice. “For over 70 years, the shareholder engagement process has been a vital tool for stockowners to propose good ideas involving sustainability, profitability, and governance; to hold CEOs accountable for mismanagement; and to mitigate risk by addressing issues like climate change and human rights.”
“These proposed changes were not asked for by investors,” Herbert continued, “they are the result of a concerted influence campaign backed by large industry associations. Key players were the Business Roundtable, National Association of Manufacturers, and the U.S. Chamber of Commerce – each of whom believes that responding to small investors creates an undue burden on the corporation.”
The proposed changes, Herbert said, are a solution in search of a problem. Trump appointees to the SEC, including Chair Jay Clayton and Commissioner Elad Roisman, argue that change is needed to ‘modernize’ the shareholder engagement process, asserting that the rules have not been “revised” in decades.
“However,” Herbert observed, “that argument is highly misleading because ‘revision’ is very different from ‘review’ – the fact is that the shareholder engagement rule has been reviewed many times over the decades and always found to be fresh and beneficial as it stood. Focusing on ‘revisions’ while ignoring ‘reviews’, as Clayton and Roisman purposefully do, is like asserting that someone who goes in for annual check-ups has received no medical attention whatsoever unless and until they undergo surgery.”
The two Democrats on the commission, Allison Lee and Robert Jackson, blasted the proposed changes as a power-grab by corporate CEOs. “The bottom line is that today’s proposals would shift power away from shareholders and towards management,” said Commissioner Lee.
Commissioner Jackson, meanwhile, argued that, while some minor reforms may be needed, today’s proposals “amount to swatting a gadfly with a sledgehammer.”
The Commission passed the motion to consider the proposed changes on a party-line vote of 3-2. The public will have only 60 days to submit comments to the SEC once the proposals are published in the Federal Register.
Contact: Bruce Herbert
206-522-3055 team@investorvoice.net
NY State Comptroller DiNapoli Statement on Proposed SEC Rule Changes
"The SEC's proposals are two of the most significant actions to restrict shareholder rights in the SEC’s history. There is no credible evidence to support the need for these proposals, and if adopted, they would undermine corporate accountability, entrench managements’ opposition to shareholder proposals and increase costs for investors. These proposals are contrary to the SEC's mission to protect investors and our financial markets. Along with other investors, I will continue to voice my opposition to these actions and my support for greater corporate accountability."
"The SEC's proposals are two of the most significant actions to restrict shareholder rights in the SEC’s history. There is no credible evidence to support the need for these proposals, and if adopted, they would undermine corporate accountability, entrench managements’ opposition to shareholder proposals and increase costs for investors. These proposals are contrary to the SEC's mission to protect investors and our financial markets. Along with other investors, I will continue to voice my opposition to these actions and my support for greater corporate accountability."
New York City Comptroller Scott M. Stringer on Proposed SEC Rule Changes
"The proposed U.S. Securities and Exchange Commission changes will compromise the independence of our contracted proxy advisers, impose limits on shareowner proposals and therefore further insulate corporate management from accountability to shareowners. If implemented, these actions would be a shameful gift to corporate executives at the expense of shareowners.”
"As Comptroller for the City of New York, I am the chief investment advisor and custodian of assets of the five New York City Retirement Systems (NYCRS) and a trustee of four of them. These Funds represent the retirement security of the City’s teachers, school employees, police and firefighters, and other employees. Many of our more than 700,000 members likely only participate in the capital markets through their role as pension fund beneficiaries and are the true main street investors whose interests the SEC should protect.
"The NYCRS are long-term shareowners of more than 3,000 U.S. public companies and are the fourth largest public pension system in the United States, with more than $200 billion in assets under management. Our funds have filed more than 1,000 shareowner proposals, almost certainly more than any other institutional investor in the world, with a record dating back 30 years.
"The proposed U.S. Securities and Exchange Commission changes will compromise the independence of our contracted proxy advisers, impose limits on shareowner proposals and therefore further insulate corporate management from accountability to shareowners. If implemented, these actions would be a shameful gift to corporate executives at the expense of shareowners.
"The proposed rules seek to remedy problems that do not exist but are merely false narratives put forward by corporate executives who want to limit the ability of investors to push for change and to hold them accountable for runaway CEO pay, excessive risk-taking and irresponsible and harmful business practices.
"These are mechanisms through which we and other shareowners have pushed for anti-discrimination policies, greater diversity in the C-suite, better climate policies and improved transparency and accountability in our interests as long-term investors. We should be demanding more of this, not less."
Council of Institutional Investors: Fact Sheet on Proxy Advisory Firms and Shareholder Proposals Nov. 5, 2019
Most public companies do not receive any shareholder proposals. On average, 13% of Russell 3000 companies received a shareholder proposal in a particular year between 2004 and 2017. In other words, the average Russell 3000 company can expect to receive a proposal once every 7.7 years. For companies that receive a proposal, the median number of proposals is one per year.
1. The Business Roundtable, National Association of Manufacturers and other
management groups’ claim that proxy advice is rife with errors is based on anecdote not evidence.
· The SEC comment file for the SEC’s Nov. 15, 2018, proxy roundtable includes a number of letters that assert that errors in proxy reports are endemic. But the letters offer very few examples and most of those do not identify the company and cannot be checked. CII believes most claims of errors actually are methodological differences.
· The only study that CII is aware of that purports to tote up proxy advisor errors alleges just 39 factual errors over nearly three years (or 0.1% of more than 30,000 reports by leading proxy advisory firms Institutional Shareholder Services (ISS) and Glass Lewis during that period). And the study inflates the claimed error rate. CII’s own analysis of the study found that no more than 17 of the claims of factual error had merit.
· CEO and board member dislike of proxy advisors appears driven by discomfort with the role of proxy research to be critical and raise questions. The charge of systemic factual error appears to be fabricated as a means to quash critical analysis and commentary.
2. Claims that proxy advisory firms wield excessive influence over how institutional investors vote confuse correlation with causation.
· Many pension funds and other institutional investors buy proxy and review advisors’ research and recommendations but vote according to their own guidelines and policies. According to ISS, 85% of its top 100 clients use a custom voting policy.
· It is wrong and insulting to suggest that institutional investors “robo vote”—vote in lockstep with proxy advisor recommendations. While ISS recommended voting against say-on-pay proposals at 12.3% of Russell 3000 companies in 2018, just 2.4% of those companies received less than majority shareholder support on their say-on-pay proposals. In 2019, Glass Lewis recommended in favor of 89% of directors and 84% of say-on-pay proposals, while directors received average support of 96% and say-on-pay proposals garnered average support of 93%.
· Academic research has found that while both ISS and Glass Lewis appear to have some impact on shareholder voting, media reports often substantially overstate the extent of that influence.
3. The proposed mandate that proxy advisory firms let companies review the firms’ reports before investor clients see them amounts to unprecedented interference in the free market and is the opposite of what is required by regulation of stock analyst reports.
· Current rules prohibit analysts from sharing draft research reports with target companies, other than to check facts after approval from the firm’s legal or compliance department.
· FINRA Rule 2241, which the SEC approved, establishes this safeguard to, as the SEC has explained, “help protect research analysts from influences that could impair their objectivity and independence.”
· If the SEC adopts its proxy advisor regulation, an analyst and a proxy advisor could write a report on the same company and the analyst would violate securities laws by showing it to the company in advance, while the proxy adviser would violate the law if it did not show it to the company in advance.
· This is the very definition of arbitrary and capricious government action.
4. Three SEC commissioners are attempting to jam through fundamental changes without appropriate analysis and public comment.
· The predicate for the SEC’s new, heavy-handed regulatory structure for proxy advisory firms is a significant change made by the SEC on Aug. 15, 2019, on a 3-2 vote, without any public comment, zero cost-benefit analysis and limited and flawed legal justification.
5. Shareholder proposals have proven to be a key channel for effective shareholder engagement with public companies for more than half a century.
· Shareholder proposals permit investors to express their voice collectively on issues of concern to them, without the cost and disruption of waging proxy fights.
· Shareholder proposals have encouraged many companies to adopt governance policies that today are viewed widely as best practice.
o Electing directors by majority vote, rather than by plurality, a radical idea a decade ago when shareholders pressed for it in proposals, is now the norm at 90% of large-cap U.S. companies.
o Similarly, norms such as independent directors constituting a majority of the board, independent board leadership, board diversity, sustainability reporting, non-discrimination policies and annual elections for all directors all were advocated early through shareholder proposals.
· Shareholder proposals are a critical tool for expression of the collective views of holders, permitting them to communicate with each other as well as the company on whether an issue or approach has support. Another tool is voting against directors, but the message from negative voting on directors when the concern is a specific policy or disclosure is much less focused or clear.
6. Shareholder proposals are not a significant burden to U.S. public companies.
· Shareholder proposals are almost always non-binding. The board actually does not have to do anything in response to a proposal.
· Most public companies do not receive any shareholder proposals. On average, 13% of Russell 3000 companies received a shareholder proposal in a particular year between 2004 and 2017. In other words, the average Russell 3000 company can expect to receive a proposal once every 7.7 years. For companies that receive a proposal, the median number of proposals is one per year.
· Companies exaggerate the cost of shareholder proposals. Most of the cost involves attempts by management to exclude proposals from their proxy statements, which is a choice made by management. The cost to put a proposal on the proxy ballot is de minimis.
· CEO advocacy organizations say that shareholder proposals keep private companies from doing an IPO, an unsupportable and fact-free assertion. It is ludicrous to argue that a board would forgo access to public capital markets because in the next eight years the company may face a nonbinding shareholder proposal requesting better disclosure on its carbon footprint or the annual election of all directors.
7. Additional curbs on shareholder proposals are not needed.
· Raising resubmission thresholds will stifle new ideas and issues, which typically take time to gain traction with investors.
· The raised resubmission thresholds will keep topics off corporate ballots for years, even though circumstances may change at a company (e.g., independent board leadership tends to be seen as much more urgent when a company is in crisis, and the proposed new thresholds are likely to bar a proposal to separate the roles of CEO and chair at companies with the worst governance records).
· The increased ownership thresholds will especially hamper small investors, the very market participants that SEC Chairman Jay Clayton has made it a priority to protect.
· Until 1983, ownership of a single share of stock carried the right to propose a shareholder resolution. Now we are on a slippery slope that strips that right from more and more small shareholders, whose ideas can be as important and valuable to consider as those of larger holders.
AS YOU SOW: As Shareholder Support for Climate Change and other Environmental, Social, and Governance Issues Grows, SEC Votes to Restrict Shareholder Voice
“The SEC has been unable to point to any demonstrable problem with the current shareholder system or make a case for how its proposal to limit shareholder rights will improve company value,” said Danielle Fugere, president of As You Sow. “To the contrary, this proposed rulemaking has the potential to increase shareholder and company risk, particularly regarding growing climate concerns. We don’t believe that it will withstand public or legal scrutiny.”
BERKELEY, CA—NOV. 5, 2019—The U.S. Securities and Exchange Commission (SEC), led by Chairman Clayton, voted today to severely limit the rights of shareholders, especially small shareholders to file proposals at companies. The SEC 14a8 process was created to ensure that shareholders have the right to seek transparency and disclosure from companies or raise significant policy issues that can create risk or harm company value over time. Such proposals, which are advisory and not mandatory even with 100% of the vote, have the goal of raising critical issues in front of management, boards, and company shareholders. Today’s draconian vote, split along party lines, would limit investor rights in ways that are incompatible with the basic premise that shareholders are owners of companies and should have a voice in the companies they own.
“With this vote, the SEC has apparently inverted its mandate of protecting shareholders to that of protecting companies from shareholder input — even where company action creates increasing risk to shareholders, people, or the environment,” said Andrew Behar, CEO of As You Sow. “This proposal flies in the face of the SEC’s mandate of ensuring transparency, open discussion, and company responsiveness to shareholder concerns.”
Shareholder proposals have served an important role in bringing cutting edge issues to the attention of management and boards, informing shareholders of growing risk, and increasing productive discussion of significant policy issues — in short, increasing transparency and shedding light on company actions. “Shareholders and companies have been well served by this process over the years; allowing company actions to fall back into the shadows is a giant step backward for all,” said Behar.
Climate proposals are an important example of how shareholders have successfully used the process to flag the growing risk to companies and investors of inaction on climate change. Shareholder proposals have shined a light on the importance of climate change; highlighted the risks of inaction; underscored opportunities for responsive companies; flagged lead actors and lagging companies; and ensured that the market is appropriately addressing growing systemic climate risk.
“The SEC has been unable to point to any demonstrable problem with the current shareholder system or make a case for how its proposal to limit shareholder rights will improve company value,” said Danielle Fugere, president of As You Sow. “To the contrary, this proposed rulemaking has the potential to increase shareholder and company risk, particularly regarding growing climate concerns. We don’t believe that it will withstand public or legal scrutiny.”

Linking Investor Engagement with Financial Value
Julie Gorte, Impax Asset Management
Some observers tend to see vote totals on shareholder proposals as binary — either they pass or they don’t. But it is useful to understand the nuances, too. In accounting, a shareholder holding at least 20 percent of a company’s shares has a significant or active interest, and that is something that can influence management decisions. That provides a different lens through which to see the 30 percent average support for shareholder proposals than a simple pass/no pass view. It’s also an indicator that it’s not just a bunch of frustrated political activists interested in these proposals; it’s an indication that a significant proportion of a company’s investors see them as relevant to the company’s financial performance.
Julie Gorte
Senior Vice President for Sustainable Investing, Impax Asset Management
Goldman Sachs’ equity research report “Shareholder Engagement in the Age of Transparency” says: “We believe shareholder resolutions can offer additional insight into emerging material risks and externalities for issues, as well as management responsiveness.”[1] The report also notes that support for environmental and social shareholder proposals has been rising for several years, with nearly 30 percent of votes going in favor of shareholder proposals. Considering that insider ownership for U.S. companies averages about 13.6 percent,[2] it is quite possible that the support for these proposals among outside shareholders is significantly higher.
A recent study [3] that looked at 847 engagements with 660 companies around the globe over a decade (2004-2014) found that successful engagements — those that did improve ESG performance — were correlated with higher sales growth without changing profitability. Moreover, a portfolio of firms that were engaged by shareholders outperformed a matched portfolio of companies that were not engaged by 4.7 percent. Another study,[4] which examined 2,152 ESG engagements at 613 publicly traded firms over a decade (1999–-2009), also found that the companies that were the subjects of these engagements had higher abnormal returns of around 1.8 percent during the year following the engagement, and the successful engagements were associated with higher abnormal returns of 4.4 percent over the following year (and zero for the unsuccessful ones).Results such as these help to explain why the votes in support of these proposals have gone up: They are about things that can and do affect financial performance. For example, of the proposals that did receive majority votes of support in 2018,[5] the engagements included topics that absolutely had financial relevance: the opioid crisis, coal ash risks, climate change and greenhouse gas emissions. Consider that one drugmaker’s stock price lost 80 percent of its value[6] after it was indicted for misleading doctors and public health officials about the effects of its opioid addiction treatment, and one of the major manufacturers of opioids, Purdue Pharmaceuticals, is reportedly looking into declaring bankruptcy in the face of expanding litigation.[7] On the climate change front, 2019 witnessed what The Wall Street Journal described as the world’s first climate change bankruptcy,[8] after PG&E declared Chapter 11 as its liabilities and penalties for destructive wildfires skyrocketed.
Bankruptcies and stock price collapses happen all the time, of course; is there any evidence that proactive work to be more sustainable might lessen them? Yes, plenty. Several recent papers have focused on what we often call tail risk — highly impactful events that can have major implications for value but that are relatively rare historically. One recent paper [9] provides quantitative evidence that investors see strong ESG practices as a hedge against what we call a left-tail risk, or large drop in value. This could be because better sustainability practice reduces firms’ vulnerability to litigation and environmental disasters, both of which can make noticeable dents in companies’ reputational value. Another recent article noted that ESG, while not a traditional style factor, was known to reduce risk in portfolios. [10] A 2018 report from MSCI [11] sheds additional light on that idea, noting that investors are interested in how ESG integration changes both systematic and stock-specific risks in portfolios over multiple time periods. Portfolios with higher ESG ratings had better risk-adjusted returns than their parent indexes.
Climate change, which is one of the main topics in shareholder proposals, is another good example of the connection with financial value. If not addressed, climate change could cost us perhaps five percent of gross domestic product annually in perpetuity,[12] and investors see it as a material source of several kinds of risk and opportunity. One recent paper [13] constructed a portfolio that had long positions in more carbon-efficient firms and short ones in carbon-inefficient firms, and that portfolio generated abnormal returns of 3.5–5.4 percent per year. Another study showed that low-carbon indexes have generally outperformed mainstream benchmarks.[14]
FOOTNOTES:
Derek R. Bingham, Tristyn Martin, Sharmini Chetwode, Christopher Vilburn, Evan Tylenda and SoYoung Lee, “Shareholder Engagement in the Age of Transparency,” Goldman Sachs Equity Research, June 12, 2019.
“Insider and Institutional Holdings by Sector (US),” Damodoran Online, Stern Business School, New York University, Jan. 2019.
Tamas Barko, Martijn Cremers, Luc Renneboog, “Shareholder Engagement on Environmental, Social, and Governance Performance,” European Corporate Governance Institute, May 31, 2017.
Elroy Dimson, Oguzhan Karakas, Xi Li, “Active Ownership,” The Review of Financial Studies, Aug. 12, 2015.
Heidi Welsh, “Proxy Season Review: Social, Environmental & Sustainable Governance Shareholder Proposals in 2018,” Sustainable Investments Institute, Nov. 9, 2018.
Theron Mohamed, “A UK Drugmaker’s Stock Crashed 80% After It Was Indicted for a ‘Truly Shameful’ Opioid-Addiction Scheme, Markets Insider, April 10, 2019.
Berkeley Lovelace Jr., “OxyContin-maker Purdue Pharma Reportedly Exploring Bankruptcy Amid Litigation Over Opioids,” CNBC, March 4, 2019.
Russell Gold, “PG&E: The First Climate-Change Bankruptcy, Probably Not the Last,” The Wall Street Journal, Jan. 18, 2019.
Michael Shafer and Edward Szado, “Environmental, Social, and Governance Practices and Perceived Tail Risk,” July 26, 2018.
Carlo Svaluto Moreolo, “ESG: The Sustainability Factor,” Investments & Pensions Europe, April 2018.
Guido Giese, Linda-Eling Lee, Dimitris Melas, Zoltan Nagy, Laura Nishikawa, “Foundations of ESG Investing,” MSCI, May 2018.
Nicolas Stern, “The Stern Review: The Economics of Climate Change,” Cambridge University Press, March 2014.
Soh Young In, Ki Young Park, Ashby H.B. Monk, “Is ‘Being Green’ Rewarded in the Market?: An Empirical Investigation of Decarbonization and Stock Returns,” Stanford Global Projects Center, April 19, 2019.
Oliver Oehri, Christoph Dreher, Christoph Jochum, “Climate-friendly Investment Strategies and Performance,” Center for Social and Sustainable Products and South Pole Carbon Asset Management Ltd., Nov. 7, 2016.
Investor Coalition Fights Opioids Crisis
By LAURA E. WEISS, CQ

It began as a suggestion from a county health official to leaders of a group of nuns’ money management program. They were addressing climate change, modern-day slavery and immigration — why not the opioid epidemic?
A year and a half later, the mammoth coalition of investors born from that idea wields $2.2 trillion of influence, urging the largest U.S. drug companies to take accountability for playing a role in the opioid crisis. The group, Investors for Opioid Accountability, has cut deals with companies in the business of making or distributing opioid painkillers to review how they oversee sales of the highly addictive drugs and make other corporate governance changes aimed at improving supervision of opioid sales.
“No one is untouched by the opioid crisis in the country — or even globally now as it’s beginning to turn out — but we lead with the investor lens because that is our responsibility and our duty to give an investor voice to it,” says IOA co-leader Meredith Miller. She says the coalition”s 46 members — including state treasurers, public pension funds, faith-based investors and union benefit funds — are hearing from their ministries, citizens or union members about the crisis.
***
IOA’s shareholder proposals include requests for reports on board oversight of risks related to opioid sales, mechanisms for recouping executive pay in the case of misconduct, disclosure of lobbying spending, independent board leadership and other adjustments to oversight mechanisms and how the CEO and other top leaders are paid.
***
IOA has claimed several victories so far. The coalition’s opioid risk report proposal won support from 62 percent of investors in Assertio Therapeutics Inc., which makes opioid painkiller Nucynta. The same proposal neared majority approval at AmerisourceBergen Corp., one of the “big three” U.S. drug wholesalers. IOA says it has a commitment from another large distributor, Cardinal Health Inc., to publish risk reports, recoup executive pay in cases of misconduct and split the roles of CEO and board chair. McKesson, the country’s sixth-largest company, and several manufacturers have also agreed to changes including reviews of how directors oversee opioid sales, avoiding votes on IOA’s proposals.
Gender Pay Equity

Natasha Lamb
Managing Partner
Arjuna Capital
There are gender pay gaps … and then there are median gender pay gaps. Understanding the difference between the two may determine just how much progress women make in terms of fairer compensation in the next decade.
So first, the definitions:
“Equal pay” gap: What women are paid versus their direct male peers, statistically adjusted for factors such as job, seniority, and geography. Often referred to in the context of “equal pay for equal work.”
“Median pay” gap: The median pay of women working full time versus men working full time. This is an unadjusted raw measure used by the Organization for Economic Cooperation and Development (OECD). Women in the US, for example, make 80 cents on the dollar versus men on this basis.
Equal pay gaps measure whether women are being paid commensurate with their peers for the work they are doing today. But median pay gaps measure whether or not women are holding as many high-paying jobs as men. Narrowing the median pay gap means putting more women in leadership (and reaping the performance benefits that diversity affords). And that’s where investors come in. Concerned shareholders in major US financial and tech companies want to make sure the pay gap difference is understood—and acted upon.
Consider the case of Citigroup. While it is true that women at Citi are paid 99% of what men are paid on an equal-pay basis when adjusting for job function, level, and geography, the median pay gap at the financial giant paints a very different picture: Women at Citigroup earn just 71% of what the men earn.
What accounts for the difference? Women are dramatically underrepresented in high-paying positions at Citigroup—and nearly all other major corporations. So, when more US companies begin disclosing their median pay gaps, the numbers are going to be shocking. In fact, Citi’s 29% median pay gap could very well end up being at the lower end for large US financial and tech companies.
This kind of disclosure is not going to happen on its own. But investors are intent on making headway, and establishing benchmarks from which to measure company progress. Between 2016 and 2018, shareholder proposals and concurrent dialogues led by my firm, Arjuna Capital, persuaded 22 companies, including Citi, JPMorgan, Wells Fargo, Bank of America, Bank of New York Mellon, Amex, Mastercard, Reinsurance Group, and Progressive Insurance to publish their gender pay gaps on an equal-pay basis.
Tech giants like Apple, Amazon, Microsoft, Google, and Facebook have been compelled to do the same. And commitments from leading companies often have a domino effect through an industry, putting pressure on more companies to act. The adjusted equal pay gap picture is, in many ways, the easy part of the gender equity story to tell. But it is only half the story. Now, shareholders like us want companies to follow Citigroup’s lead and disclose their median gender pay gaps.
Today, Arjuna Capital is announcing an important new phase of our work: a median pay gap shareholder resolution engaging a dozen major US companies across the banking, tech, and retail sectors, including: Adobe, Amazon, Intel, Facebook, Alphabet/Google, Bank of New York Mellon, Bank of America, Wells Fargo, AmEx, JPMorgan Chase, and Mastercard.
The 12th company we targeted with the shareholder proposal—Citigroup—opted to respond almost immediately, disclosing its median pay gap data through a blog, and pledging to narrow this wider gap. On Jan. 16, 2019, Citi became the first US company to reveal its global median pay gap.
The result was a bit of rough sledding for Citi. National and financial news outlets zeroed in on the shock factor in the data. Headlines read: “Citigroup Admits It Pays Women 29% Less Than Men;” and “Citgroup’s business is money, but not a lot of it goes to its female employees.” Others got it right with headlines focusing on the significance of Citi’s groundbreaking decision to release median figures: “Citigroup is revealing pay day data most companies won’t share” and, perhaps most bluntly, “Citigroup Bravely Announces It Pays Women Like S—t.”
Citi had the courage to break the mold and disclose median pay numbers, and that bravery will pay off in the long run, not only for the company but for its investors, by improving gender diversity throughout the company. A recent study cited in the Harvard Business Review found that wage transparency, in countries that mandate it, not only narrowed the wage gap but increased the number of women hired and promoted into leadership positions.
Citi also made it clear that it is taking the proactive steps needed to fix the median gender pay gap. Its goal is to increase representation at the assistant vice president through managing director levels, to at least 40% for women globally and 8% for black employees in the US by the end of 2021. (Yes, there is a minority pay gap and a minority median pay gap problem, too.)
Multinational companies, including Citi, that operate in the United Kingdom are now under regulatory mandate to disclose median gender pay gaps. In 2018, peer Bank of America revealed a 41% gap for its UK operations. Citigroup reported a 36% median gap for the UK, but prior to January’s announcement, the company had not published median information for its global operations, including the US.
Revealing the whole story of the gender and racial pay gap is essential to create change. Indeed, what gets measured (and disclosed) gets managed. As it stands, the World Economic Forum estimates the gender pay gap costs the economy $1.2 trillion annually. The 20% median income gap for all women working full time in the United States is a disparity that can equal nearly half a million dollars over a career. And the income gaps for African-American and Latina women are at 60% and 55% respectively. At the current rate, women will not reach pay parity until 2059. This depressing statistic is not only bad for women, it’s bad for the economy, and it’s bad for the companies that can benefit now from women’s leadership and talent.
It remains to be seen how many of the 12 companies targeted by Arjuna Capital will agree to the shareholder resolution in 2019. Our pledge is to continue to work with the companies’ leadership to find common ground on our resolution, and to educate the media and public about the median pay gap. We will applaud all good faith efforts to publish median pay numbers because the most effective shareholder activism is not about shunning; it is about casting light on a problem, calling companies to task, and nudging them through the sometimes difficult process of disclosure and reform.
Citi learned that disclosing its median gender pay gap meant a little PR pain in the near term. But it also established itself as the leading US institution on pay equity, doing the honest and real work to address inequity for women and minorities. Concerned shareholders will continue to press other companies to follow suit, because, unfortunately, there remains glaring inequality in the US workplace. And it is high time to tell the whole story.
Kroger and Tropical Forests

Kroger Co., the largest grocery chain in the U.S., agreed to develop and implement a no-deforestation policy after Green Century filed a shareholder resolution with the company, urging them to take action. After the announcement, they withdrew the shareholder resolution with the company.
According to the agreement, Kroger will implement a no-deforestation policy in its private label Our Brands products supply chain by 2020. It also will report on the progress it makes toward its goals through reliable third-party questionnaires.
As one of the largest retailers in the world with an extensive supply chain, Kroger’s new commitment is the kind of corporate buy-in needed to preserve the world’s forests
The Role of Investors in Supporting Better Corporate ESG Performance
For over half a century, the shareholder proposal process has served as an effective way for investors to provide corporate management and boards with insights into their priorities and concerns regarding corporate governance, policies and practices. The process has resulted in numerous important changes to corporate governance in the U.S. Examples include:
Resolutions were the impetus behind the now standard practice – currently mandated by major US stock exchanges’ listing standards — that independent directors constitute at least a majority of the board, and that all the members of the following board committees are independent: audit, compensation, nominating and corporate governance.
In 1987 an average of 16 percent of shareholders voted in favor of shareholder proposals to declassify boards of directors so that directors stand for election each year. In 2012, these proposals enjoyed an 81 percent level of support on average. Ten years ago, less than 40 percent of S&P 500 companies held annual director elections compared to more than two-thirds of these companies today.
Electing directors in uncontested elections by majority (rather than plurality) vote was considered a radical idea a decade ago when shareholders pressed for it in proposals they filed with numerous companies. Today, 90 percent of large-cap U.S. companies elect directors by majority vote, largely as a result of robust shareholder support for majority-voting proposals
A proposal that built momentum even more rapidly and influenced the practices of hundreds of companies in the last few years is the request for proxy access. Resolutions filed by the New York City Comptroller to allow shareholders meeting certain eligibility requirements to nominate directors on the company’s proxy ballot achieved majority votes at numerous companies. As a result, since 2015, at least 400 companies have adopted proxy access bylaws.
“Say-on-pay” vote requirements — now mandated by the Dodd-Frank Act — also resulted from shareholder proposals.
Shareholder proposals or related engagements played a key role in moving close to 160 large companies (including more than half of S&P 100 companies) to commit to disclosure and board oversight of their political spending with corporate funds.
Since 2009, 85 companies have agreed to issue sustainability reports as result of shareholder resolutions. According to the G&A Institute, 81 percent of S&P 500 companies published sustainability reports in 2015 compared to just under 20 percent in 2011.
The first resolution requesting that companies source deforestation-free palm oil that went to vote was in 2011 and received 4.2 percent support. By 2016 more than 20 companies had responded to similar resolutions and protected their brands’ reputations by committing to source deforestation-free palm oil produced by workers free from human rights abuses.
Shareholder proposals have led to wide-scale adoption of international human rights principles as part of corporate codes of conduct and supply chain policies, protecting companies from legal and reputational risk.
A substantial majority of large companies have sexual orientation nondiscrimination policies largely as a result of hundreds of shareholder proposals. A 2016 analysis by Credit Suisse found that 270 companies which provided inclusive LGBTQ work environments outperformed global stock markets by 3 percent annually for the previous six years.
The impact of investor influence strategies
The evidence reveals that investor efforts to engage companies on ESG-related risks and opportunities are associated with better shareholder returns:
Academic research on corporate social responsibility engagements with US public companies over the period between 1999-2009 shows that after successful engagements, companies experience improved accounting performance and governance.
An examination of private engagements conducted by fund manager Hermes demonstrated financial outperformance associated with investor engagement rather than stock picking.
An analysis of the stock performance of 188 companies placed on the ‘focus list’ for ESG engagement by California Public Employees’ Retirement System (CalPERS) found that these companies performed significantly better than their peers (15.27 percent above the Russell 1000 Index) over a 14-year period.
Evidence from collaborative dialogues involving 225 investment organizations over the period between 2007-2017 shows that after “successful” engagements (as defined by a set of pre-determined criteria and scorecards) have occurred, target companies experience improved profitability (as measured by return on assets), while unsuccessful engagements demonstrate no change.
Research from Harvard Business School indicates that filing shareholder proposals is effective at improving the performance of the company on the focal ESG issue, even though such proposals nearly never received majority support. Proposals on material issues are associated with subsequent increases in firm value.
Read the original article here.
Wells Fargo and Boardroom Ethics

Sister Nora Nash and Father Tom McCaney meeting with Wells Fargo
Wells Fargo, on its webpage states: “As part of its commitment to transparency, Wells Fargo agreed to develop the Business Standards Report following a shareholder proposal from a group of shareholders led by the Interfaith Center on Corporate Responsibility. To create the report, Wells Fargo worked with more than 175 leaders and team members under the guidance of the Board of Directors and the company’s top-level Operating Committee.”
The Wells Fargo Business Standards Report was the result of several shareholder resolutions and meetings with the CEO and other Executives. The company supported the proposal when it appeared on the proxy, with a commitment to continued engagement.
The investors, including the Sisters of St. Francis of Philadelphia, continue to seek transparency and monitor performance in light of the company’s past violations of trust, ethics, human rights, and failures to respect employees and customers. The company continues to reckon with its commitment to bringing about change in its culture, risk management, customer services and corporate citizenship.
ESG factors as a good signal for future risk
Jane Jagd, Bank of America
What if we told you how to avoid stocks that go bankrupt?
We think you would listen. Environmental, Social & Governance (ESG) factors are too critical to ignore, in our view. In our earlier report ESG: good companies can make good stocks, we found that ESG-based investing would have offered long-term equity investors substantial benefits in mitigating price risk, earnings risk and even existential risk for US stocks — ESG would have helped investors avoid 90% of bankruptcies in the time frame we examined. Our findings were encouraging enough to warrant a closer look. We here assess how US corporations, regulators and investors are positioned for ESG, and how the market is responding.
ESG is the best signal we have found for future risk
Prior to our work on ESG, we found scant evidence of fundamental measures reliably predicting earnings quality. If anything, high quality stocks based on measures like Return on Equity (ROE) or earnings stability tended to deteriorate in quality, and low quality stocks tended to improve just on the principle of mean reversion. But ESG appears to isolate non-fundamental attributes that have real earnings impact: these attributes have been a better signal of future earnings volatility than any other measure we have found.
US corporates may be behind the curve . . .
Despite empirical evidence of its efficacy, ESG is not drawing much enthusiasm from US corporates. Among companies participating in our survey at our March 2017 BofAML US Investor Relations conference, almost half of the survey respondents indicated they have no resources dedicated to ESG initiatives, and no intentions of implementation. Globally, the theme is burgeoning: ESG-related regulations have doubled since 2015; over 6,000 EU member state companies will be required to publish disclosures; and 12 global stock exchanges require written ESG guidance – but not one is in the US!
. . . but investors are ahead of it & PE multiples are responding
In our May survey of BofAML institutional clients, 20% cited using ESG, well above the estimated 5% of float that corporations believe is held by ESG-oriented investors. In another investor survey, 66% raised issues on sustainability disclosures, and 85% called for improved disclosure in filings. And the investment industry is changing to accommodate governance: for the first time ever, FTSE Russell ruled out the addition of zero voting rights stocks, citing “concerns raised by shareholders.” The market is listening: shareholder-friendly companies have seen significant multiple expansion — and we see strong signs that this re-rating continues.
Read the full text here.
Historic Context for Retail Investor Rights
James McRitchie, Editor, CorpGov.net
While at one time, ownership of a single share of stock came with the right to submit a proposal without restriction as to number or subject, in 1983 the SEC decided it made sense to impose a modest but low submission requirement, setting the threshold at $1,000 held for at least one year. The SEC raised this to $2,000 in 1998, “to adjust for inflation” but did not raise it higher “in light of rule 14a-8’s goal of providing an avenue of communication for small investors.” (File No. S7-25-97)
A study of 286 shareholder proposals submitted between 1944 and 1951 found that 137 or 47% were submitted by the Gilbert brothers. (The SEC Proxy Proposal Rule: The Corporate Gadfly, p. 830 av) The fact that three families submit a disproportionately high number of proposals is not historically unusual.
Without early ‘gadflies’ like the Gilberts and Wilma Soss, shareholders would not have the right to file proposals, vote on auditors, or have executive pay disclosed and there would be even fewer women directors.
Read the full text here.
Understanding ESG Incidents: Key Lessons for Investors
Pax World Fund, Dec 2017
Sustainalytics conducted a quantitative analysis of their incident dataset, reviewing 29,000 company activities around the world that generated undesirable social or environmental effects. They found that incidents are increasing, some industries are more exposed than others, and some regions are more exposed as well. These activities can impact company share price, so asset managers and owners can benefit from applying incidents analysis in their portfolios.
Read the full text here.
From Sustainability to Business Value
Pax World Fund, Feb 2018
ING interviewed 210 finance executives in US-based large-cap and mid-cap companies about the importance of sustainability to corporate strategies. They found that over 80% of firms are embedding sustainable thinking into their business growth plans and that nearly half reported that sustainability concerns actively influence their growth strategies. The firms with the most robust sustainability strategies tend to have had better revenue, borrowing and credit-ratings outcomes.
Read the full text here.
New York City Pension Funds Promote Boardroom Accountability

Michael Garland, Assistant Comptroller for Corporate Governance and Responsible Investment in the Office of New York City Comptroller Scott Stringer
With an average retirement benefit of $38,000 per year, it is likely that many of our members only participate in the capital markets through their role as pension fund beneficiaries. Our members are true Main Street investors, as opposed to a group using that name that represents the interests of company managers. We are long-term share owners of approximately 10,000 public companies around the world, including more than 3,000 U.S. companies.
A particularly good example of market change from shareowner proposals relates to “proxy access” — that is, a mechanism to permit shareowners to include their nominees on the company proxy card for a minority of board seats under certain circumstances. In 2014, Comptroller Stringer and the NYC Funds launched the Boardroom Accountability Project, a campaign to implement proxy access on a company-by-company basis in the U.S. market using shareowner proposals.
Today, largely as a result of the Boardroom Accountability Project, approximately 540 U.S. companies, including 70 percent of S&P 500 companies, have enacted proxy access bylaws with terms similar to those in the vacated SEC rule, up from only six companies in 2014 when we launched the project. In July 2015, economic researchers at the SEC released a study that analyzed the public launch of the Boardroom Accountability Project and found a 0.5 percent increase in shareowner value at the first 75 firms that received proxy access shareowner proposals from the NYC Funds. The SEC staff’s findings were consistent with a 2014 CFA Institute study that found that proxy access on a market-wide basis has the potential to raise U.S. market capitalization by as much as 1 percent, or $140 billion.
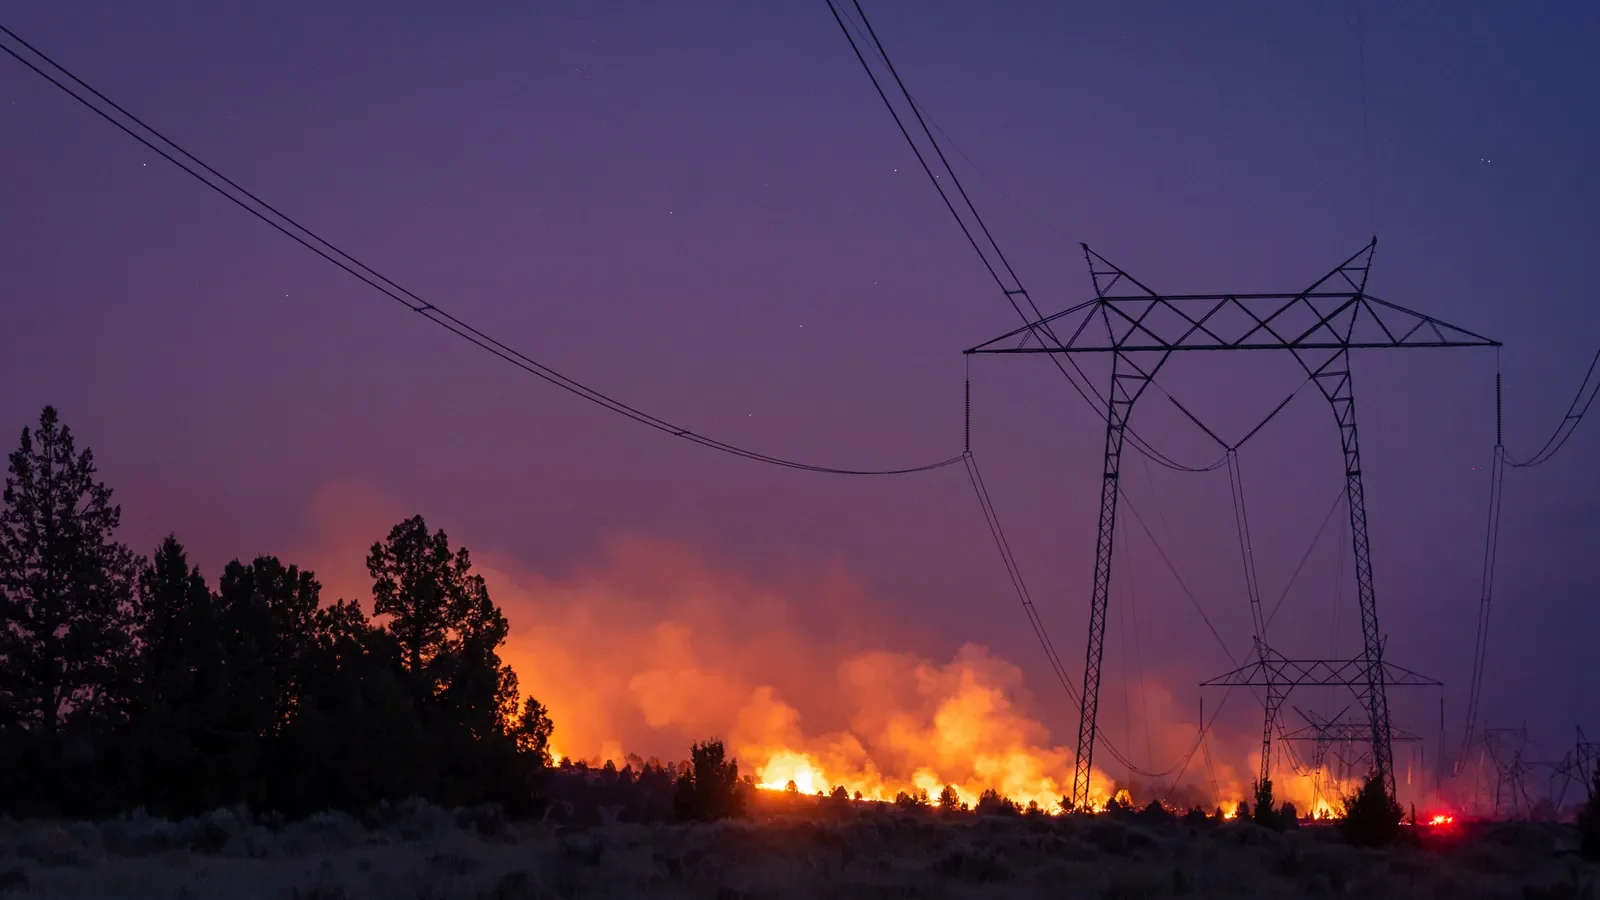
Midwest Utilities and Climate Change
Seventh Generation Interfaith Coalition for Responsible Investment
Seventh Generation Interfaith (SGI) is a coalition of 40 faith-based and values-driven institutional investors located in the Mid-Western United States. Shareholder proposals have had a major impact on midwestern utility companies. Proposals submitted to the WEC Energy Group and CMS Energy Corporation asked each to publish an assessment of the long term impacts on the company’s portfolio of public policies and technological advances consistent with limiting global warming to no more than two degrees Celsius over pre-industrial levels. The proposals were withdrawn upon company commitments and subsequent publishing of scenario analyses, and leading to aggressive GHG reduction goals. (See CMS Energy Climate Assessment Report; WEC Pathway to a Cleaner Energy Future). Engagement with Xcel Energy preceded a groundbreaking announcement of the company’s commitment to zero-carbon electricity by 2050 and publishing of their Carbon Report (Xcel Energy Building a Carbon-free Future). A proposal at MGE Energy, subsequently withdrawn, also led to their announced commitment to net-zero carbon electricity (Wisconsin State Journal, May 14, 2019).