Silencing voices at the ballot box and in the boardroom?
Sanford Lewis
As voting rights and access to the ballot box dominate national debate, a parallel struggle is unfolding in corporate America: who gets to decide what a company’s shareholders are allowed to vote on?
In a stunning parallel to the current fights over election rights, the Securities and Exchange Commission (SEC) is proposing to rescind its shareholder proposal rule, a more than 80-year-old process that lets shareholders engage with fellow shareholders and their portfolio companies. For retirees and retail investors whose savings are invested in public companies, the federally regulated shareholder proposal process is one of the few direct tools available to ensure effective risk management and corporate governance.
For decades, shareholders have relied on this right to bring important issues to fellow investors for a vote. Shareholder proposals have held boards accountable by requiring that they receive a majority vote to remain on the board. Other proposals have pushed companies to address climate-related financial risks that could pose significant liabilities in the future. Proposals have addressed excessive executive pay and other abuses of power. Recently, proposals have sought transparency on risks related to companies’ deployment of Artificial Intelligence. Shareholder proposals are an effective way to communicate with management about how it safeguards the company against a range of AI risks.
A shareholder seeking more information about an issue from a company can submit a proposal, which acts as a referendum to gauge whether other investors also think the information is material to their decision-making. Even proposals that receive majority support from investors are non-binding, making the filing of shareholder proposals an inherently non-adversarial engagement tool. It is also an efficient process, because it means inclusion of a few pages in a much larger mailing that the company is already sending to all shareholders.
Despite the importance of the shareholder proposal process, the SEC is threatening to turn shareholder democracy on its head by locking out these proposals from corporate voting materials. Every public company circulates an annual proxy statement to its shareholders, signifying the items to be voted upon at the company's annual meeting. The vast majority of votes are currently cast through the proxy card which contains yes or no checkboxes for each item to be voted; the proxy card is accessible to widely dispersed shareholders who do not intend to attend the meeting in person.
Under the SEC proposed changes, shareholder proposals would be locked out of the company's proxy materials. Shareholders could still raise proposals from the floor of a meeting under state law. But a proponent who wants votes from people not attending the meeting would have to file and mail their own proxy materials a very expensive proposition that only the most well-funded investors can do.
The rule in place today empowers small shareholders to raise important issues; the rescission of the rule would shut retail shareholders out of the process. Only the wealthiest investment firms and investors would be able to submit shareholder proposals and send mailings necessary to get substantial votes. These investors, however, seldom file shareholder proposals because their holdings in the company are large enough that they don't need to file proposals in order to get the attention of the board and management.
The SEC’s proposed rules would prevent proposals expected to be introduced in the meeting from appearing in full on the company’s proxy statement and provide no opportunity to vote on them on the company’s proxy card.
Before the SEC Rule Change
Today, shareholders have the right to file proposals and to bring important matters before their fellow shareholders. The mechanics of this process have strong guardrails to filter out unreasonable requests. For example, proposals must be relevant to the company, not merely address the company's ordinary business, and the proponent must meet ownership requirements. Proposals cannot exceed 500 words, and rules disqualify them from being refiled if they receive votes below a certain threshold. Once a proposal is successfully filed, it appears in the company’s proxy statement — an annual filing the company distributes to all its shareholders with information on all items that will be voted on. This includes issues shareholders want to raise, as well as management topics such as background information on director elections and approval of executive pay.
Along with the proxy statement, the company distributes a proxy card that most shareholders use to cast their vote and make their voices heard.
This is an essential right that comes with owning part of a company through shares, but the SEC is trying to take that away.
Today, the proxy card lists director elections and management’s proposals first. Proposals submitted by shareholders under Rule 14a-8 follow. Each item has its own boxes to vote For, Against, or to Abstain. Exhibit A shows an example.
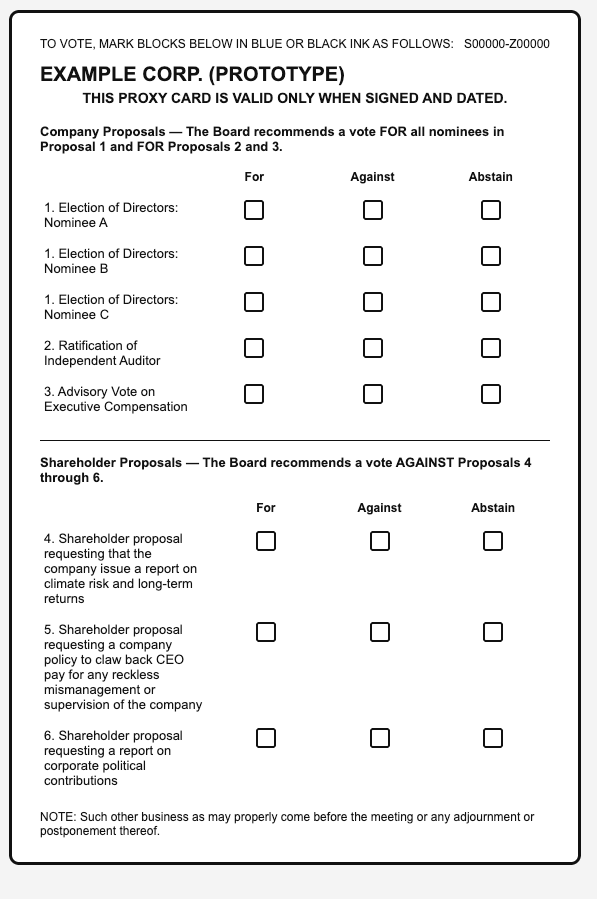
Exhibit A. Proxy card under current rules (illustrative)
Under the proposed rules, the company’s proxy card would list no shareholder proposals at all. Shareholder proposals are silenced on the corporate proxy card. Instead, the SEC proposal entitles management to cast the investor’s own votes AGAINST any shareholder proposal raised at the meeting — unless the investor checks a small, poorly explained box to withhold management's discretionary authority.
As Exhibit B shows, the shareholder proposals on the card would be replaced by a single question: will the shareholder let management vote the shareholder’s own shares as it sees fit? There would be no option on the company ballot to vote FOR any of the shareholder proposals presented, only an option to notify the company that the shareholder doesn't want the company to cast his or her votes against one or more of those shareholder proposals that are not even visible on the management ballot card.
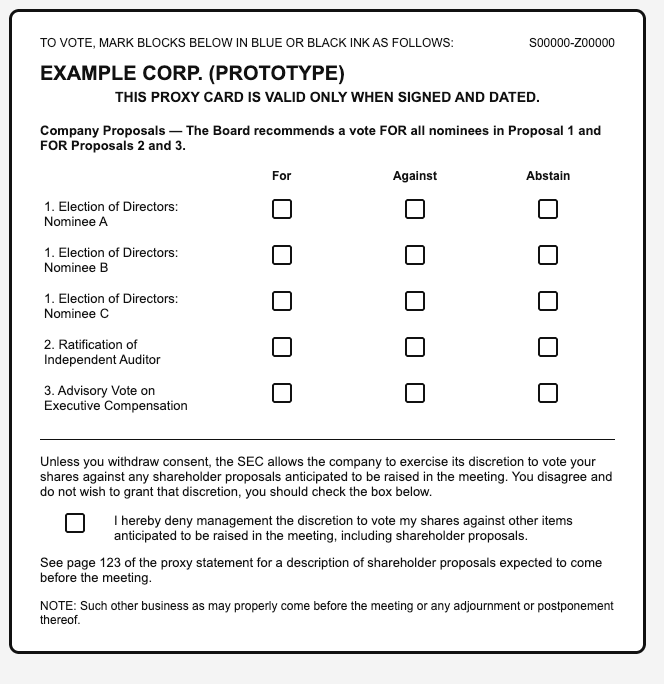
Exhibit B. Proxy card under the proposed rules (illustrative)
The card would not list the proposals or provide any information about shareholders' concerns or requests. Shareholders would have to dig through a separate document, the proxy statement, to find a one-line description generated by the company of any shareholder proposals the company expects to come up for a vote.The full 500 word proposals would not appear in the proxy statement at all.
The proxy rules have long ensured that individual shareholders can easily vote on proposals raised by fellow shareholders. The SEC proposes to end that.
Section 14(a) of the Securities Exchange Act of 1934 is the law on which the shareholder proposal process was built. It rests on a simple principle: investors shouldn't be asked to hand over their voting authority without adequate information about what will be decided. Rescinding Rule 14a-8 abandons that protection. It would return us to the pre-1934 world, where poorly informed shareholders signed blank checks and management called the shots.
Those who are alarmed by this move by the SEC have till November 20th to comment. You can comment directly on the SEC website or go to http://protectshareholdervoice.com for additional notes and a tool for commenting.
A right that only a few shareholders can afford to exercise is no right at all.
The Commission’s proposal anticipates that Rule 14a-4 will be utilized as an alternative to proposals filed under Rule 14a-8, while overlooking the significant barriers that conducting independent solicitations pose for investors. Under the Commission’s proposed model for contested solicitations, firms would be allowed to leave shareholder proposals off of management proxy ballots and automatically count unvoted shares against proposals on a contested ballot, necessitating the solicitation of a higher percentage of shares for shareholder proposals to have any chance of achieving majority support.
The SEC says shareholders will still have a voice through independent solicitations, even as it seeks to rescind Rule 14a-8. Investors filing their own proxy statements is no substitute for access to company ballots. The cost of mailing materials alone makes this "alternative" inaccessible to most shareholders. A right that only a few shareholders can afford to exercise is no right at all.
The SEC Should Avoid Overreach and Support Investors' Fiduciary Duty
The Securities and Exchange Commission is taking steps that could change how shareholders exercise their ownership rights and how institutional investors manage risk. The issue is larger than environmental, social and governance investing. It goes to a basic question of fiduciary duty: Can an asset owner evaluate information that may affect the value of its portfolio without being treated as a political activist?
The SEC's Shift in Policy
The SEC has moved beyond debating particular ESG practices. In August, the Division of Corporation Finance announced that it would stop responding to shareholder-proposal no-action requests altogether. Companies must still notify the SEC when they intend to exclude a proposal, but the staff will no longer indicate whether it would object
In September came a more consequential step: the Commission the federal rule that gives shareholders a way to place qualifying proposals in corporate proxy materials. Under the proposal, questions about shareholder proposals would be left primarily to state law and corporate governing documents. [Chairman Paul Atkins says the change is necessary because the SEC should not intrude into state corporate law.
A Campaign Against "Woke" Proposals
The debate over federal versus state authority is legitimate. But the SEC's policy direction also sits squarely within a larger political and business campaign against ESG and against shareholder proposals characterized as ideological or "woke."
In a 2022 comment letter, the Business Roundtable called for Rule 14a-8 to be restored to what it considers its original purpose by excluding proposals that advance "broad ideological agendas .It argues the process should focus on long-term value creation and has urged Congress and the SEC to act.
The U.S. Chamber of Commerce has taken a similar position. On the day the SEC announced its proposal to rescind Rule 14a-8, the Chamber welcomed the action saying special interests had exploited the rule to advance their agendas at the expense of public companies and shareholders. The alignment matters. The Trump administration, business organizations and federal agencies are challenging ESG, DEI and related shareholder activity as ideological, while the SEC is changing the regulatory structure that governs how shareholders bring such matters before fellow owners. One need not assume the SEC is acting at the direction of these organizations to recognize that their policy positions and the Commission's proposed rule changes point in the same direction.
But a political label does not answer an investment question.
A pension fund does not become a political organization because it evaluates workforce turnover. An endowment does not abandon fiduciary discipline because it examines climate exposure. A foundation does not become an activist because it asks whether human-capital practices affect financial performance. Investors routinely examine information that management finds inconvenient or that political constituencies find controversial. The fiduciary test is narrower: Does the information have a reasonable connection to risk, return, valuation or long-term financial performance?
Activists Must Answer with Evidence
Shareholder advocates also have a responsibility. When the Business Roundtable, the Chamber and their allies call ESG proposals "woke," proponents should respond with evidence of financial materiality, not an appeal to social importance. They should explain how an issue can affect revenue, costs, capital allocation, productivity, litigation exposure, regulatory risk, access to capital, workforce stability or long-term enterprise value.
A pension fiduciary need not support a proposal because it advances a social objective. The question is whether the underlying factor could reasonably affect beneficiaries' economic interests. Employee turnover that affects productivity is a financial consideration. So is a governance practice that creates material litigation or regulatory exposure, or a climate risk that threatens assets, supply chains, insurance costs or capital expenditures.
This approach is consistent with the SEC's own emphasis on materiality. Even the Business Roundtable has suggested that climate-related information should be disclosed when material to investors .The same standard should apply to ESG and anti-ESG proposals alike, without first asking whether the subject is politically conservative or progressive.
It also gives advocates a stronger response to the SEC's criticism of Rule 14a-8.Commissioner Mark Uyeda has argued that some proposals are pushed by political interests with no fiduciary obligation to the company or its shareholders, and that some subjects lack material relevance.Those concerns should not be dismissed. They should be answered proposal by proposal.
The burden runs in both directions. Companies and trade associations should not be able to wave off a proposal by labeling it "woke." Proponents should not expect support merely because their goal is desirable. Both must address the same question: What is the economic connection between the issue and long-term financial interests?
What Rescission Would Change
Rule 14a-8 has never required investors to support every proposal. It gives shareholders a way to bring qualifying matters before fellow owners, who then decide. Some proposals may be political, duplicative, immaterial or overly prescriptive. Others address matters investors reasonably believe affect corporate value. The proper response is to examine the economic facts, not to presume an entire category of subjects is ideological.
Rescission would change that balance. The SEC says it restores the traditional authority of state corporate law. Critics counter that it could produce different shareholder rights depending on a company's state of incorporation and give boards greater control over what reaches shareholders. The business groups that have pressed for narrowing the rule would be among the beneficiaries.
Smaller shareholders have the most to lose. Large institutions can engage companies privately, hire lawyers and consultants, and speak directly with management. A small shareholder has far fewer resources, and the federal proxy process has offered a relatively inexpensive way to put a question before fellow owners. The retreat from the no-action process adds uncertainty, leaving companies and proponents to resolve disputes through other means, including costlier litigation.
The full article also addresses the SEC’s October report on Climate Action 100+
Shadow SEC Statement No. 16: Retain Rule 14a-8
By John Coates, John C. Coffee, Jr., James D. Cox, Merritt B. Fox and Joel Seligman October 13, 2026
We oppose rescission of SEC Rule 14a-8.
Rule 14a-8 has for 80 years been a useful, congressionally authorized component of the U.S. capital markets, fully compatible with the long-standing dual state and federal system governing public companies. Reasonable people may disagree reasonably about whether the current version of Rule 14a-8 is perfectly calibrated to obtain the greatest net benefits. We do not agree that the Commission has come close to making the case that Rule 14a-8 does not provide any net benefits whatsoever, much less that wholesale repeal will provide more net benefits than either the status quo or reasonable alternatives to the current rule.
There are many policy reasons to oppose rescission. Most obviously, proposals under Rule 14a-8 have been approved by shareholders numerous times on topics core to corporate governance, such as majority-board election requirements and classified boards—persuasive evidence (not seriously discussed in the proposing release) of the value of allowing shareholders to communicate via proxy statements and votes on matters of common interest. Many other proposals have received enough supporting votes to signal to boards the need for attention to specific topics, and boards have responded to those signals. Many other proposals have received few positive votes, and have failed to receive more votes over time, providing feedback to sponsoring shareholders that proposals need to be refined, improved, or dropped.
Also important to any serious analysis would be an informed and good faith attempt to anticipate what would follow from rescission. We are confident that shareholders will not sit by silently as boards mismanage or misgovern their companies or rely on the “Wall Street rule” (of exit), especially given how many institutional investors are not permitted by their own commitments to sell. When, predictably, at least some companies are seen to be underperforming or engaged in poor decisions, shareholders will use alternative tools in lieu of Rule 14a-8 proposals. Those tools may well disrupt corporate governance far more than non-binding proposals submitted under Rule 14a-8. Proxy fights, coalitions with hedge fund activists, withhold-vote campaigns, negative votes on management proposals, shareholder-sponsored binding bylaw amendments, and lawsuits are among those tools. Say-on-pay votes will continue as they are mandated by statute. The current release almost entirely fails to treat these possibilities with the attention they deserve. We also note the SEC made a major change in how it implemented Rule 14a-8 just a year ago, and it does not adequately review facts about the effects of that change in its current rule proposal.
But the Commission’s own release presents policy reasons for repeal as secondary to its legal rationale. The Commission contends that Rule 14a-8 exceeds the Commission’s authority under Section 14(a) of the Securities Exchange Act of 1934 and improperly intrudes on a domain long reserved to the states. In the interest of brevity, the rest of this statement focuses on the SEC’s legal rationale, which provides an independent and sufficient basis for rejecting it.
That justification is wrong on its own terms. Rule 14a-8 does not create any substantive right enforceable under state corporate law, and it displaces nothing that state law otherwise governs. Proposals included under the rule are precatory; they bind no one, alter no charter, and effect no corporate action that state law does not already fully control. What the rule actually regulates is the content of a federal disclosure document—the company’s own proxy statement—a subject squarely within the Commission’s Section 14(a) authority since 1934. A shareholder has always been free to raise the identical resolution from the floor of a meeting; Rule 14a-8 only concerns whether that proposal may also appear in the company’s proxy materials. That is a question about the scope of a federal communications channel, not an intrusion into state corporate governance.[1] The fact that in-person attendance at meetings had ceased to be a meaningful way for shareholders to exercise voting rights was evident in 1934 and is not a change that can justify a rescission of a long-standing rule on any ground, much less legal authority.
The U.S. House Commerce Committee report accompanying the Securities and Exchange Act of 1934 responded to a proxy system described by critics as “a self-perpetuation and a self-approval device” for incumbent management, [2]and the companion Senate report complained that “[t]oo often proxies are solicited without explanation to the stockholder of the real nature of the questions for which authority to cast his vote is sought.”[3] The House report grounded the proxy provisions on the idea of “fair corporate suffrage”[4]—the notion that a shareholder’s formal voting right meant little in practice if the only practical mechanism for exercising it (the proxy) was controlled entirely by management, unconstrained by any disclosure or fairness requirement. The stated purpose of what became Section 14(a) was to give the Commission “power to control the conditions under which proxies may be solicited with a view to preventing the recurrence of abuses which have frustrated the free exercise of the voting rights of stockholders.”[5]One clear gap was the inability of many shareholders to communicate with each other about shareholder resolutions and other topics of interest, because as their numbers grew, their ability to do so at a state-law-mandated shareholder meeting had steadily diminished.
Rule 14a-8 addresses another gap in disclosure when (as customary) a corporation solicits the authority to vote shareholders’ shares on any matter that may arise at a shareholder meeting. If such requests are made with corporate knowledge that a shareholder intends to seek action on a proposal at the meeting, the corporation would need to communicate its position about the proposal as part of its proxy solicitation. Without that disclosure, the corporation risks material omission liability, and shareholders risk having their authority misused to vote on an uninformed basis. Rule 14a-8 governs that process with guardrails that protect companies and shareholders alike in the state-law based voting process.[6] The SEC’s proposing release does not adequately consider how this goal of the rule would be addressed in its absence.
Nothing about modern corporate governance has eliminated the need for shareholders to communicate with each other to instruct and oversee proxies or engage in informed governance with full disclosure—a core mandate of the securities laws. No statute bearing on that fundamental need has relevantly changed since Rule 14a-8 was adopted in 1942 to partly address the gaps emphasized by Congress. The Commission does not identify any statutory change of note, nor any case law casting meaningful doubt on the legality of Rule 14a-8.[7] To the contrary, more than a dozen decisions have held or presumed over the past 80 years that Rule 14a-8 or its predecessor was and remains authorized.[8] The SEC does nothing to address much less dismiss that contrary body of law,[9] or the plain language of the statute it purports to interpret. The SEC’s only attempt to invent a justification for its volte face is to stress the fact that proxy communications have “effectively” or “de facto” displaced resolutions made in person at shareholder meetings. But that fact was a logical result of and contemplated by the Securities Exchange Act of 1934 itself, and it has been a fact for decades. It is not a new fact that somehow justifies drastically re-interpreting the authority the statute gives the SEC. Proposals made under Rule 14a-8 continue to have only the legal effect given to them under state corporate law, and the Commission’s efforts to suggest otherwise are supported by no facts.
An agency that reverses an 80-year, consistently applied interpretation of its own authorizing statute without pointing to any intervening change in the law—whether statute or governing case law—mischaracterizing the practical effect of its own rule, has not offered the “reasoned explanation” the Administrative Procedure Act requires for changed agency positions.[10] The most basic element of legal reasoning is to consider opposed arguments and authorities. The same is true for “reasoning” under the APA. A final rule resting on the SEC’s current rationale would be vulnerable to vacatur as arbitrary and capricious.
The Commission may believe that Loper Bright Enterprises v. Raimondo[11] supports its position, since that decision holds that courts owe no deference to an agency’s interpretation of the statutes it administers. But Loper Bright cuts the other way. Its lesson is that an agency’s legal interpretation must now stand or fall on the merits of its reasoning, not on the agency’s say-so.[12] The interpretation offered in this release does not stand on its merits: It is thinly reasoned and unsupported by serious legal analysis, and it reads far more naturally as a restatement of the political commitments of the current single-party Commission than as an exercise of the Commission’s expertise in administering Section 14(a). Loper Bright confirms this proposal is entitled to zero deference from a reviewing court.
The Commission should withdraw the proposal.
ENDNOTES
[1] “Where … the Commission has prescribed a rule under its clear authority to regulate the proxy process, it cannot be said that “the [Commission]’s assertion of authority directly invades the ‘firmly established’ state jurisdiction over corporate governance and shareholder voting rights.” Interfaith Ctr. on Corp. Resp. v. SEC, 786 F. Supp. 3d 97, 135 (D.D.C. 2025) (quoting Bus. Roundtable v. Sec. & Exch. Comm’n, 905 F.2d 406, 413 (D.C. Cir. 1990) (quoting CTS Corp. v. Dynamics Corp. of Am., 481 U.S. 69, 89 (1987))).
[2] Sheldon E. Bernstein & Henry G. Fischer, The Regulation of the Solicitation of Proxies: Some Reflections on Corporate Democracy, 7 U. Chi. L. Rev. 226, 227 (1940). See also H.R. Rep. No. 1383, 73d Cong., 2d Sess., 13 (1934) (“Fair corporate suffrage is an important right that should be attached to every equity security bought on a public exchange,” and that management “should not be permitted to perpetrate themselves by the misuse of corporate proxies.”)
[3] S. Rep. No. 1455, 73d Cong. 2d Sess. 75 (1934).
[4] H.R.Rep. No. 1383, 73d Cong., 2d Sess., 13 (1934).
[5] Id. at 14.
[6] E.g., SEC v. Transamerica Corp., 67 F. Supp. 326 (D. Del. 1946) (requiring re-solicitation of proxies by company given its knowledge of planned shareholder proposals, upholding predecessor of Rule 14a-8), aff’d, 163 F.2d 511 (3d Cir. 1947); cf. New York City Emps. Ret. Sys. v. Am. Brands, Inc., 634 F. Supp. 1382, 1386 (S.D.N.Y. 1986) (stating that omission of a shareholder proposal from proxy materials in violation of Rule 14a-8 is “inherently misleading”).
[7] The SEC cites Santa Fe Industries, Inc. v. Green, 430 U.S. 462, 479 (1977) and Bus. Roundtable v. SEC, 905 F.2d 406, 410 (D.C. Cir. 1990). Neither addressed Rule 14a-8. Santa Fe limits its focus to areas “where established State policies of corporate regulation would be overridden.” Id. at 479. Few states have elaborated rules for when shareholder proposals may or must be included in company proxy statements, and nothing about Rule 14a-8 would override any state laws that are adopted to do so. Business Roundtable stresses a point that undercuts the SEC’s current legal position: “Proxy solicitations are, after all, only communications with potential absentee voters. The goal of federal proxy regulation was to improve those communications and thereby to enable proxy voters to control the corporation as effectively as they might have by attending a shareholder meeting.” 905 F.2d at 410 (emphasis in original).
[8] S See, e.g., Roosevelt v. E.I. du Pont de Nemours & Co., 958 F.2d 416, 422–23 (D.C. Cir. 1992) (“It is obvious to the point of banality . . . that Congress intended by its enactment of [S]ection 14 . . . to give true vitality to the concept of corporate democracy.”); Grimes v. Centerior Energy Corp., 909 F.2d 529 (D.C. Cir. 1990); Med. Comm. for Human Rts. v. SEC, 432 F.2d 659 (D.C. Cir. 1970), vacated as moot, 404 U.S. 403 (1972); AFSCME v. Am. Int’l Grp., Inc., 462 F.3d 121 (2d Cir. 2006); Trinity Wall St. v. Wal-Mart Stores, Inc., 792 F.3d 323 (3d Cir. 2015); SEC v. Transamerica Corp., 163 F.2d 511 (3d Cir. 1947); Dyer v. SEC, 266 F.2d 33 (8th Cir. 1959); As You Sow v. Chubb Ltd., No. CV 26-734 (SLS), 2026 WL 879666 (D.D.C. Mar. 31, 2026); Interfaith Ctr. on Corp. Resp. v. SEC, 786 F. Supp. 3d 97 (D.D.C. 2025); United Church Bd. for World Ministries v. SEC, 617 F. Supp. 837 (D.D.C. 1985); Lovenheim v. Iroquois Brands, Ltd., 618 F. Supp. 554 (D.D.C. 1985); SEC v. Transamerica Corp., 67 F. Supp. 326 (D. Del. 1946), aff’d, 163 F.2d 511 (3d Cir. 1947); Tosdal v. Nw. Corp., 440 F. Supp. 3d 1186 (D. Mont. 2020); Amalgamated Clothing & Textile Workers Union v. Wal-Mart Stores, Inc., 821 F. Supp. 877 (S.D.N.Y. 1993); N.Y. City Emps.’ Ret. Sys. v. Am. Brands, Inc., 634 F. Supp. 1382 (S.D.N.Y. 1986); Peck v. Greyhound Corp., 97 F. Supp. 679 (S.D.N.Y. 1951); KBR Inc. v. Chevedden, 776 F. Supp. 2d 415 (S.D. Tex. 2011); Apache Corp. v. N.Y.C. Emps.’ Ret. Sys., 621 F. Supp. 2d 444 (S.D. Tex. 2008); see also CA, Inc. v. AFSCME Emps. Pension Plan, 953 A.2d 227 (Del. 2008).
[9] Indeed, it cites only three court decisions and provides no reasons to reject the settled legal understandings reflected in any of those decisions, merely stating “the Commission disagrees.”
[10] See FCC v. Fox Television Stations, Inc., 556 U.S. 502, 529 (2009); Motor Vehicle Mfrs. Ass’n v. State Farm, 463 U.S. 29, 42 (1983).
[11] 144 S. Ct. 2244 (2024).
[12] See id. at 392 (explaining that under Section 706 of the APA, “it thus ‘remains the responsibility of the court to decide whether the law means what the agency says'” (quoting Perez v. Mortg. Bankers Ass’n, 575 U.S. 92, 109 (2015) (Scalia, J., concurring in judgment)).
This post comes to us from the Shadow SEC, whose members are professors John Coates at Harvard Law School, John C. Coffee, Jr. at Columbia Law School, James D. Cox at Duke University School of Law, Merritt B. Fox at Columbia Law School, and Joel Seligman at Washington University School of Law.
Why the Proposed Repeal of SEC Rule 14a-8 Matters for You
Oct 08, 2026
If you have a 401(k), you’re a shareholder. A proposal would strip away one of your oldest rights.
If you have any money invested in “the market”—a 401(k), retirement account (IRA), pension, 403(b), brokerage account, etc—you are a shareholder. A share is simply a piece of a company. You’re a part owner. You’re likely Jeff Bezos’s boss, and Mark Zuckerberg’s boss, and Jensen Huang’s boss.
On October 7, I joined a panel discussion hosted by Columbia University’s Sustainable Investing Research Initiative (SIRI). The panel was part of SIRI’s Pathways to Consensus program and titled “Who Gets a Say? Rule 14a-8 and the Future of Shareholder Voice.”
You’re a shareholder—with the associated rights and abilities. You deserve to know what Rule 14a-8 is and why folks at Columbia University are asking about your future.
An excerpt from Greg’s adapted remarks at the panel:
Shareholder Proposals
Since 1942, shareholders have been able to raise their hand to offer a proposal of a “proper subject” for a vote by all shareholders. In general, proper subject proposals are non-binding: even a proposal with 99% shareholder support is only a suggestion. Proposals also can’t direct regular business operations: shareholders are not management. Most proposals deal with governance or structural issues like calling for the CEO and Board Chair to be two different people or calling for shareholders to get a regular vote on executive pay and bonuses.
With in-person meetings replaced by proxies, the SEC has required companies to include shareholder proposals in their voting materials sent to all shareholders, even when the company disagrees. The premise of this requirement is that it’s materially misleading for a company to omit from proxy materials an issue the company knows will be raised at that annual meeting.
For more than eighty years, the SEC has regulated the definition of a “proper subject” for a shareholder proposal. In an annual process, shareholders submit questions or ideas to company management to be included in the annual voting materials. Corporations review these proposals, and often ask the advice of the SEC if that proposal is a “proper subject” and so must be included, or if they can tell the shareholder no, we won’t be voting on that idea. The rule dictating this is known as Rule 14a-8, because it’s issued under Section 14(a) of the Securities Exchange Act.
Rule 14a-8 has been amended, reinterpreted, and legally challenged every few years since its creation. The rule continues to be debated today, but it has facilitated shareholders getting concerns onto corporate voting materials that company leadership would rather not discuss. That’s a good thing because companies work for—are owned by—shareholders.
Why this matters for you
That might all change soon, though. Last month, the SEC proposed rescinding Rule 14a-8 in its entirety and divesting its ability to regulate the shareholder proposal process to the states and to companies’ own bylaws. And no, states do not have their own process or clear guidelines to fill the gap this would leave in deciding what is a “proper subject.” Shareholders—you—would be left to start from the beginning and advocate for the right and ability to get questions and suggestions on corporate proxy materials once again—something that hasn’t been in real doubt since America started formally regulating its financial markets.
The SEC’s proposed rescission of Rule 14a-8 is open for public comment through November 20, 2026, and will likely take many months or years to work its way through the regulatory and legal system. In the meantime, other things are happening across financial markets and corporate America to insulate company management and limit the power of shareholders. More companies like SpaceX and Anthropic are diluting the voting power of regular investors and concentrating power of massive public companies in a few individuals. Companies are developing new retail voting programs allowing shareholders to set default voting policies in line with corporate leadership’s recommendations. Texas now lets companies require shareholders to own $1 million or 3% of a company’s stock before submitting a proposal.
As one-offs, these actions might not have an effect on your 401(k) or retirement accounts. Taken together, every family saving for college and every worker saving for retirement will see a less open, more concentrated, financial and economic system than what they’ve known, with unknown future implications for the value of their dollars.
The SEC’s Proposal to Eliminate Rule 14a-8 Removes Accountability
Oct 09, 2026
Watering down financial regulations makes it easier for companies to put profits over people.
Some background: State treasurers like me are sounding the alarm on the Trump administration’s proposal to eliminate a safeguard that has given investors a voice for more than 80 years: Rule 14a-8. This gives eligible shareholders the ability to include qualifying proposals in a company’s proxy materials, the documents investors receive before voting at an annual meeting. In doing so, eligible shareholders can raise concerns with the companies they own and bring those concerns before other investors.
The SEC’s proposal to eliminate Rule 14a-8 is a direct threat to the rights of long-term investors, and I am concerned it will curtail our ability to hold public companies accountable.
Accountability to shareholders is the foundation of public markets, and engaged shareholders make companies stronger. Weakening the federal shareholder proposal process is not going to make the sustainability risks for companies go away. It’s just going to make it harder for shareholders to raise them.
Listen to my remarks on a For the Long Term press all about the SEC rule change.
As Illinois’ Chief Investment and Banking Officer, I have a responsibility to protect the interests of taxpayers, retirees, and college savers. Shareholder proposals are an important tool for ensuring that companies address material risks that can affect workers, consumers, communities, and investors alike. They are also a key tool for engaging with boards to make sure their actions and oversight align to driving long-term durable returns.
The SEC should be protecting investors, not making it easier for companies to avoid accountability, and I strongly oppose this proposal and urge the Commission to preserve Rule 14a-8 and the shareholder rights it protects.
I have used shareholder proposals to encourage stronger health and safety practices at companies, to advocate for corporate boards to prioritize patients and quality of care when providing healthcare, and to enhance board oversight of material sustainability risks. Eliminating this rule will not make financial, governance, or operational risks disappear. It will simply make them harder and more expensive to flag. Replacing a uniform federal framework with a complex patchwork of state laws and company-by-company rules will increase inefficiencies, costs, and disputes.
Let me offer an example of this process working correctly. In 2023 and 2024, my Office supported shareholder proposals filed by Proxy Impact that called for Meta to assess child safety and implement harm reduction measures on Meta platforms. Two years later, the issue of child safety poses a significant risk to Meta, including recent lawsuits and fines. This illustrates how shareholders can use proposals to raise material risks to companies. We shouldn’t make it harder for shareholders to do so.
Shareholder proposals also are a useful tool for State Treasurers to lead constructive and collaborative dialogue with companies. A couple years ago, we filed shareholder proposals at Southwest & American Airlines over health and safety concerns among their employees and contracted employees, including heat stress for workers on the tarmac. The airlines made commitments, and we withdrew the shareholder proposals.
Since then, we have continued to work with both companies to enhance their disclosure on health and safety, including providing input on their annual sustainability reporting and what would be most helpful for the companies to disclose. One of the companies committed to obtaining an Operational Safety audit when we withdrew the proposal and has since then obtained it. That’s an important step towards keeping employees safe.
This SEC proposal to do away with a rule that has worked since 1942 is part of the Trump administration’s continuing demolition of guard rails. We have seen time and again Trump gutting the rules to put money in the pockets of his family and his cronies. The president is enriching the Trump family over the interest of all Americans. Watering down financial regulations makes it easier for companies to put profits over people.
The SEC should not make its limitations to the 14a-8 process permanent or eliminate its shareholder proposal framework. I am calling on the SEC to protect retirees, pension beneficiaries, individual investors and families saving for their child’s college education by keeping the rules in place.
The SEC’s comment period is currently scheduled to close on November 20, 2026. Submit a comment urging the Commission to preserve Rule 14a-8.
SEC Quorum Rule: A Commission of One, Adopted Without Public Comment
James McRitchie, 09/30/2026
On September 30, 2026, the SEC changed who gets to decide things at the SEC. It did not propose the change. It didn’t ask for comments. It simply adopted a final rule, effective on publication, that lets a single Commissioner act as the entire Commission whenever every other Commissioner is disqualified from a matter.
Congress created a five-member, bipartisan Commission. The SEC has now decided, on its own and without public input, that one person can be enough.
In California, where I once headed rulemaking at a state agency, we called rules adopted without going through the required process “underground regulations.” The federal version has a different name, but the problem is the same: the public was shut out of a decision that affects everyone the SEC regulates.
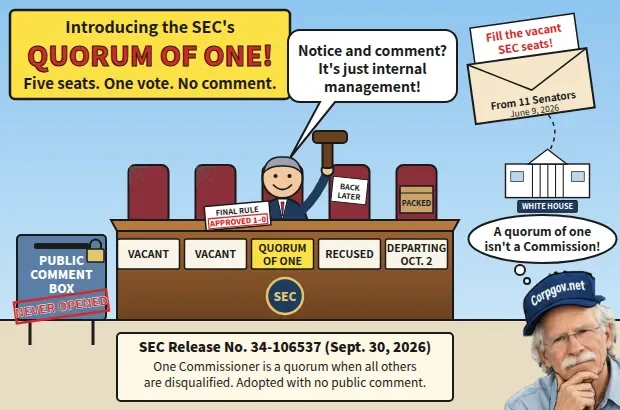
A Quorum of One – and Music for a Democratic Corporate Governance
What the SEC Did
The amendment (Release No. 34-106537) rewrites 17 CFR 200.41, the Commission’s quorum rule. Since 1995, three Commissioners have made a quorum. If fewer were in office, the number in office did. If disqualifications left two able to act, two could. But in 1995, the Commission expressly declined to go further, saying it did not believe it necessary to let one Commissioner constitute a quorum.
The new rule does exactly that. And the stated purpose is not internal housekeeping. The release says the amendment is “designed to promote flexibility and finality of agency rulemaking.”
Yet the SEC skipped notice and comment by calling it a rule of “agency management and organization” that does “not substantially affect the rights or obligations of non-agency parties.” A rule designed to make it easier to finalize rules that bind investors, companies, and markets does not fit that description.
Why the Timing Matters
No Democratic Commissioner has served since early 2026.
Two seats have remained vacant, although nothing prevents the President from nominating, and the Senate from confirming, Democrats to fill them.
Commissioner Hester Peirce has reportedly announced her departure effective October 2, 2026, two days after this rule was adopted.
If no successor is confirmed, two Commissioners will remain, both of the same party. Under the new rule, whenever one is disqualified, the other can act alone for the Commission.
I do not assume how any Commissioner would use this power. The problem is structural. Powers Congress gave to a bipartisan commission could be exercised by one person.
A Quorum of One Is Not a Commission
A quorum is the minimum number of members needed for a body to act. It is plural by definition. One person cannot deliberate with himself.
The D.C. Circuit upheld the SEC’s existing rule in Falcon Trading Group v. SEC (1996), when only two Commissioners were in office. But the court relied on the common-law rule that “a majority of a quorum constituted of a simple majority of a collective body” may act. One Commissioner ia not a simple majority or two and one acting alone is not a collective body. Falcon does not bless this.
Even the Commissioners Say Bipartisanship Matters
On June 9, 2026, Senators Raphael Warnock and Chris Van Hollen, joined by Banking Committee Ranking Member Elizabeth Warren and eight other Democratic senators, wrote to the White House urging it to fill the vacant seats. “A full slate of commissioners and board members can bring a range of perspectives to policies that shape our markets,” they wrote. “No practical barrier prevents the President from next appointing a Democrat to the SEC.” They noted Chairman Atkins has said he is “supportive of having a full complement of commissioners, as it helps with debates and everything else.”
Commissioners themselves have said the same:
Commissioner Mark Uyeda (2022): “The Commission is structurally designed to promote regulation that is the product of consideration by five individuals with different perspectives.”
Commissioner Daniel Gallagher (2013): “Congress created the SEC as a bipartisan, five-member Commission and gave each Commissioner — including the Chairman — only one vote.”
Commissioners Peirce, Crenshaw, and Uyeda, jointly (2025): “Although as Commissioners we approached policy issues from different perspectives, there was always dignity in our differences.”
A quorum of one eliminates the different perspectives they valued.
What’s at Stake for Shareholders
The SEC has proposed rescinding Rule 14a-8, ending the federal requirement that companies include qualifying shareholder proposals in their proxy statements, a right investors have relied on since 1942. Under the new quorum rule, a final rule of that consequence could be adopted by a single Commissioner if the others were disqualified.
Rules that reverse decades of settled policy are exactly where deliberation matters most. A major rule adopted by one Commissioner, or by members of one party alone, may also be more vulnerable to challenge and to reversal by a future Commission. That undercuts the very “finality” the SEC says it wants.
The answer to vacancies is to fill them. It is not to redefine the Commission so that one member can act for all five.
Media Coverage
What I’ve Done, and What You Can Do
Because the SEC didn’t open a comment period, I filed a petition for rulemaking under Rule 192 of the SEC’s Rules of Practice, asking the Commission to rescind the amendment, or at a minimum, suspend it and put it out for public comment. You can read it here: [Comment on Release No. 34-106537]. I also filed a copy in the Rule 14a-8 rescission file (S7-2026-32), because the quorum rule bears directly on who may adopt a final rule there.
My petition also asks the SEC to:
limit any single-member authority to ministerial or time-critical matters, excluding rulemaking, enforcement authorizations, and contested adjudications;
define “otherwise disqualified” and publicly disclose every disqualification that produces a one- or two-member quorum; and
defer final action on major rulemakings, including the Rule 14a-8 rescission, until the Commission has at least three members, including at least one not of the majority party.
You can help:
Support the petition. Once the SEC posts it on its petitions page, file a comment. Until then, email your views to rule-comments@sec.gov, referencing Release No. 34-106537.
Raise it in the Rule 14a-8 file. If you’re commenting on the proposed rescission (S7-2026-32, due November 20), ask the SEC not to finalize it with fewer than three Commissioners.
Contact the Senate Banking Committee. Call (202) 224-7391 and tell them you support their call to fill the vacant seats, which both Republicans and Democrats supported in their letter of June 9, 2026.
The SEC’s legitimacy rests on the deliberation Congress built into it. A Commission of one isn’t what Congress designed, and it isn’t what investors deserve.
Sources
SEC, Commission Quorum Requirement, Release No. 34-106537 (Sept. 30, 2026).
SEC, Establishment of Commission Quorum Requirement, Release No. 34-35548 (1995).
Letter from Sens. Warnock, Van Hollen, et al. (June 9, 2026).
Falcon Trading Group v. SEC, 102 F.3d 579 (D.C. Cir. 1996).
Commissioner Uyeda, SEC Speaks remarks (Sept. 9, 2022); Commissioner Gallagher, remarks (Feb. 22, 2013); Statement of Commissioners Peirce, Crenshaw, and Uyeda (Jan. 20, 2025).
Holland & Knight, “Low Tide at the SEC: From Five Commissioners to Two” (July 2026).
The Investors Weigh In on Rescinding Rule 14a-8
Dave Lynn, September 23, 2026
The SEC’s proposal to rescind Rule 14a-8 prompted a swift response from the Council of Institutional Investors (CII). On the same day that the proposal was issued, CII Executive Director Glenn Davis issued a statement, bluntly noting:
Let this moment settle in: The SEC, created for the purpose of protecting investors in the aftermath of the Crash of 1929, today proposed to rescind a World War II-era rule protecting shareholders’ ability to suggest ideas to improve the companies they own.
Yes, shareholder proposals can be a source of embarrassment when they reveal a disconnect between shareholders’ and managers’ understandings of what matters to long-term performance; and sometimes they trigger compromise before a vote takes place. That is a feature of strong capital markets, not a basis for a government agency to swat a fly with a sledgehammer.
The proposed rescission is a solution in search of a problem. Nearly all shareholder proposals are non-binding, which means they merely give corporate directors data to make better-informed decisions. Company costs related to shareholder proposals trace largely to self-imposed expenses such as pursuing legal cover to exclude proposals from ballots or funding campaigns to get out the “against” votes. Most publicly traded companies face zero shareholder proposals in a given year.
Could Rule 14a-8 be improved? Sure. But the SEC proposed rescinding the rule in its entirety, with fingers crossed that state legislators and corporate directors will develop a patchwork of new rules resulting in something better. Spoiler alert: That patchwork will launch a new race to the bottom in state corporate law and result in a dramatic reduction in shareholders who qualify as proponents, notwithstanding smaller investors’ history of putting forward many of the most highly supported proposals.
CII will speak publicly and repeatedly to defend Rule 14a-8. We encourage all market participants to do their part in this effort. It’s not about whether you agree or disagree with the substance of particular shareholder proposals. It’s about preserving broad shareholder expression as a vital part of robust capital markets.
Meanwhile, the comments are already starting to pour in on the SEC’s proposal. Trillium Asset Management, LLC submitted a comment letter this week requesting that the Commission extend the public comment period from 60 days to 120 days, while asking the Commission to convene a public roundtable “to gather the views of investors before proceeding further.” These requests were subsequently echoed in a comment letter submitted by the Committee on Mission Responsibility Through Investment, part of Presbyterian Life & Witness, an agency of the General Assembly of the Presbyterian Church.
SEC Proposal to Move Proxy Oversight to States Comes Under Industry Scrutiny
Matt Toledo, September 17, 2026
According to the Securities and Exchange Commission, Rule 14a-8 exceeds the SEC’s authority, but opponents said the SEC’s proposal takes a ‘sledgehammer’ to shareholder proposals.
The Securities and Exchange Commission announced Wednesday a proposal to rescind Rule 14a-8 under the Securities Exchange Act of 1934. The proposal would eliminate SEC oversight of shareholder proposals in public companies’ proxy materials for vote by shareholders and would “leave determinations about the role of shareholder proposals to state law and company governing documents,” according to the SEC’s release.
“Many of the justifications for adopting the rule either have not been substantiated in practice or are less compelling today, and the rule has had unintended consequences, including the implication of federal preemption that may have discouraged states from developing their own laws governing shareholder proposals,” the SEC stated.
Additionally, the SEC proposed amendments to Rule 14a-4(c) in an effort to modernize the proxy solicitation process. These amendments, according to the SEC, would:
Eliminate the requirement that companies deliver an annual report to security holders;
Eliminate the delivery deadline when documents are incorporated into a proxy statement;
Eliminate the requirement and the ability to submit notices of exempt solicitation; and
Shorten the minimum broker search period to five business days from 20.
“The proposed rescission of Rule 14a-8 would, if adopted, eliminate the federal rule regulating inclusion of shareholder proposals in a company’s proxy materials for vote by the company’s shareholders,” said SEC chair Paul Atkins in a statement. “To be clear, the proposed rescission would not eliminate the concept of shareholder proposals and is not an attempt by the Commission to silence shareholders. Rather, it is a recognition that the Commission must act within its authority.”
Targeting Shareholder Voting
Atkins, in his statement, said of the proposal’s timing that, coming during a period “of increased competition among states for corporate domicile, there is no better time for the Commission to recognize the limits of its authority, relative to state law, for regulating shareholder proposals. Competition has always been the engine for innovation and progress in America. As part of states’ efforts to attract companies, the proposed rescission of Rule 14a-8 should, if adopted, provide states with both the legal clarity and the motivation to implement their own ideas for a sensible shareholder proposal framework.”
The SEC proposal comes as President Donald Trump has focused on changing the shareholder voting process, specifically by limiting the role of proxy advisory firms, most notably by a December 2025 executive order. Trump named the two largest proxy advisers, Institutional Shareholder Services Inc. and Glass, Lewis & Co. LLC, and said they “wield enormous influence over corporate governance matters, including shareholder proposals, board composition, and executive compensation, as well as capital markets and the value of Americans’ investments more generally, including 401(k)s, IRAs, and other retirement investment vehicles.”
Trump’s order directed the SEC chair to “consider revising or rescinding those rules, regulations, guidance, bulletins, and memoranda that are inconsistent with the purpose of this order”; to review proxy advisers’ work for violations of the anti-fraud provisions of federal securities laws; and to screen their work overall for other potential violations of federal law.
Institutional Shareholder Services is part of ISS STOXX, which owns CIO.
A report from law firm Akim Gump Strauss Hauer & Feld LLP noted that the recission of rule 14a-8 would remove the lowest-cost channel for placing proposals in front of shareholders, resulting in institutional investors having to develop more resource-intensive and less certain methods to distribute shareholder proposals.
Some companies have moved their official domicile to benefit from less stringent governance standards, including proxy rules. Space Exploration Technologies Corp.—SpaceX—was criticized by institutional investors for moving to Texas from Delaware in 2024, because corporate laws in Texas make it more difficult for investors to initiate shareholder proposals. SpaceX’s move came after a Delaware Court of Chancery ruling that ordered Tesla to rescind Elon Musk’s 2018 CEO pay package, worth about $56 billion in options.
Industry Reactions
The California Public Employees’ Retirement System was critical of the SEC’s proposal. James Scullary, a spokesman for the system that managed $637.1 billion in pension assets as of June 30, says the fund views Rule 14a-8 “as a critical component of company-shareholder engagement.”
“The SEC’s proposal to rescind the rule directly harms the fundamental rights of shareholders and limits our ability to engage constructively and advocate for policies that positively influence long-term share value,” Scullary says.”For decades, the federal proxy process has been a vital, standardized mechanism for investors to raise material risks and hold corporate boards accountable. Dismantling this framework doesn’t modernize our markets; it simply silences the actual owners of these companies. In addition, by abandoning a unified federal standard and kicking the shareholder proposal process down to a patchwork of 50 state laws and individual corporate bylaws, the SEC is introducing inefficiencies and potential legal issues into U.S. capital markets.”
Glenn Davis, executive director of the Council of Institutional Investors, responded to the SEC proposal, saying “Yes, shareholder proposals can be a source of embarrassment when they reveal a disconnect between shareholders’ and managers’ understandings of what matters to long-term performance; and sometimes trigger compromise before a vote takes place. That is a feature of strong capital markets, not a basis for a government agency to swat a fly with a sledgehammer.”
The Interfaith Center on Corporate Responsibility, in a statement, referred to the proposed rescinding of 14a-8 as an “all hands-on-deck” moment for investors, while also describing the move as an attack on the fundamental rights of shareholders and on decades of precedent that have facilitated engagement between investors and companies.
“Investors focused on safeguarding the long-term value of their holdings have benefited from the shareholder engagement process as a key instrument for constructive dialogue between shareholders and executives for over 50 years,” ICCR CEO Josh Zinner said in a statement. “These engagements have led to many commonplace improvements in corporate risk mitigation and governance policies now considered best practices in a wide range of industries.”
Proponents of the SEC proposal said the shareholder proposal process has been hijacked by investors with a political agenda—generally referring to institutional asset owners and funds that have made environmental, social and governance factors a major focus of their shareholder proposals.
“The SEC’s previous proxy rules allowed political activists to hijack the proxy system at the expense of everyday investors,” said Chris Iacovella, president and CEO of the American Securities Association. “ASA applauds Chairman Atkins for ending the use of SEC resources to referee political disputes and redirecting them toward the agency’s core mission of protecting investors from fraud.”
The U.S. Chamber of Commerce, a trade association, also welcomed the SEC proposal. Mike Flood, senior vice president of the chamber’s Center for Capital Markets Competitiveness, said, “For too long, special interests have exploited Rule 14a-8 to advance their own agendas at the expense of public companies and their shareholders. We commend the SEC for seeking a long-term solution to this problem and for its ongoing work to encourage more businesses to go public.”
Microsoft commits to continue fielding shareholder proposals through 2027 AGM
Jack Grogan-Fenn, 5 September 2026
As the SEC considers dismantling the federal shareholder proposal framework, Microsoft has moved early to reassure investors that access rights will remain for at least its next two annual meetings.
Technology giant Microsoft has agreed to continue accepting shareholder proposals under existing ownership thresholds through its 2027 annual meeting, becoming one of the first major US issuers to publicly commit to preserving shareholder proposal access following the US Securities and Exchange Commission (SEC) proposal to rescind Rule 14a-8.
The agreement comes as investors increasingly seek clarity from individual companies on how they would handle shareholder proposals if the federal framework were removed. By putting its position in writing ahead of a final SEC decision, Microsoft has provided an early indication of how issuers may respond and established a potential reference point for investors engaging with other companies.
Microsoft moves to preserve existing proposal thresholds
The National Legal and Policy Center (NLPC) announced on 22 September that it had secured an agreement with Microsoft under which the company will continue applying the current ownership thresholds for shareholder proposals through its 2027 AGM. Microsoft’s 2026 AGM is set to take place on 8 December, with the company yet to publish its proxy materials.
“Microsoft put in writing that the smallest long-term owners of the company will still have a way to be heard next year, no matter what the SEC does,” said Paul Chesser, Director at the NLPC. “Every other company that claims to value its shareholders should be asked why it won’t do the same.”
The agreement follows the SEC's proposal to rescind Rule 14a-8, amend Rule 14a-4 and “modernise” the proxy solicitation process. The proposals would remove the federal mechanism that currently allows eligible shareholders to place resolutions before fellow investors through company proxy materials.
Against that backdrop, the NLPC submitted proposals to a number of companies, including Microsoft, seeking commitments to maintain access for proponents meeting the existing ownership thresholds of US$2,000 held for three years, US$15,000 for two years or US$25,000 for one year. Following discussions with the company, the Microsoft proposal was withdrawn. The first proposal in the campaign to proceed to a shareholder vote is set to be considered at consumer goods company Procter & Gamble's AGM on 13 October.
While debate over Rule 14a-8 has largely focused on regulators, Microsoft's decision is significant because it moves the discussion towards corporate policy. Rather than waiting for a final regulatory outcome, the company has chosen to state publicly how it intends to approach shareholder access in the near term.
Attention shifts from regulators to companies
The question now facing investors is whether other issuers will make similar commitments.
Under the current system, companies must include procedurally compliant shareholder proposals in proxy materials ahead of annual meetings. If Rule 14a-8 is rescinded, companies would have significantly greater discretion over whether, and on what terms, shareholders can submit resolutions for consideration by fellow investors.
Evidence that attention is already shifting towards companies can be seen elsewhere in the debate. Shareholder advocate Jim McRitchie has called on Costco to submit a comment letter opposing the SEC's proposal, arguing that the retailer has historically benefited from the shareholder proposal process and warning that rescinding the rule would replace a single federal standard with company-by-company uncertainty. He also suggested that investors are likely to remember how companies position themselves as the debate unfolds.
Similarly, Zevin Asset Management wrote to Costco urging the company to “actively protect corporate governance best practices and capital markets integrity related to Rule 14a-8”. The investor also warned that weakening or rescinding Rule 14a-8 would “disrupt an established, low-cost dialogue and lead to significant unintended consequences for public companies”.
Against that backdrop, Microsoft's agreement provides one of the earliest examples of an issuer making an explicit commitment before regulators have reached a final decision. For investors seeking assurances that shareholder proposal rights will continue, it may become an important benchmark when engaging with other companies.
Support for shareholder proposals spans ideological divides
The agreement is notable not only because of the company involved, but also because the initiative originated with the NLPC, an organisation best known for its criticism of ESG and diversity-related initiatives.
That dynamic reinforces a broader theme emerging from the Rule 14a-8 debate. Concerns about preserving shareholder access are increasingly being expressed across different parts of the investor and policy landscape.
“The recent report noting Microsoft has come to an agreement with a conservative investor advocate to allow shareholder proposals to continue to be filed is an example of good governance by the company,” Smith, Senior Policy Advisor at the Interfaith Center on Corporate Responsibility, told Minerva Analytics. “Investors and companies alike are facing a huge vacuum if the SEC rescinds Rule 14a-8. Since the SEC announcement, many investors have discussed urging companies to develop their own policies to allow resolutions to be filed going forward.”
Smith added that removing the shareholder proposal mechanism may leave investors increasingly reliant on alternatives such as litigation and vote campaigns to raise concerns. Sanford Lewis, Director and Founder of the Shareholder Rights Group, likewise described Microsoft's decision as a positive governance step and expressed hope that other companies will adopt similar approaches.
The breadth of opposition to rescinding Rule 14a-8 has become increasingly apparent. Representatives of pension funds in both Republican- and Democrat-led states have raised concerns about the proposal, while voices from across the political spectrum, including the Heritage Foundation and Bowyer Research, have highlighted potential risks associated with dismantling the existing framework.
What happens if the SEC rescinds Rule 14a-8?
Whether other companies choose to make similar commitments remains unclear. However, Microsoft's agreement provides one of the first tangible signs that issuers are beginning to plan for a post-Rule 14a-8 environment.
The significance of the development lies less in its immediate impact on Microsoft than in what it may signal for the wider market. If the SEC ultimately removes the federal shareholder proposal framework, investors are likely to focus increasingly on company-level policies and commitments. Microsoft has moved early to set out its position. The next question is whether other issuers decide to do the same.
SEC Move Would Make it Harder for Shareholders to Push Companies on Climate Action
Dimuthu Attanayake, October 3, 2026
Shareholder proposals aren’t legally binding. But companies can feel pressure to take them seriously.
The U.S. Securities and Exchange Commission wants to scrap a rule that allows shareholders to formally petition companies, one of the ways that shareholder advocacy groups have pressed for more action on climate and sustainability.
Investor and advocacy groups warn that the SEC’s move would block a longstanding avenue for pressuring public companies to factor in climate risks that could severely impact their operations.
For instance, investors have used the rule to persuade companies to be more transparent on their emission targets and to better account for other environmental impacts. In 2022, nearly two-thirds of Home Depot shareholders backed a proposal on deforestation in its supply chains. Home Depot commissioned a third-party assessment and released a report in 2024.
“Taking away the right of shareholders to petition companies about climate change really is taking away another tool … not only from investors, but also from the public, to address the climate issue,” said Timothy Smith, senior policy advisor at the Interfaith Center on Corporate Responsibility, a coalition of faith- and values-based investors.
Shareholders Push Companies to Help Retain Proxy Proposal Rights
Drew Hutchinson, Oct 2nd
While the SEC pursues an end to mandatory votes on corporate shareholder proposals, investor advocates are pushing companies themselves to step in and help preserve existing rights.
The burgeoning pressure on companies ranging from Microsoft Corp. to Oracle Corp. comes as the Securities and Exchange Commission seeks to repeal an 84-year-old regulation compelling companies to hold annual votes on shareholder resolutions. States will have the option to fill a regulatory gap if the rule goes through, but in the meantime, stockholders are going straight to the source.
Independent shareholder advocate James McRitchie wrote to Costco Wholesale Corp. last week asking the company to oppose the SEC’s plans in public comments, according to an email seen by Bloomberg Law.
Similarly, investment firm Zevin Asset Management contacted its 30 portfolio companies mid-September urging them to speak out publicly against the proposal, express concerns to the agency’s commissioners, and maintain the status quo, according to sustainable investing director Marcela Pinilla. Meanwhile, the New York State and New York City comptrollers’ offices also called on every publicly traded company to keep accepting the proposals.
Other campaigns began earlier. Noting SEC leaders’ increasing condemnation of the proposal process, the National Legal and Policy Center’s shareholder arm submitted resolutions earlier in the year at a half-dozen companies. One was withdrawn after Microsoft agreed in August to keep accepting proposals that meet existing stock ownership requirements for one year, regardless of what the agency does. Two similar proposals will see a vote Oct. 13 at Procter & Gamble Co. and Nov. 18 at Oracle.
Shareholder proposals can address anything from board practices to diversity, equity, and inclusion. Companies saw an increase in environmental and social justice proposals in the early 2020s following the death of George Floyd, but that trend has since dropped off. In the 2026 proxy season, governance proposals — which ask for measures like independent board directors or certain shareholder rights — were king.
Shareholders see Rule 14a-8, the regulation in question, as a civil, productive way to put key issues in front of companies. Hedge funds have the clout to call up CEOs, but smaller proponents rely on the rule for access, said Paul Chesser, director of the NLPC’s Corporate Integrity Project.
“There’s relatively few of us,” he said. “They don’t have to deal with a lot.”
Divergence Likely
Chesser’s organization has holdings in a couple dozen more companies where it could submit proposals before next spring’s proxy season, when most large companies hold their annual meetings. Future resolutions would probably focus on preserving more aspects of the current federal rule, not just the minimum stock ownership requirements it pursued at Microsoft and Oracle, he said.
Whether companies will embrace shareholders’ pleas for action is up in the air. After asking Costco to submit comments to the SEC opposing the rollback, McRitchie received a response from the company’s general counsel, John Sullivan, according to an email seen by Bloomberg Law: “Thanks for the feedback. We are evaluating the SEC proposal and your comments.”
“The near term is just going to be a lot of issuers taking different paths,” said Brent Trame, partner at Thompson Coburn LLP.
Ultimately, companies will probably keep including at least some shareholder proposals if the existing rule vanishes, said Frank Zarb, partner at Proskauer Rose LLP.
Companies already got a taste of the shareholder proposal process without the SEC. The agency decided last November to stop settling disputes between shareholders and companies about which proposals were required to go to a vote — a policy it said it will continue until further notice. Some businesses operated during the 2026 proxy season as they had in every other year, while others seemed more comfortable excluding resolutions, said Timothy Smith, senior policy adviser at shareholder group Interfaith Center on Corporate Responsibility. It will be the same disparity if Rule 14a-8 disappears, he said.
States Take Spotlight
The SEC views state legislatures and courts as the proper venues to handle shareholder proposal rules, an agency spokesperson said in a recent press briefing.
What states do will also dictate how companies function going forward. Some states could create a mandatory shareholder proposal process, while others could let companies opt in — in which case some would and others wouldn’t, said Benjamin Edwards, a law professor at the University of Nevada, Las Vegas.
Two-thirds of Fortune 500 companies are incorporated in Delaware. But SEC Chairman Paul Atkins has questioned whether the state’s laws guarantee the right to non-binding shareholder proposals, and even invited companies before last proxy season to get a Delaware legal opinion stating so. No one took him up on it.
Delaware’s Corporate Law Council, which advises the general assembly on business code updates, has been studying and deliberating the implications of threats to Rule 14a-8 for months, Secretary of State Charuni Patibanda-Sanchez said in an emailed statement.
“Given Delaware’s expertise in corporate governance, we are the best jurisdiction able to propose a solution that meets the needs of the market,” she said.
The best shareholder proposal framework for companies is sort of like wine, Edwards said: “What is a better fit for one company and their situation may not be a better fit for another.”

Shareholder Proposals as an Early Warning System for Corporate Risk, and the Cost of Ignoring Them
Posted by Timothy Smith and Sehr Khaliq, Interfaith Center on Corporate Responsibility, on October 8, 2026
Much has been written about the significance of the $5 billion historic penalty and privacy reforms imposed by the FTC on Meta, but press surrounding the incident rarely references the fact that this risk was something shareholders had already warned management about through shareholder filings.
In 2018, shareholders filed a proposal at Meta asking the company to issue a report discussing the merits of establishing a Risk Oversight Board Committee to address privacy/data risks that could threaten shareholder value. The Board opposed the proposal, arguing that the Board’s audit committee offered sufficient oversight. Since Meta is a dual class share company with CEO Mark Zuckerberg owning 99.7% of the outstanding Class B shares that represent only 13% of the economic ownership but grant him 61% of the voting power, the proposal got only 11.55% of the vote, which represented 45% support among non-insider shares.
However, the very next year the FTC fined the company $5 billion and required it to establish an independent privacy committee with unfettered control over decisions affecting user privacy. The order required the company to designate compliance officers who will be responsible for Facebook’s privacy program and will report to the new Board privacy committee and can be removed only by that committee. In an ironic twist the FTC order enhanced the demands of the 2018 shareholder proposal but with a $5 billion fine attached. This was not even the first case of a company being fined or being forced to pay damages in billions of dollars on an issue that shareholder proponents had asked them to consider – we’ve had multiple this year alone!
On July 27th, 2026 it was announced that Johnson and Johnson would pay $5.5 billion to settle talcum powder-related cancer lawsuits. In 2022, shareholders had filed a resolution asking J&J to discontinue global sales of its talc-based baby powder, citing cancer litigation, asbestos concerns and growing financial risk, but management had dismissed their concerns about its talcum powder arguing that “decades of science have reaffirmed its safety” and that the company had taken adequate measures against litigation. With the Board opposing the proposal it received only 15.6% of the vote. Now the settlement may cost the company and shareholders $7 billion depending on participation. But even that is not the largest settlement this year.
In February 2026 Monsanto announced a Roundup™ class settlement agreement to resolve current and future claims for up to $7.25 billion. Shareholders had repeatedly asked Monsanto to report on the risks associated with glyphosate (including in 2015, 2016, and 2018) but the Board had opposed the proposals each time arguing that “the purported harms suggested in the proposal are simply unsubstantiated and unproven assertions improperly characterized as risks”, thus the requested risk analysis was speculative and unnecessary.
The largest settlement in 2026 (to date) came in August when Meta announced it would be paying $18 billion to settle U.S. lawsuits over children’s social media addiction. The settlement represents 9% of the company’s annual revenue and follows $2.4 billion in legal-proceeding charges recorded during the second quarter, when total costs and expenses increased 55% to $42.03 billion.
Shareholders had repeatedly filed shareholder proposals asking the company to address risks related to child safety online since 2020. In 2020 a proposal asked the company to publish a report to address potential adverse impacts to children (18 years and younger) and to the company’s reputation or social license, and assess the impact of limits to detection technologies and strategies. The Board opposed the proposal arguing that it was “unnecessary and not beneficial to our stockholders”. The proposal got 12.4% of the vote. Shareholders refiled the proposal in 2022 and despite Board opposition it got 56.7% of the independent vote (because of the company’s dual class share structure the actual vote was 17.3%). The same year, Meta was fined $400 million for failing to safeguard children’s information on Instagram. Shareholders continued to file on the issue with the company in 2023, 2024 and 2025 but each time the Board opposed the ask, and the dual class share voting structure obstructed the voice of independent shareholders. Could being more responsive to these shareholder proposals have saved the company and shareholders, not to mention the victims, from harm? We will never know, but those arguing about the costs and benefits of shareholder proposals need to consider the value of these shareholder proposals as an early warning system that when unheeded causes real harm to people, planet, shareholders and the bottom line.
These examples (captured in the table below) cost the 3 companies involved, and their shareholders, over $30 billion in damages and fines this year alone – a representation of the very real cost of ignoring shareholder proposals. And these examples are simply recent illustrations of investors raising important and material issues with Boards and management that get easily dismissed but build as issues of public importance, resulting in costly penalties and settlements. They are a reminder of the value of shareholder resolutions as an early warning system identifying material corporate risks, which seek to preserve shareholder value and deserve more thorough scrutiny by Boards.
| Company/ Risk | Shareholder proposal(s) / warning | Board response to proposal(s) | Financial consequence recorded in 2026 |
|---|---|---|---|
| Johnson & Johnson – product safety | 2022: Shareholders asked J&J to discontinue global sales of talc-based Baby Powder, citing cancer litigation, asbestos concerns and growing financial risk. | OPPOSED. J&J said its talc was safe, and that existing litigation/risk-management processes were adequate. | ~$5.5B proposed settlement in 2026, with potential total exceeding $7B depending on participation. |
| Monsanto/ Bayer – Glyphosate/ human-health & regulatory risk | 2015–18: Shareholders repeatedly asked Monsanto to report on the risks associated with glyphosate (2015, 2016, 2018) including the potential financial consequences of restrictions following its classification by IARC/WHO as “probably carcinogenic.” | OPPOSED. Monsanto said glyphosate had a 40-year safety record; that regulatory authorities had repeatedly found it safe, and that the requested risk analysis was speculative and unnecessary. Bayer acquired Monsanto in 2018 and inherited the Roundup litigation. | $7.25B proposed nationwide Roundup settlement in 2026; earlier settlements and judgments added billions more. |
| Facebook/ Meta – Child Safety Online | Shareholders repeatedly asked the company to address risks related to child safety online including in 2020, 2021, 2022, 2023, 2024 and 2025 | OPPOSED. The Board argued that the shareholder proposals were “unnecessary and not beneficial to our stockholders”. Despite Board opposition, the 2022 filing got majority support from independent shareholders with 56.7% of the independent vote (because of dual class share the actual vote was 17.3%) | $18 billion to settle US lawsuits over children's social media addiction in 2026. |
Statement by CII Executive Director Glenn Davis on the SEC’s Proposed Rescission of Rule 14a-8
Washington, D.C., Sept. 16, 2026
Let this moment settle in: The SEC, created for the purpose of protecting investors in the aftermath of the Crash of 1929, today proposed to rescind a World War II-era rule protecting shareholders' ability to suggest ideas to improve the companies they own.
Yes, shareholder proposals can be a source of embarrassment when they reveal a disconnect between shareholders' and managers' understandings of what matters to long-term performance; and sometimes they trigger compromise before a vote takes place. That is a feature of strong capital markets, not a basis for a government agency to swat a fly with a sledgehammer.
The proposed rescission is a solution in search of a problem. Nearly all shareholder proposals are non-binding, which means they merely give corporate directors data to make better-informed decisions. Company costs related to shareholder proposals trace largely to self-imposed expenses such as pursuing legal cover to exclude proposals from ballots or funding campaigns to get out the "against" votes. Most publicly traded companies face zero shareholder proposals in a given year.
Could Rule 14a-8 be improved? Sure. But the SEC proposed rescinding the rule in its entirety, with fingers crossed that state legislators and corporate directors will develop a patchwork of new rules resulting in something better. Spoiler alert: That patchwork will launch a new race to the bottom in state corporate law and result in a dramatic reduction in shareholders who qualify as proponents, notwithstanding smaller investors' history of putting forward many of the most highly supported proposals.
CII will speak publicly and repeatedly to defend Rule 14a-8. We encourage all market participants to do their part in this effort. It's not about whether you agree or disagree with the substance of particular shareholder proposals. It's about preserving broad shareholder expression as a vital part of robust capital markets.
NYS Comptroller DiNapoli and NYC Comptroller Levine Statement on SEC’s Plan to Silence Shareholders of Public Companies
September 24, 2026
New York State Comptroller Thomas P. DiNapoli and New York City Comptroller Mark Levine today issued a joint statement opposing the Securities and Exchange Commission's proposal to rescind Rule 14a-8 and encouraging companies to support shareholders ability to file proposals. Since 1942, the rule has required publicly traded companies to include qualifying shareholder proposals in their proxy materials so that all investors can vote on them. Without it, companies could exclude shareholder proposals from the proxy ballot altogether, leaving investors to bear the cost of a separate proxy solicitation just to put a question before their fellow shareholders. Their statement:
“We are disappointed to see the SEC proposing to rescind Rule 14a-8.
“Any SEC action to rescind or fundamentally alter Rule 14a-8 will likely face lengthy legal challenges. We expect—as a matter of good corporate governance—that publicly traded American companies will continue accepting shareholder proposals for publication in their proxy for the 2027 season and adhering to the status quo during this period of regulatory uncertainty.
“The shareholder proposal process is a cornerstone of American corporate governance that has strengthened board oversight, improved risk management, and fostered productive dialogue between investors and companies for more than 80 years. Companies should not use the shield of regulatory uncertainty to undermine the important and constructive role investors play in making companies better.”
Rulemaking Petition-Factsheet
Formal Petition Regarding Amendments to Rule 14a-8
Under the Securities Exchange Act of 1934, Filed with the U.S. Securities and Exchange Commission, July 23, 2026
WHAT THE PETITION REQUESTS
The petition is filed under an SEC rule that invites shareholders to recommend changes to an SEC rule. The Petition asks that, if the SEC conducts a rulemaking on Rule 14a-8, it recalibrate rather than dismantle the rule. If the Commission proceeds with rulemaking, the petition reminds the SEC of its obligation under the Administrative Procedure Act to rigorously evaluate less harmful alternatives before any wholesale change.
NO ACTION PROCESS RECOMMENDATIONS
The no-action process be retained with reforms to sharpen the review process machinery—clarifying timelines, promoting direct engagement between issuers and proponents, and thereby reducing unnecessary demands on Commission staff:
establish a two-week engagement period after an issuer submits a notice of intent to exclude a shareholder proposal, during which the issuer and proponent may seek an agreement that potentially eliminates the need for a staff advisory opinion
provide specific timeframes for proponents to respond to exclusion notices, and confirm that the staff will consider any timely proponent response when issuing an advisory opinion;
extend the deadline for filing exclusion notices from 80 to 90 days, and clarify that the deadline runs from the earlier of the issuer’s proxy print deadline or its EDGAR filing deadline for the definitive Form DEF 14A; and
Set clear timeframes for a proponent to respond if a company requests a staff advisory opinion.
Allow 14 business days for responses to procedural objections such as proof of ownership, and 30 calendar days for responses to substantive exclusions
Eliminate outdated paper copy submission requirements.
Excise obsolete language in the existing Rule requiring the submission of six paper copies, reflecting the modern reality that all submissions are processed electronically.
RECOMMENDATIONS ON EVALUATING LESS HARMFUL ALTERNATIVES
In the event that the SEC proposes reforms to the shareholder proposal rule beyond the no action process, the petition reminds the SEC of its obligation to consider less harmful alternatives that would do less to disrupt the expectations and systems that the market has come to rely upon. Such less harmful alternatives could include retaining the federal framework while leaving dispute resolution to the courts and evaluating the related cost of litigation that this approach would impose. Such evaluation would also consider approaches for reducing the subjectivity of the rules to reduce disputes between proponents and issuers.
Signatories of the petition
The signatories include New York State Comptroller Thomas P. DiNapoli and organizations: Ceres, For the Long-Term, the Interfaith Center on Corporate Responsibility, Shareholder Rights Group, and US SIF
Rulemaking Petition regarding Amendments to Rule 14a-8 Under the Securities Exchange Act of 1934
July 23, 2026
Vanessa A. Countryman, Secretary
U.S. Securities and Exchange Commission
100 F Street, NE, Washington, DC 20549-1090
I. Introduction
The undersigned submit the following pursuant to 17 CFR § 201.192(a) (Rule 192(a) of the Commission’s Rules of Practice) and Section 553 of the Administrative Procedure Act.
Petitioners request that the Commission, in any rulemaking to amend Rule 14a-8 under the Securities Exchange Act of 1934 (“the Rule”), largely retain the Rule, which has, over the course of many decades established and refined a balance among issuers, proponents, and the voting shareholders whose capital is at stake.
The petition addresses both the no-action process as well as the underlying exclusion and procedural rules. We urge that both be retained and staff review be restored effective immediately.
In particular, in any rulemaking we urge that the no-action process be retained with consideration of reforms to sharpen the review process machinery—clarifying timelines, promoting direct engagement between issuers and proponents, and thereby reducing unnecessary demands on Commission staff. The amendments would:
establish a two-week engagement period after an issuer submits a notice of intent to exclude a shareholder proposal, during which the issuer and proponent may seek an agreement that may obviate the need for staff review of the notice;
provide specific timeframes for proponents to respond to exclusion notices, and confirm that the staff will consider any timely proponent response when issuing an advisory opinion;
extend the deadline for filing exclusion notices from 80 to 90 days, and clarify that the deadline runs from the earlier of the issuer’s proxy print deadline or its EDGAR filing deadline for the definitive Form DEF 14A; and
update the Rule to eliminate the archaic requirement that submissions be filed in paper copies.
Petitioners also recognize that Chairman Paul Atkins has signaled his intent for the Commission to abandon its role as an informal “referee” of the excludability of individual shareholder proposals and that the Division of Corporation Finance has paused review of most no-action requests. Therefore, while the petitioners believe that the no-action process should be retained and fully reinstated, the petition urges that any rulemaking not seek to limit the Commission’s role via a heavy handed wholesale rescission or other aggressive modification to the Rule without first rigorously evaluating less harmful alternatives including (a) limiting no-action letters to contested exclusion notices or significant policy matters or using other mechanisms, including those recommended in the petition to reduce the role of the staff or (b) retaining or refining the federal procedural and exclusion rules but leaving consideration of the validity of exclusion decisions to the courts. In the event it proposes substantial modifications or rescission of the no-action process or other elements of the Rule, the Commission should evaluate the impacts and costs associated with increased litigation already evidenced during the 2026 proxy season suspension, and how the existing substantive exclusions and procedures would function in the absence of Commission staff engagement on a proposal-by-proposal basis.
II. Statutory Authority
The Commission’s authority to adopt the requested amendments derives principally from Section 14(a) of the Securities Exchange Act of 1934 and the Commission’s broad authority to regulate corporate proxy statements in the public interest and for the protection of investors. The Commission has repeatedly affirmed its authority to establish and refine Rule 14a-8 in its various rule-making releases including Proposed Amendments to Rule 14a-8 Under the Securities Exchange Act of 1934 Relating to Proposals by Security Holders, Exchange Act Release No. 34-12598 (July 7, 1976), 41 Fed. Reg. 29,982 (proposed July 20, 1976) (to be codified at 17 C.F.R. pt. 240); Amendments to Rule 14a-8 Under the Securities Exchange Act of 1934 Relating to Proposals by Security Holders, Exchange Act Release No. 34-20091 (Aug. 16, 1983), 48 Fed. Reg. 38,218 (Aug. 23, 1983) (codified at 17 C.F.R. pt. 240); Shareholder Proposals Relating to the Election of Directors, Exchange Act Release No. 34-56161 (July 27, 2007), 72 Fed. Reg. 43,488 (proposed Aug. 3, 2007) (to be codified at 17 C.F.R. pt. 240); Substantial Implementation, Duplication, and Resubmission of Shareholder Proposals Under Exchange Act Rule 14a-8, Exchange Act Release No. 34-95267 (July 13, 2022), 87 Fed. Reg. 45,052 (proposed July 27, 2022) (to be codified at 17 C.F.R. pt. 240).
III. Interest of Petitioners
Petitioners include pension trustees and asset owners and organizations whose members or funds include individual investors and institutional fiduciaries—with long investment horizons and legal obligations to beneficiaries that make active stewardship not merely a choice but a duty. Many have filed shareholder proposals, and not all take the same perspective. All have relied on the proposal process as a practical tool for engaging companies on material risks, including through voting on shareholder proposals.
IV. Shareholder Proposals and the Rule 14a-8 Framework
Shareholders of public companies can submit proposals for consideration at annual meetings, providing a formal mechanism to influence corporate governance, strategy, and risk oversight. This process, which provides investors with important information about issues being raised by fellow shareholders, is made effective through the SEC’s proxy rules, particularly Rule 14a-8 (“the Rule”), which requires disclosure of eligible proposals in a company’s proxy statement so that shareholders are apprised of matters under consideration during the upcoming meeting and have an opportunity to vote on them through the proxy process.
To qualify a proposal under the Rule, shareholders must meet specified ownership thresholds, hold shares for a defined period, and comply with procedural requirements such as submission deadlines and proof of ownership. Rule 14a-8 also establishes thirteen enumerated grounds on which companies may exclude proposals, designed to screen out proposals that would not be likely to be significant to investors. The exclusions include, among other things, proposals that fall outside proper shareholder authority under state law, relate to ordinary business operations, contain misleading information, duplicate or conflict with other proposals, lack relevance, have already been substantially implemented, or fail to meet resubmission thresholds. The burden of justifying exclusion of a proposal falls on the issuer receiving the proposal, which must submit to the Commission an explanation of its reasons. Rule 14a-8(g), Rule 14a-8 (j)(2)(ii).
V. Removing a “Cornerstone” would Destabilize Corporate Governance in the US
The Commission’s Spring 2026 Unified Regulatory Flexibility Agenda includes a rulemaking to modify Rule 14a-8.[1] The petitioners are aware that Chair Paul Atkins and Commission members have articulated that the rulemaking may severely circumscribe or even rescind Rule 14a-8. Such changes may include allowing state law or corporate bylaws to delineate whether and when a shareholder proposal would be included on the corporate proxy statement or even eliminating entirely the ability of shareholders to submit proposals for the corporate proxy statement. Moreover, Executive Order 14366 (issued December 11, 2025),[2] while focusing on the role of proxy advisors, also asked the SEC to evaluate curtailing environmental, social and governance shareholder proposals through an SEC rulemaking.
Rule 14a-8 creates value and manages risk for shareholders and their companies, and provides structural integrity for investor-company relationships.
The Commission has previously recognized in its July 2022 Proposing Release that:
The shareholder proposal process has become a cornerstone of engagement between shareholders and company management. Shareholder proposals provide an important mechanism for investors to express their views, provide feedback to companies, exercise oversight of management, and raise important issues for the consideration of their fellow shareholders in the company’s proxy statement. Moreover, investor support for shareholder proposal campaigns over the years has helped to shape many current corporate practices and policies, such as annual director elections, majority vote standards for director elections, and proxy access rights for shareholders.[3]
The petitioners believe that eliminating that cornerstone would destabilize corporate governance in America, removing a critical tool for board and management accountability to shareholders that investors rely upon in their investment and stewardship strategies.
The result would be the silencing of many shareholder proposals—and with them, lost value and risk management benefits—followed by an era of uncertainty and chaos in corporate governance, with more litigation, more opposition to director elections and pay packages, and a more adversarial relationship between investors and their companies.
The Commission has honed the Rule over the course of decades to balance the interests of issuers, proponents, and shareholders who vote on the proposals. The Commission should respect that balance, instead of upsetting market norms and expectations. This petition proposes modest adjustments to the shareholder proposal exclusion process to increase predictability and efficiency and limit demands on SEC staff resources. It also proposes that, if the SEC considers radical changes to the Rule, it first consider less harmful alternatives.
VI. The No-Action Process and Its 2026 Suspension
Since 1947, disputes over whether a proposal could be excluded have been addressed through the SEC’s no-action process. The process for staff consideration of shareholder proposal no-action requests was extensively described in the Commission’s 1976 release “Statement of Informal Proposals for the Rendering of Staff Advice with Respect to Shareholder Proposals.”[4]
When a company seeks to exclude a proposal, it submits a request to the SEC’s Division of Corporation Finance explaining the legal basis for doing so. Shareholder proponents may submit a response.
SEC staff then issue an informal no-action letter indicating whether or not they concur that the proposal may be excluded. Staff reasoning is typically brief often just a few sentences—either finding “some basis” for the company’s arguments and stating that the staff would not recommend enforcement action if the company excludes the proposal, or, if they disagree with the company’s arguments, stating that they are “unable to concur.” Staff need not address all bases for exclusion if they concur with the company on one. If staff concur, the company may omit the proposal from its proxy statement with a degree of regulatory assurance; if staff do not concur, most companies allow the proposal to proceed rather than risk enforcement action.
Only a court can definitively determine whether an exclusion is validly applied. Therefore, the informal staff opinions are nonbinding. Nevertheless, the shareholder proposal no-action process has historically provided a relatively fast and even-handed avenue for guiding company action and developing interpretive guidance under Rule 14a-8.
Provisions promulgated in Rule 14a-8 reinforce fairness in the conduct of this informal process:
Rule 14a-8(k) provides that the proponent “should try to submit any response to [the SEC staff], with a copy to the company, as soon as possible after the company makes its submission. This way, the Commission staff will have time to consider fully [proponent’s] submission before it issues its response.”
Rule 14a-8(g) provides that “Except as otherwise noted, the burden is on the company” to persuade the Commission or its staff that it is entitled to exclude a proposal.
November 2025 Announcement
In November 2025, the SEC’s Division of Corporation Finance issued a statement announcing a policy applicable to the 2026 proxy season on how staff will assess and respond to company notifications under Rule 14a-8(j).[5] Under this policy, which was reportedly justified by a 2025 government shutdown that strained SEC staff resources, a company intending to exclude a shareholder proposal was still required to notify the Commission pursuant to Rule 14a-8(j), but the staff would not respond to the request or express any view on the company’s intended basis for exclusion. The Division reserved a single exception: where a company seeks to exclude a proposal under Rule 14a-8(i)(1) as an improper subject for shareholder action under state law.
To the extent that a company wanted a written response from the SEC regarding its exclusion notice, the policy provided for the staff to issue a letter, when requested by a company, stating that, based solely on the company’s or counsel’s unqualified representation and without evaluating its merits, it would not object to the omission of the proposal.
This no-objection process departed from the explicit terms of Rule 14a-8 in two distinct ways:
In issuing such “no objection” letters staff failed to accommodate and consider the proponent’s perspectives, a clear departure from the intent of Rule 14a-8(k);
The staff did not place the burden of persuasion on the company, instead accepting the company’s perspective without evaluating its persuasiveness, which is wholly inconsistent with Rule 14a-8(g).
Implementation of Rule 14a-8 by the Commission and the affected parties has historically depended on a combination of administrative oversight, evolving staff interpretation, and iterative dialogue between companies and investors. With the administrative layer removed during the 2026 proxy season interpretive authority shifted directly to issuers and the courts. Dispute resolution over exclusions migrated to litigation and market pressure.
An analysis of the impacts of withdrawing the no-action process during the 2026 proxy season demonstrated that the results were not neutral.[6] Instead:
Proposals were disadvantaged that sought to surface emerging issues such as the role and risks of AI because there was no applicable staff guidance for application by issuers and proponents.[7]
Proposals revised in form to comport with historical staff guidance on issues like micromanagement were not honored by receiving companies, leading to the exclusion of proposals that, in the normal course of the no-action process, would have been re-evaluated for consistency with the rules.
Issuers excluded proposals based on a risk assessment of whether they were likely to be subject to an injunctive suit by the proponent. In particular, issuers assessed that smaller shareholders with fewer resources were less likely to sue, rendering their proposals more easily excludable. Petitioners conclude that the abandonment of the no-action process was neither beneficial, in the public interest, nor consistent with the SEC’s mission to protect investors and maintain fair, orderly, and efficient markets.
Companies requested and received no-objection letters for proposals on topics for which the staff had consistently over the years refused to concur in a company’s analysis as a basis for exclusion, such as those relating to political spending.
Six lawsuits were filed by proponents seeking injunctive relief to include proposals on the proxy.
The suspension created chaos, not efficiency. Investors who had satisfied every requirement to file a proposal, but who lacked the litigation budget to fight for inclusion in court, were effectively silenced. Issuers fared no better: stripped of substantive SEC guidance, many chose the path of least resistance and included proposals they might have legitimately excluded, simply to avoid the litigation risk of guessing wrong.
The “no objection” letters that replaced substantive review made matters worse. They permitted companies to exclude proposals without presenting evidence (the exact opposite of what the Rule requires) while proponent submissions went unread. The Division’s policy did not merely or appropriately conserve staff resources dedicated to Rule 14a-8. In effect, it repealed a fundamental element of the rule.
Additionally, issuer behavior and outcomes from the most recent proxy season cannot be treated as determinative or predictive of how a permanent system lacking the no-action process would operate going forward. Companies this season were responding to a temporary suspension under conditions of considerable uncertainty; under an established regime without a neutral referee, issuers would likely grow far more aggressive in pursuing exclusions.
VII. Recommended Reforms to the Exclusion Notice Process
The suspension of the no-action process has highlighted areas in which the Rule can be improved for the benefit of both issuers and proponents—including encouraging the parties to resolve more of these disputes prior to SEC staff review. These improvements would reduce costs, ensure the Rule’s provisions are upheld, and restore an orderly, efficient no-action process.
This petition recommends technical reforms to ensure that Rule 14a-8 procedures and proposal exclusions align with the intentions of the Rule, provide clarity to the parties, and update the exclusion process to reflect common modern practices.
Our recommended changes (set forth in Appendix A) would accomplish the following refinements to the shareholder proposal exclusion process:
1. Modify the requirements for company submissions of exclusion notices.
a. Change the deadline for filing an exclusion notice from 80 to 90 days. Specify that this deadline must be calculated in advance of the company’s print deadline or proxy filing, whichever occurs earlier. This rectifies a problem that has emerged in recent years where the window for staff review of an exclusion request has been truncated by accelerated company deadlines for printing proxy statements which precede the formal date for submission of the proxy form for EDGAR.
b. Establish a mandatory two week engagement window for the proponent and issuer to seek a negotiated agreement in the two weeks after submission of the exclusion notice, potentially eliminating the need for a staff advisory opinion.
c. Guarantees that the staff advisory opinions issued after the engagement window continue to place the burden of persuasion squarely on the issuer to present concrete evidence supporting the excludability of the proposal. This procedural safeguard precludes the issuance of “no objection” letters based on the unqualified representations of issuers while ignoring rebuttal evidence from proponents.
2. Set clear timeframes for a proponent to respond if a company requests a staff advisory opinion:
a. Allow 14 business days for responses to procedural objections (such as proof of ownership) and 30 days for responses to substantive exclusions.
b. Reinforce that the staff must consider timely submitted proponent perspectives before issuing any advisory opinion.
3. Eliminate outdated paper copy submissions requirements:
a. Excise obsolete language in the existing Rule requiring the submission of six paper copies. This would reflect the modern reality that all submissions are now processed electronically.
In addition, to the extent that the Commission proposes rescinding the no-action process, we recommend that it consider less harmful alternatives, including our proposed refinements that would reduce the demands on staff time. Other less disruptive alternatives to reduce the resource demand of the no-action process have also been successfully deployed by the staff in prior instances and should be evaluated in lieu of outright rescission of the no-action process. Notably, from 2019 to 2022, the Division of Corporation Finance staff successfully utilized a summary tracking chart[8] to record its perspective on the excludability of individual shareholder proposals for which it had received exclusion notices, but only issuing no-action letters stating a rationale in a limited number of matters where the staff identified a pressing need to clarify a specific interpretive position. This and similar resource saving alternatives must be evaluated as viable options rather than revoking the highly valued no-action process entirely.
VIII. Alternatives to Eliminating the Substantive Framework and Procedures of Rule 14a-8
We are advised that the Commission may also, beyond revoking the no-action process, consider more severe changes to the shareholder proposal rule, such as deferring entirely to state law or corporate bylaws rather than maintaining consistent federal exclusions and procedures. Doing so would severely undermine this cornerstone of U.S. corporate governance, creating unacceptable regulatory uncertainty and litigation risk for both proponents and issuers, and create impediments for access to the Rule for smaller shareholders.
If the Commission issues such a proposed rulemaking rescinding or severely curtailing Rule 14a-8, we urge the Commission to also evaluate alternatives that maintain the federal rules while eliminating the no-action process. This evaluation should include consideration of whether the current rules provide sufficient clarity, or could be refined to be more objective to avoid the need for litigation. It should also consider the potential role of engagement to promote modification or withdrawal of proposals, which would reduce the need for the no-action process.
Outright rescission of Rule 14a-8 would upset a longstanding balance between investors and their companies built around the Rule’s exclusions and procedures for submitting shareholder proposals that appear on corporate proxy statements. For example, the relevance exclusion, Rule 14a-8(i)(5), considered and refined by the Commission over numerous administrations, screens for materiality to the specific issuer, relieving companies of an obligation to respond to, and protecting shareholders from consideration of, trivial or irrelevant proposals. The resubmission exclusion, Rule 14a-8(i)(12), considers the voting outcomes from the previous years and spares shareholders and the board from perennial re-litigation of proposals that have garnered only minimal support. The eligibility thresholds for filing proposals set the entry price, demanding a genuine and durable stake before the Rule may be invoked.
The Rules provide a low-cost and uniform mechanism for proposal access across every public company. Shareholders have an impressive record of deploying this process to elevate corporate consideration of substantial near and long-term risks. Shareholder proposals often raise critical issues that the board or management might otherwise neglect, helping to counteract the natural proclivity of corporate boards and managers to bury issues that could be of concern to investors. As financial economist Michael C. Jensen observed, corporate reporting and market communications are often shaped by incentives to meet or beat market expectations rather than to present a full account of risk.[9] Former SEC Chairman Arthur Levitt similarly warned in 1998 that the drive to satisfy earnings expectations could displace faithful representation with “a game of nods and winks.”[10] Management is often incentivized to short-term profit and setting strategy accordingly, while ignoring long-term risks. These concerns remain salient today, and shareholder proposals play an important role in counteracting positive spin or corporate concealment that can range from mere puffery to greenwashing and securities fraud.[11]
Proposals have called attention to company mismanagement and poor governance, warned of company-related financial collapses, public health crises, environmental failures, labor violations, failure to demonstrate that the interests of investors are being adequately considered and addressed. They have also successfully pushed to improve the governance of emerging technologies that will be central to the 21st century. In doing so, these shareholder proposals identified material risks that management had failed to adequately address before the ultimate costs to shareholders and the company became catastrophic and undeniable.[12]
Eliminating the Rule would harm investors and markets that rely upon consistent standards and procedures for placing proposals on proxies across public companies. It would inevitably create a Tower of Babel comprised of fragmented, conflicting filing and technical requirements spanning disparate state corporate laws and idiosyncratic company bylaws. Interpretation and enforcement would become entirely dependent on the slow, costly machinery of private litigation and evolving inconsistent judicial interpretations. This would suppress the availability of the proposal process and severely reduce transparency on material investor concerns. Costly litigation would permanently destabilize the established working relationships on which issuers and investors rely. Any rulemaking to significantly alter the Rule must fully account for the systemic harm inflicted on the market and exhaustively consider less harmful alternatives, as requested by this petition.
Conclusion
The right to file a shareholder proposal that appears on the corporate proxy statement is not a courtesy extended by management. It is a foundational aspect of corporate ownership. Shares carry voting rights, and under long-established corporate and federal frameworks, those voting rights have long included the ability to put hard questions—about strategy, risk, and disclosure—before fellow owners. Because these proposals are advisory, they do not overrule management. Instead, they inform it, pressure it, and aggregate the judgment of the people whose capital is at risk. This voice is also a source of market efficiency. Engaged owners surface information, press for crucial disclosures that let the whole market price risk more accurately, and discipline managers who would otherwise be insulated from accountability. Empirical evidence on shareholder engagement demonstrates that successful, well-targeted engagements lead to positive abnormal returns at targeted firms, while unsuccessful ones are not value-destructive.[13] Curtailing that voice weakens one of the few mechanisms through which dispersed owners can hold management to account.
The reforms in this petition are narrow, practical, and overdue and will protect a right that has stood for over 80 years. The Commission should adopt them and reject other ideas that would eliminate or harmfully modify this important SEC rule.
Sincerely,
Steven Rothstein
Chief Program Officer, Ceres
Dave Wallack
Executive Director, For the Long Term
Josh Zinner
Chief Executive Officer, Interfaith Center on Corporate Responsibility
Thomas P. DiNapoli
New York State Comptroller
Sanford Lewis
Director, Shareholder Rights Group
Bryan McGannon
Managing Director, US SIF
[1]https://www.reginfo.gov/public/do/eAgendaViewRule?pubId=202510&RIN=3235-AN47 (“The Division is considering recommending that the Commission propose rule amendments to modernize the requirements of Exchange Act Rule 14a-8 to reduce compliance burdens for registrants and account for developments since the rule was last amended.”).
[2]https://www.whitehouse.gov/presidential-actions/2025/12/protecting-american-investors-from-foreign-owned-and-politically-motivated-proxy-advisors/
[3] Substantial Implementation, Duplication, and Resubmission of Shareholder Proposals Under Exchange Act Rule 14a-8, Exchange Act Release No. 34-95267 (July 13, 2022), 87 Fed. Reg. 45,052 (proposed July 27, 2022).
[4] Statement of Informal Procedures for the Rendering of Staff Advice With Respect to Shareholder Proposals, Exchange Act Release No. 34-12599 (July 7, 1976), 41 Fed. Reg. 29,989 (July 20, 1976).
[5]https://www.sec.gov/newsroom/speeches-statements/statement-regarding-division-corporation-finances-role-exchange-act-rule-14a-8-process-current-proxy-season
[6]https://static1.squarespace.com/static/5d1f9923ca0f4800011d443a/t/69eff37e7fe4671d80fc6256/1777333118857/
SRG+Report+Final+04.27+%2B+website+link.pdf
[7]Id. at 13. Overall, 28% of exclusions in the 2025–2026 season asserted an (i)(7) ordinary business basis. In a majority of those—roughly 64%—companies excluded proposals even though prior SEC staff precedent did not clearly resolve whether exclusion was appropriate.
That 64% category is not uniform. It consists predominantly of two types of proposals that have historically required staff interpretation: (1) revised proposals that build on earlier models but modify language or scope, often to respond to prior SEC guidance or staff determinations on issues such as micromanagement, and (2) novel or innovative proposals that introduce new topics or structures not previously addressed by staff decisions.
[8]https://www.sec.gov/divisions/corpfin/shareholder-proposals-2019-2020.pdf
[9]https://papers.ssrn.com/sol3/papers.cfm?abstract_id=1894304
[10]https://www.sec.gov/news/speech/speecharchive/1998/spch220.txt
[11]https://business.rice.edu/wisdom/companies-talk-more-clearly-when-business-booming
[12]https://www.iccr.org/reports/shareholder-proposals-an-essential-investor-right/
[13]https://www.researchgate.net/publication/253236822_Active_Ownership
Appendix A: Proposed Markup
(j) Question 10: What procedures must the company follow if it intends to exclude my proposal?
(1) If the company intends to exclude a proposal from its proxy materials, it must file its reasons with the Commission no later than 80 90 calendar days before the earlier of its print deadline or the date it files its definitive proxy statement and form of proxy with the Commission. The company must simultaneously provide you with a copy of its submission. The Commission staff may permit the company to make its submission later than 80 90 days before the company files its definitive proxy statement and form of proxy, if the company demonstrates good cause for missing the deadline.
(2) The company must file six paper copies of submit the following:
(i) The proposal;
(ii) An explanation of why the company believes that it may exclude the proposal, which should, if possible, refer to the most recent applicable authority, such as prior Division letters issued under the rule; and
(iii) A supporting opinion of counsel when such reasons are based on matters of state or foreign law.
The two calendar weeks after submission of a no-action request is considered the engagement period, in which the parties have an opportunity to engage and converge on an agreement for withdrawal of the no-action request.
If the engagement period ends without agreement, SEC staff may review the parties’ submissions and issue an advisory opinion—including but not limited to all instances in which the issuer and proponent have raised contested issues that require resolution.
(k) Question 11: May I submit my own statement to the Commission responding to the company’s arguments?
Yes, you may submit a response, but it is not required. The staff will consider your submission as well as the company’s. After the company makes its submission you should try to submit any response to us, with a copy to the company, within 14 business days of receipt of the exclusion notice for any procedural objection such as proof of ownership, and within 30 days to respond to any of the enumerated exclusions as soon as possibleafter the company makes its submission. This way, the Commission staff will have time to consider fully your submission before it issues its any response. You should submit six paper copies of your response.
Americans for Financial Reform (AFR) Petition
Endorsed as of July 20, 2026 by 12,586 Individuals
To: Securities and Exchange Commission
Dear Chairman Atkins and Commissioners Peirce and Uyeda,
We write on behalf of workers, retirees, pension beneficiaries, consumers, and communities who deserve a financial system that serves the public good rather than concentrating power in the hands of wealthy insiders. We urge you to preserve the shareholder proposal rule as a critical tool that allows shareholders to hold corporate management accountable and challenge the growing concentration of corporate power in our economy. The SEC should protect investors and fair markets — not help consolidate power in the hands of billionaire oligarchs, corporate executives, and other insiders.
For eighty years, the ability of shareholders to raise questions before the companies they own has been one of the most effective ways for regular shareholders — including workers’ pensions, responsible asset managers, and small investors — to weigh in on corporate decision-making. That is precisely why these rights are under attack. Weakening the proposal process would silence investors on workers’ rights, climate risk, racial equity, political spending, executive pay, and other issues that affect companies and the broader economy.
When investors ask a clothing retailer to account for supply chain vulnerabilities, they are protecting brand equity and long-term profitability. When they ask a pharmaceutical company to address legislative risk embedded in its earnings guidance, they are doing the analytical work that sound investing requires. When they flag water scarcity exposure for agricultural, beverage, semiconductor, or mining companies, they are surfacing risks that conventional financial filings routinely omit — risks that eventually become losses borne by ordinary shareholders. When they ask for accountability from management for not respecting workers’ freedom of association, they are pushing companies to address risks that come from a low-morale, high-turnover workforce.
Corporate management should not get to decide which investor concerns are acceptable and which are too inconvenient to appear on a ballot. Whether shareholders are raising concerns about climate risk, labor standards, political spending, racial equity, executive compensation, or corporate misconduct, the point is the same: investors need meaningful tools to challenge insiders and protect the long-term value of the companies they own.
If the shareholder proposal process is curtailed, the practical result would be a transfer of power: away from workers’ pensions, small shareholders, and the broader investing public — and toward corporate insiders and a small circle of wealthy and powerful actors. Blind spots will accumulate. Risks that could have been surfaced early will compound, spreading across companies and sectors until they become systemic.
The boards and executives of public companies should answer to regular shareholders instead of being insulated from their input and accountability. That principle is essential for investor protection and fair markets that serve everyone — not just a powerful few.
Investor Coalition, NY Comptroller Petition SEC to Fix – Not Gut – Shareholder Proposal Rule
July 23, 2026
For media inquires please contact Esperanza@focalpointstrategygroup.com
Petition urges Commission to adopt practical reforms that streamline the no-action process and evaluate less disruptive alternatives before considering major changes to Rule 14a-8
WASHINGTON, D.C. — A coalition of investor groups and New York State Comptroller Thomas P. DiNapoli filed a rulemaking petition today urging the SEC to recalibrate, rather than dismantle, Rule 14a-8, the federal rule governing shareholder proposals on corporate proxy statements.
The petition responds directly to SEC Chairman Paul Atkins, who told the Society for Corporate Governance recently that this season's suspension of staff review of company arguments for excluding proposals cut resource demands and suggested he may make that suspension permanent. Atkins has also floated shifting shareholder proposal oversight to state law or company bylaws, and a White House Executive Order suggested SEC consideration of scrapping the rule outright.
The petitioners - DiNapoli, Ceres, the Interfaith Center on Corporate Responsibility, the Shareholder Rights Group, US SIF, and For the Long Term - argue that if the SEC is going to do a rulemaking, there's a more efficient fix that doesn't require abandoning investor protections.
Two core asks:
Streamline the proposal exclusion process before it reaches the SEC. The petition calls for a mandatory two-week engagement window after a company issues an exclusion notice, clear response deadlines for proponents, modestly extended filing windows, and an end to obsolete paper-filing requirements — changes meant to resolve more disputes privately and make SEC review faster when it is needed.
Require the SEC to test less drastic options first. Before rescinding the no-action process, handing oversight to state law, or otherwise gutting Rule 14a-8, the petition says the Commission is obligated under the Administrative Procedure Act to evaluate less harmful alternatives — including the procedural fixes above.
The petition cites this year's experience as the cautionary tale: with substantive no-action review suspended, costs didn't disappear, they moved — onto investors and companies navigating more uncertainty, inconsistent outcomes, and litigation. As the filing puts it: "The suspension created chaos, not efficiency."
Alongside the petition, investors also filed:
Citizen petitions with nearly 32,000 signatures opposing rescission of the rule
A FOIA request (Shareholder Rights Group and Democracy Forward) seeking records on the SEC's reported "previewing" of rulemaking plans with select constituencies
U.S. Senator Elizabeth Warren (D-MA): “Rescinding SEC Rule 14a-8 would be another giveaway to corporations and their executives at the expense of workers and retirees. From preventing shareholders from bringing lawsuits on company misconduct to rolling back disclosures key to investors, President Trump’s SEC seems more interested in stifling ordinary investors’ voices than protecting their rights.”
Sanford Lewis, Director, Shareholder Rights Group: "Good regulation starts with solving the right problem. If the Commission's objective is to reduce demands on staff resources, there are practical ways to accomplish that without abandoning a regulatory framework that has served investors, companies, and the markets for decades."
New York State Comptroller Thomas DiNapoli: "For more than eighty years, shareholder proposals have been a critical tool for investors to hold boards and management accountable. The right to include shareholder proposals on corporate proxies has driven reforms that strengthened American companies and protected shareholder value. Suspending the no-action process shifted costs onto investors and companies and fostered uncertainty, inconsistency, and litigation. We’re offering the SEC a better option: targeted fixes that ease the burden on staff while keeping a neutral referee on the field. That’s good for shareholders and good for the companies we invest in.”
Illinois State Treasurer Mike Frerichs: "Ultimately, weakening or taking away the shareholder proposal process is not going to make the sustainability risks for companies go away. It’s just going to make it harder for shareholders to raise them," Illinois State Treasurer Michael Frerichs said. "So naturally I am concerned that eliminating the 14a-8 process would reduce the rights of shareholders and limit our ability to engage companies facing material sustainability risks."
Dave Wallack, Executive Director, For the Long Term: "Long-term investors need functioning institutions. The choice before the SEC is not between efficiency and investor rights—it's between thoughtful modernization and unnecessary disruption. Before abandoning a framework that has served our capital markets for decades, the Commission should fully evaluate the practical, lower-cost alternatives already on the table."
The petition calls its recommendations "narrow, practical, and overdue," and comes as the SEC weighs potential Rule 14a-8 amendments on this year's agenda.
About For the Long Term
For the Long Term (FTLT) is a nonpartisan organization dedicated to strengthening the institutions, leaders, and policies that drive long-term economic growth and prosperity. FTLT works with state financial leaders, institutional investors, and market participants to advance practical solutions that promote long-term value creation, effective stewardship, and resilient capital markets. Through convenings, research, and strategic partnerships, FTLT helps public officials and investors navigate emerging challenges—from technological change and demographic shifts to corporate governance and economic competitiveness—while building the capacity of those entrusted with managing public resources. FTLT believes that strong institutions, informed leadership, and a long-term perspective are essential to ensuring that American markets remain the most dynamic, innovative, and trusted in the world.
Additional Quotes
“Our nation's capital markets system works best when investors and companies work together. The shareholder proposal process is an essential tool that allows investors to have direct dialogue with company management about material risks to the business. Rolling back this process will cause immense harm to our capital markets and will undermine investors' freedom to engage with the companies they own.” Andrew Collier, Senior Director, Freedom to Invest, Ceres. Phone: 202-774-0171. Email: acollier@ceres.org
About Ceres
For more than 35 years, Ceres has been at the forefront of building business leadership and supporting innovative market and policy solutions to address the world’s most pressing sustainability issues. We work with investors, companies, and policymakers to advance actions that reduce emissions and build a cleaner, more resilient economy – all in a way that advances justice and equity.
“ICCR has been deeply concerned about the ways this proposed attack on shareholder rights could impact our members and the wider landscape of corporate governance and accountability. These changes being suggested by the administration would undermine a tool that generations of Americans have come to depend upon to safeguard the long-term value and viability of their investments. At a time of growing unease about the condition and direction of the U.S. economy, Chair Atkins should be seeking to strengthen rather than undermine investor protections.” Josh Zinner, CEO, ICCR email: jzinner@iccr.org
About the Interfaith Center on Corporate Responsibility (ICCR)
The Interfaith Center on Corporate Responsibility (ICCR) is a broad coalition of more than 300 institutional investors collectively representing over $4 trillion in invested capital. ICCR members, a cross-section of faith-based investors, asset managers, pension funds, foundations, and other long-term institutional investors, have over 50 years of experience engaging with companies on environmental, social, and governance (“ESG”) issues that are critical to long-term value creation. ICCR members engage hundreds of corporations annually in an effort to foster greater corporate accountability. Visit our website www.iccr.org and follow us on LinkedIn, Bsky Social, and Facebook.
"Shareholder proposals help investors identify risks before they become larger problems. Making it harder for shareholders to question management does not make those risks disappear. It simply makes it harder for companies, boards, and investors to see them." Jonas Kron, Chief Advocacy Officer, Trillium Asset Management, LLC email:jkron@trilliuminvest.com
About Trillium Asset Management, LLC
Trillium Asset Management offers investment strategies and services that seek to advance humankind towards a global sustainable economy, a just society, and a better world. For over 40 years, the firm has been at the forefront of ESG thought leadership and draws from decades of experience focused exclusively on responsible investing. Devoted to aligning stakeholders’ values and objectives, Trillium combines impactful investment solutions with active ownership.
“Communication between investors and their portfolio companies is mutually beneficial. Restricting investors' ability to express their preferences directly —through filing or voting on shareholder proposals — will produce votes against directors that convey no clear or constructive signal to the companies." Elizabeth R. Levy, CFA, Managing Director, Clean Yield Asset Management email:liz@cleanyield.com
About Clean Yield Asset Management
For more than 40 years, Clean Yield Asset Management has used the power of investing to meet the financial goals of our clients while moving society toward a more just and sustainable future. Clean Yield works with individuals, families, family trusts, foundations, and aligned nonprofit clients to implement an investment strategy aligned with their progressive values. Our strategies ensure that our clients' investments are not only financially rewarding but also aligned with their values and contributing to a more sustainable world.
“The shareholder proposal process benefits the entire capital market value chain, not just proponents. Shareholder proposals are one of the few formal mechanisms investors have to raise material governance and risk issues directly with boards. The process is an efficient means to surface existing and emerging risks and increases transparency leading to better investment decision making.” Bryan McGannon, Managing Director of US Sustainable Investment Forum bmcgannon@ussif.org
US SIF Sustainable Investment Forum
They are the preeminent voice advancing sustainable investing. Members, who represent $5 trillion in assets under management or advisement, support US SIF’s mission to rapidly shift investment practices toward sustainability, focusing on long-term investment, the generation of positive social and environmental impacts and supporting the shift toward a more resilient and equitable planet and society. https://www.ussif.org
Governance Proposals Dominate the 2026 Proxy Season
These are highlights from an article posted by ISS-Corporate analyzing the 2026 season.
Shareholder Proposal Volume Falls to a Five-Year Low
Against these backdrops, the overall volume of shareholder proposals submitted and advanced to a vote has declined to a five-year low.
While the overall volume of proposal submissions and those appearing on the final ballot declined, governance-related proposals recorded an increase in overall volume. This relative resilience highlights the continued prioritization of core shareholder rights and board accountability mechanisms among investors as well as changes in proponents’ tactics.
In contrast, environmental and social proposals extended their downward trajectory with further declines in both the number of proposals submitted and proposals voted, reflecting a more selective investor approach toward these topics. Anti-ESG proposals, which had been rapidly increasing in volume, saw a decline as well, though they continue to comprise a meaningful portion of overall proposal volume.
The shift in proposal activity likely reflects a combination of factors, including the evolving political and regulatory landscape, the mixed success many environmental and social proposals have achieved in recent years, and the impacts of recent SEC actions.
Changes to the SEC’s shareholder proposal framework and no-action process appear to have altered the calculus for proponents, potentially discouraging some submissions while incentivizing others to pursue a more focused strategy. As a result, some proponents appear to have reduced proposal activity altogether, while others have become more selective in targeting issues and companies, or have redirected their efforts toward governance-related topics that historically receive broader shareholder support and face fewer ideological headwinds.
Taken together, these developments suggest that rather than signaling a diminished interest in environmental and social issues, the decline in proposal volume may reflect a strategic recalibration by proponents seeking to maximize impact and improve the likelihood of gaining meaningful shareholder backing.
ISS-Corporate’s Approach to Proxy Season Insight
The 2026 proxy season highlights significant changes in shareholder proposal activity. While overall proposal volume declined, governance-focused proposals remained resilient and continued to receive the strongest investor support, highlighting sustained shareholder focus on board accountability and shareholder rights. Meanwhile, environmental and social proponents appear to be recalibrating their tactics, adopting a more targeted approach.
As the 2026 proxy season concludes, these trends offer important signals about evolving investor priorities and the issues most likely to shape shareholder engagement and voting decisions in the years ahead. ISS-Corporate’s Compensation & Governance Advisory team helps companies analyze shareholder proposal trends, benchmark governance practices against market expectations, assess potential areas of shareholder concern, and develop engagement and disclosure strategies that align with investor priorities. Through data-driven insights and practical governance guidance, we support boards and management teams in preparing for future proxy seasons and strengthening shareholder relationships in an increasingly dynamic governance landscape.